One broker, from first call to settlement.
Car, caravan, boat, motorbike, equipment and business finance. Your broker compares the panel so you do not have to. Self-employed and ABN welcome.
Sending an enquiry doesn't affect your credit file
Some of the lenders on our panel
Car, bike andcaravan loans
Secured against what you're buying. We compare lenders on our panel and show you the options before you commit. Your rate depends on your credit history, the age of what you're buying and the loan amount.
Asking for a quote won't affect your credit file.
*The comparison rate is calculated on a secured loan of $30,000 fixed for a term of 5 years, effective 13/11/2026 and subject to change. WARNING: The comparison rate is true only for the examples given and may not include all fees and charges. Different terms, fees or other loan amounts may result in a different comparison rate. Rates are for applicants who meet the lender's criteria. T&Cs and lending criteria apply.
What we finance
Every asset. Every situation.
From personal vehicles to commercial fleets, Morella Finance covers the full spectrum of asset finance in Australia.

Tell us what you need
A quick two-minute form. Loan type, asset value and a little about your situation. Nothing you wouldn't tell your bank.
We compare the panel
Your broker searches the panel for a rate and structure that suits your profile. No bank-branch roulette.
See your options
We present the best matches, explain the differences and answer any questions before you commit to anything.
Approved and funded
Once you choose, we handle the paperwork end-to-end. Pre-approval is possible the same day for many straightforward applications.
Why use a broker
Your bank shows you one rate.
A broker shows you the panel.
Broker vs bank,
a real comparison
Self-employed and low-doc specialists
ABN holders, sole traders and companies get access to specialist lenders that banks will not show you.
No credit impact to enquire
Getting a quote with us does not trigger a credit enquiry. Check your options first, decide later.
Structure, not just rate
Rate is one factor. Balloon payments, loan term and early-repayment terms all affect the real cost. We look at the full picture.
Real people, not call centres
Finance is a big decision. Talk it through with an experienced broker.
Every enquiry is answered by a broker who explains your options in plain English, compares lenders, and stays with you from the first call to settlement.
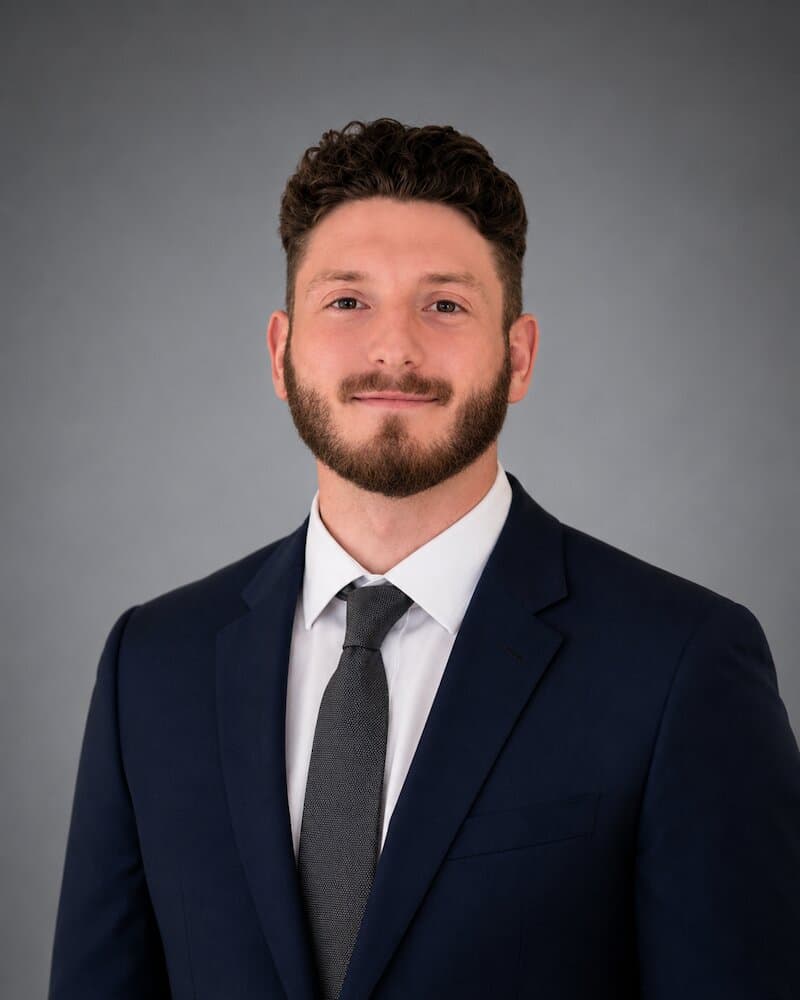
Joseph Nowland
Director and Senior Finance Broker
The broker who answers your first call is the broker who takes you to settlement.
Who we help
Built for every borrower.
First-time buyers
- No finance history? No problem.
- We explain every step before you sign.
- Thin or no credit file considered.
Self-employed and ABN holders
- Low-doc and alt-doc options available.
- Flexible income verification.
- Loans for brand new ABNs.
Business owners
- Chattel mortgage, finance lease and hire purchase.
- Preserve working capital.
- Potential GST and depreciation benefits.
Refinancers
- Refinance mid-term.
- Consolidate multiple loans into one payment.
- No disruption to daily operations.
Straight answers to the questions everyone asks.
Still have something on your mind? Talk to a broker. No scripts, no pressure.
Get my quoteNot necessarily. The point of using a broker is to end up with a better deal than you would find on your own. We compare our panel on your behalf, including specialist lenders your bank will never show you, and we negotiate the rate and structure with the lender rather than accepting the first offer. You are under no obligation to proceed. Full details are available in our Credit Guide.
Getting a quote does not require a credit enquiry. A formal application does involve a credit check, but we explain exactly when that happens before we proceed. Some lenders do not require a credit check for pre-approval.
Yes. Our panel includes lenders who specialise in self-employed, low-doc and ABN borrowers, including some who will consider a brand-new ABN and others who accept as little as one to two years of self-employment history for a low-doc assessment.
Pre-approval is possible the same day for many straightforward applications. Complex situations, adverse credit or unusual assets can take longer, and we tell you upfront if yours is one of them.
Car, caravan, boat, motorbike, commercial truck, equipment, business assets and personal loans. If you are not sure whether your asset qualifies, contact us and we will let you know.
No. We are a credit representative with a large lender panel and we are not owned by any lender. How we work, and how we manage any conflict of interest, is set out in full in our Credit Guide.
Learning centre
Understand the finance before you sign
Straightforward guides on how each type of finance works, what lenders look at and what to check before you commit. Pick a category to see the latest.
 10 guidesCar financeNew, used, refinance and private sale car loans for employed and self-employed buyers.Explore car finance
 Buying a Car Privately: How Finance Works for Private SalesPrivate sales often mean better prices, but the finance process differs from a dealer purchase. Here is how private sale car loans work, step by step.
 Comparison Rate vs Interest Rate: What's the Difference?Two rates appear on every Australian loan ad, and they rarely match. What the comparison rate includes, why it exists and which one to compare on.
 Car Finance for Self-Employed and ABN HoldersNo payslips does not mean no car loan. How self-employed Australians and ABN holders get car finance, what documents lenders accept.
 How Your Credit Score Affects Your Car LoanYour credit file shapes which lenders will approve you and on what terms. How scores work in Australia, what lenders actually look at.See all 10 car finance guides
 8 guidesCaravan financeCaravans, camper trailers and motorhomes, bought from a dealer or privately.Explore caravan finance
 Caravan Finance for Self-Employed and ABN HoldersRunning your own show should not stand between you and a caravan. What lenders actually ask of ABN holders, and how to place the application well.Australia's caravans are getting heavierAustralia's caravans are getting heavier. Vans over 2,500kg tare rose 32% in two years. See caravan weight by state from BITRE's 2026 registration data.New vs Used Caravan Finance: Which Is Right for You?New and used caravans borrow the same way but are assessed quite differently. How lender appetite, age rules and structure shift between the two.How Caravan Loan Pre-Approval WorksSorting your caravan budget before you shop changes how dealers and private sellers treat you. How pre-approval works and how to use it well.See all 8 caravan finance guides
 7 guidesMarine financeBoats, jet skis and marine refinancing, with the checks that come with buying on water.Explore marine finance
 Boat Finance for Self-Employed BuyersSelf-employed Australians buy a lot of boats, and lenders know it. The documents that work, how low-doc marine lending runs.How Boat Loan Pre-Approval WorksPre-approval settles your boat budget before you go shopping and strengthens your hand at boat shows, brokers' yards and private sales. How it works.New vs Used Boat Finance ComparedLenders read a new boat and a used one differently. Hull age, engine hours, surveys and private sales all shift the finance, and this guide explains how.What Deposit Do You Need for a Boat Loan?Plenty of boat loans settle with nothing down, and others are stronger with a contribution. What a deposit does to the loan, and what can stand in for cash.See all 7 marine finance guides
 5 guidesMotorbike financeRoad, sport and commuter bikes, secured against the bike or unsecured.Explore motorbike finance
 Secured vs Unsecured Motorbike Loans ExplainedWhether your bike loan is secured or unsecured changes the lender pool, the assessment and what happens if things go wrong.New vs Used Motorbike FinanceNew and used bikes get different treatment from lenders. Age caps, kilometres, modifications and private sales all change the finance, and here is where.What Deposit Do You Need for a Motorbike Loan?Some bike loans need no deposit at all, others benefit from one. How deposits change the loan, what counts as a deposit, trade-ins.Buying a Motorbike Privately: How Finance WorksPrivate bike sales can be the best value on two wheels, but the finance runs differently. Ownership checks, PPSR searches, settlement.See all 5 motorbike finance guides
 8 guidesCommercial financeUtes, trucks and work vehicles for ABN holders, including low-doc options.Explore commercial finance
 How Fleet Finance WorksOnce a business runs several vehicles, funding them as one arrangement beats accumulating loans. Facilities, structures and replacement cycles.GST and Tax Treatment of Vehicle Finance in Plain EnglishHow GST, deductions and depreciation sit alongside business vehicle finance, laid out simply for the conversation with your accountant.New ABN? How to Finance a Work VehicleA young ABN narrows the lender pool without closing it. What lenders want to see, and the evidence that carries a new business over the line.Chattel Mortgage vs Lease vs Hire Purchase: Which Structure Suits Your Business?Three structures finance most Australian business vehicles, and they differ on ownership, tax mechanics and what happens at the end of the term.See all 8 commercial finance guides
 5 guidesEquipment financeMachinery, plant and business equipment financed against the asset itself.Explore equipment finance
 Machinery Finance: New, Used and Private SaleHow machinery finance treats new stock, used gear and private sales, from excavators to tractors and forklifts, and where each deal tends to fit.Should You Buy or Finance Business Equipment?Paying cash feels virtuous and is sometimes wrong. How to weigh working capital, asset life and opportunity cost when choosing to buy outright or finance.How to Finance Equipment as a Sole TraderSole traders reach the same equipment finance market as companies. How you are assessed, the documents that work and what a new ABN changes.Low-Doc Equipment Finance ExplainedLow-doc equipment finance funds business assets on alternative income evidence. Who it suits, the documents lenders accept.See all 5 equipment finance guides
 6 guidesBusiness loansUnsecured business loans, overdraft facilities and capital raise finance.Explore business loans
 Capital Raise Finance: Funding Growth Without Property SecurityHow Australian businesses fund expansion without offering property as security, the debt structures available and what lenders assess.Business Overdraft vs Business Loan: Which Do You Need?The practical differences between a business overdraft and a term loan, how each structure works, and which funding needs suit which of the two.How Business Loan Assessment Works: What Lenders Look AtWhat Australian lenders actually assess on a business loan application, from trading history and bank statements through to serviceability and credit conduct.How Fast Can You Get a Business Loan in Australia?Realistic business loan timelines in Australia, how fast approval and funding actually happen, and what slows applications down.See all 6 business loans guides
 5 guidesPersonal financeTravel, weddings, home improvements and debt consolidation.Explore personal finance
 Travel Loans: What to Know Before You BorrowHow travel loans work, when borrowing for a trip is reasonable and how to structure holiday finance so the repayments end soon after the trip does.Wedding Loans: Financing the Day Without the StressHow wedding loans work in Australia, how to decide what to borrow responsibly and how to structure finance so the celebration does not follow you for years.Fixed vs Variable Personal Loans ExplainedWhat fixed and variable personal loans actually mean for your repayments, flexibility and planning, and which suits the way you intend to repay.
 Debt Consolidation Loans: How They Work and When They HelpHow debt consolidation loans work, when rolling debts into one actually improves your position, and the situations where consolidation makes things worse.See all 5 personal finance guides