1 of 3
Secured Boat Loan
- Security required
- Yes, vessel and trailer
- Typical terms
- 1 to 7 years
- Balloon available
- Yes
- Best suited to
- Trailer boats to cruisers
- Turnaround
- Possible same day

Whether you're buying a runabout, a cruiser or a jet ski, we compare marine lenders across our full panel to find a structure that suits your situation.
Same day pre-approval possible. No obligation to proceed.
Broker vs bank,
a real comparison
One application, many lenders
We submit once and compare across the marine lending market, saving you time and protecting your credit file.
Vessel-specific structures
Marine finance has its own quirks. We match the loan structure to the vessel type and your intended use.
Honest rate comparison
Banks show you their rate. We show you dozens. The difference often means thousands over the life of the loan.
Support from enquiry to settlement
We handle lender negotiations, paperwork and communication so you can focus on the water.
The process
Share details about what you're buying, your budget and your financial situation.
We search the market to find rates and structures suited to your loan.
We present your matches with rates and terms explained simply before you decide.
Once you choose, we handle the rest. Your loan settles and you take delivery.
Some of the lenders on our panel
Compare marine finance types side by side
The most common structures for boats and personal watercraft, and where each fits.
Secured Boat Loan
Jet Ski Finance
Low-Doc (ABN)
Step 1 of 5
Marine loans are secured loans where the vessel, engine and its trailer often form the security. Terms typically run one to seven years and cover runabouts, cruisers, sailing boats, jet skis and commercial vessels.
Lenders assess vessels on age, type, value and how they are identified. Registered vessels with a clear Hull Identification Number are straightforward, while older boats, one-offs and vessels bought privately need lenders with more flexible marine policy.
Boat-plus-trailer packages can usually be financed as one asset, and many lenders will include safety equipment and electronics fitted at purchase in the loan amount.
Boats are long-life assets, and financing spreads the cost over the years you'll actually use it, rather than draining your savings before you've even launched it. That leaves cash free for storage, insurance and running costs.
Having pre-approval in place lets you move quickly, which matters in a market where well-priced boats, especially used ones, get snapped up fast.
If you run a business, you may be able to structure marine finance as business lending, with chattel mortgage treatment for vessels used to earn income. Confirm the tax position with your accountant.
Match the lender to the vessel first. Age caps, vessel types and private sale rules vary more in marine lending than almost any other asset class, so the shortlist of suitable lenders is genuinely different for a new jet ski versus a fifteen-year-old cruiser.
Consider a marine survey for older or higher-value vessels. Lenders don't require one, but a survey can still protect you on condition and value.
Then compare structures. Term length, balloon size and whether the trailer and equipment are bundled all move the total cost.
One enquiry compares marine lenders across the lender panel. Your broker shortlists lenders that accept your vessel type and purchase channel, then handles valuation requirements, title checks and settlement.
Have your licence, proof of income and the vessel details ready, including the HIN for used boats. For private sales, the seller is paid directly at settlement once ownership is verified.
Get pre-approved before boat shows and private inspections, and buy the boat that fits lender policy rather than discovering the policy afterwards.
Bundle the trailer and fitted equipment into the purchase where you can. Financing them with the vessel usually beats paying for them on short-term credit.
For older vessels, ask your broker which lenders assess on condition rather than age alone, and consider a survey even when it is optional.
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$1,014
per month
Weekly
$234
Total repayment
$60,829
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteBoat Finance Runs
on Its Own Rules.
Vessel age, construction, and whether it is trailerable or moored all shape who will lend and on what terms. Your broker places the application where the vessel fits, rather than where the form fits.
Written by a licensed broker for Australian borrowers.
 2 guidesMarine financeBoats, jet skis and marine refinancing, with the checks that come with buying on water.Explore marine finance
 Boat Finance 101: The Complete GuideHow boat loans work in Australia, including what lenders assess, the documents you need and how the application runs from enquiry to settlement.
 Buying a Boat Privately: Finance, HIN and Encumbrance ChecksPrivate boat sales can be the best value on the water, but the finance runs differently. HIN checks, PPSR encumbrance searches, settlement.Browse the full guide library
Who we help
Not sure where to start? We walk you through every option and help you borrow the right amount.
Moving from a smaller vessel to something larger? We find the right structure for your trade-up.
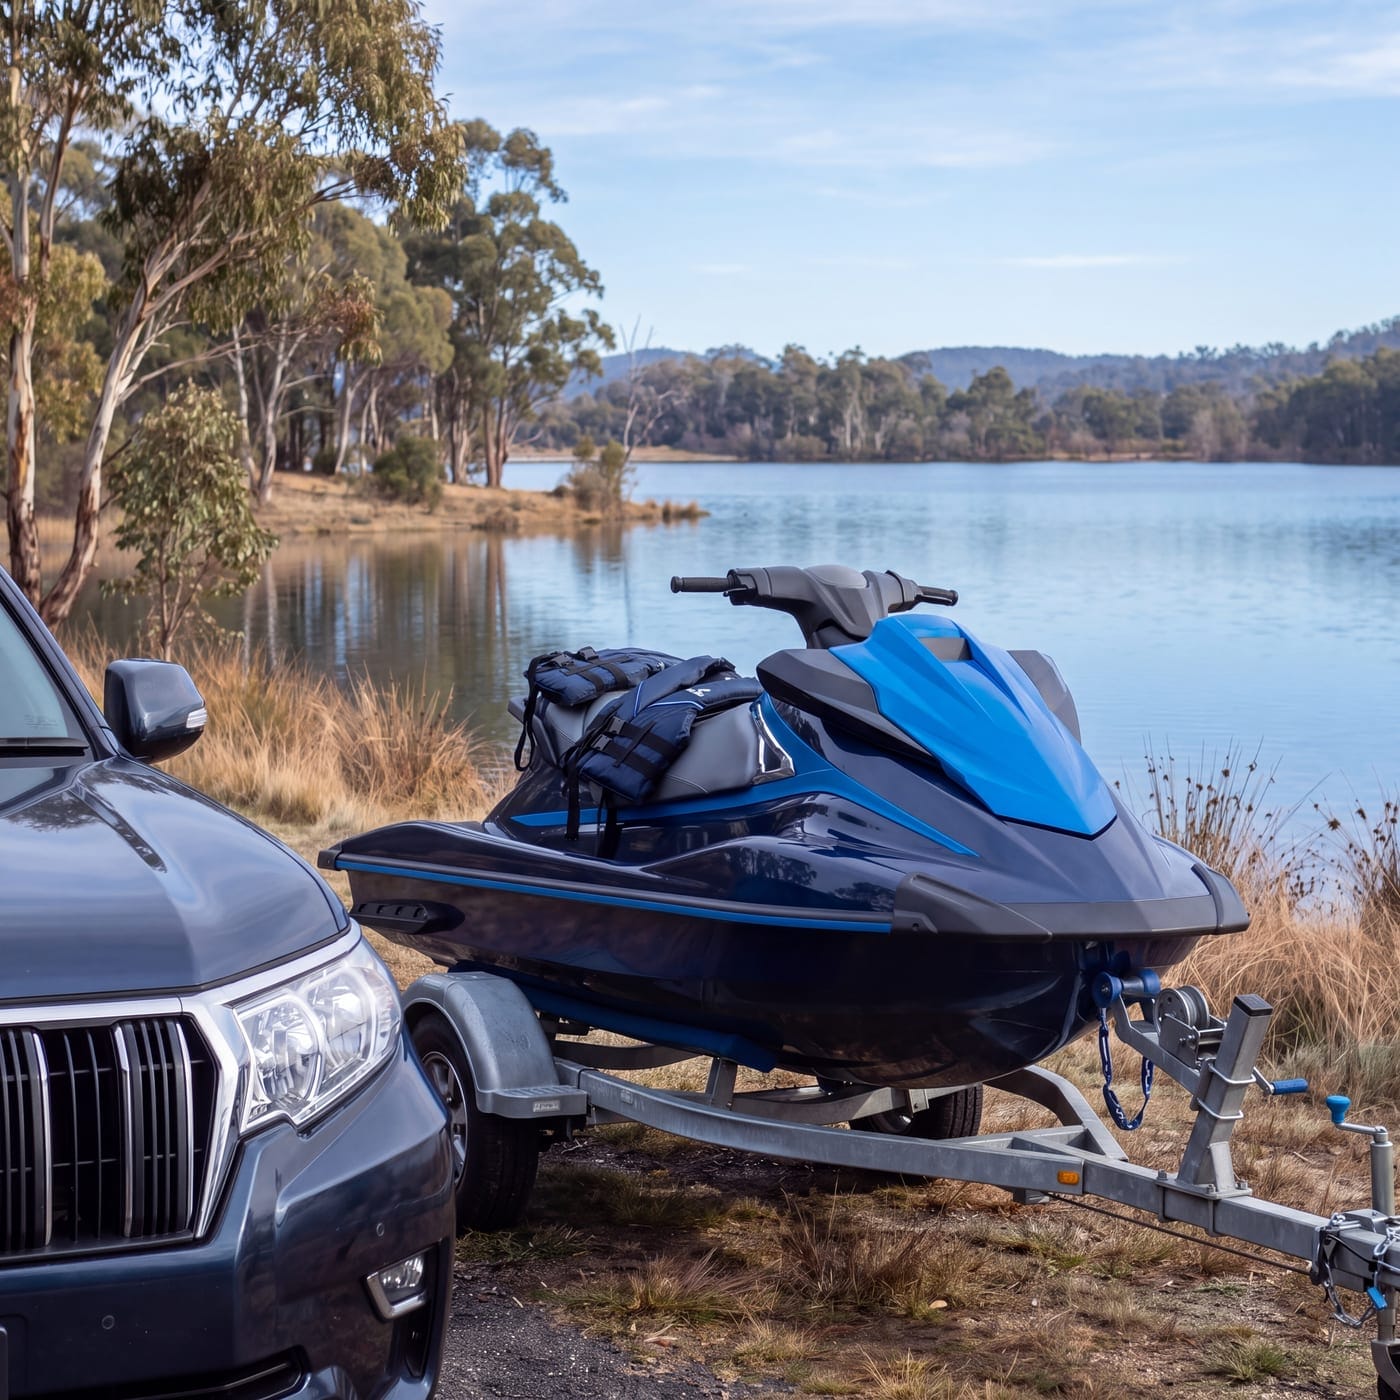
PWC finance for new and used personal watercraft, secured and unsecured.
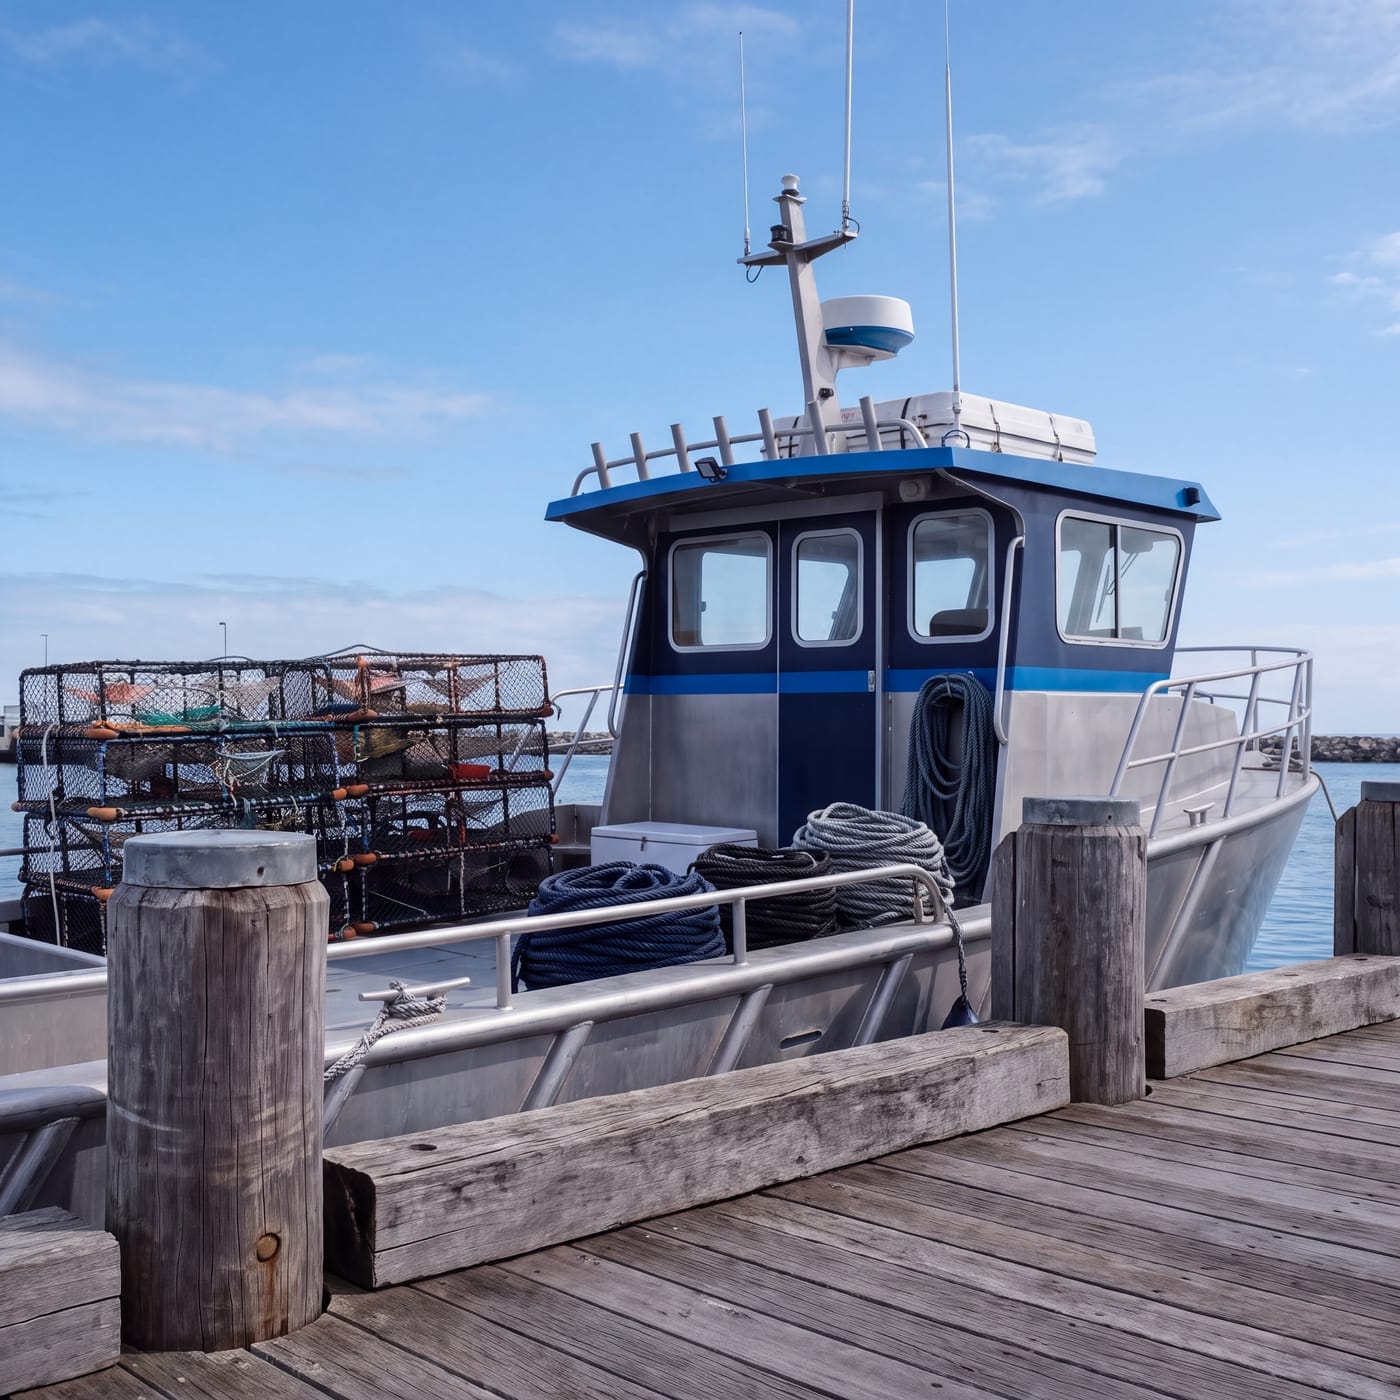
Using the vessel commercially? We explore chattel mortgage and other business finance structures.
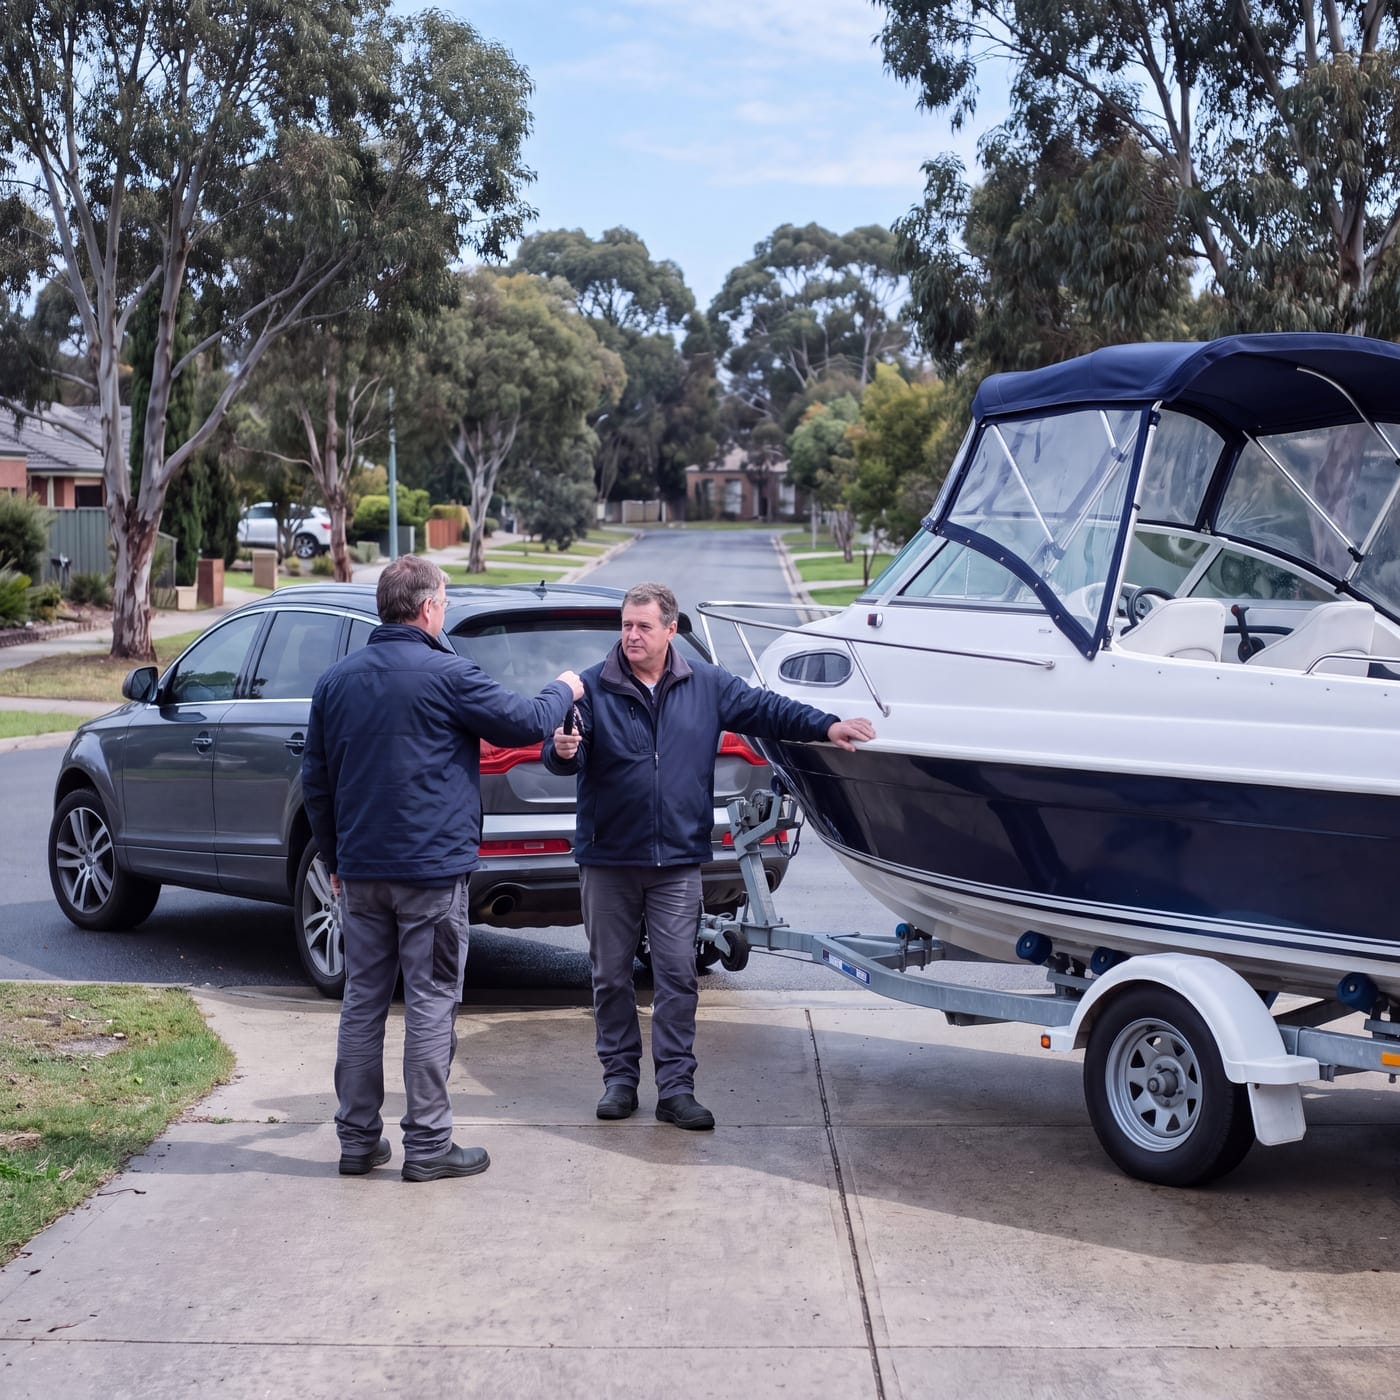
Buying from a private seller? We arrange finance and guide you through the transfer process.
Australian citizen or permanent resident
Aged 18 or older
Stable income (PAYG, self-employed or business)
Acceptable credit history (some lenders consider adverse credit)
Vessel meets lender age and condition requirements