1 of 3
Secured Caravan Loan
- Security required
- Yes, the caravan
- Typical terms
- 1 to 7 years
- Balloon available
- Yes
- Best suited to
- Towed vans and campers
- Turnaround
- Possible same day

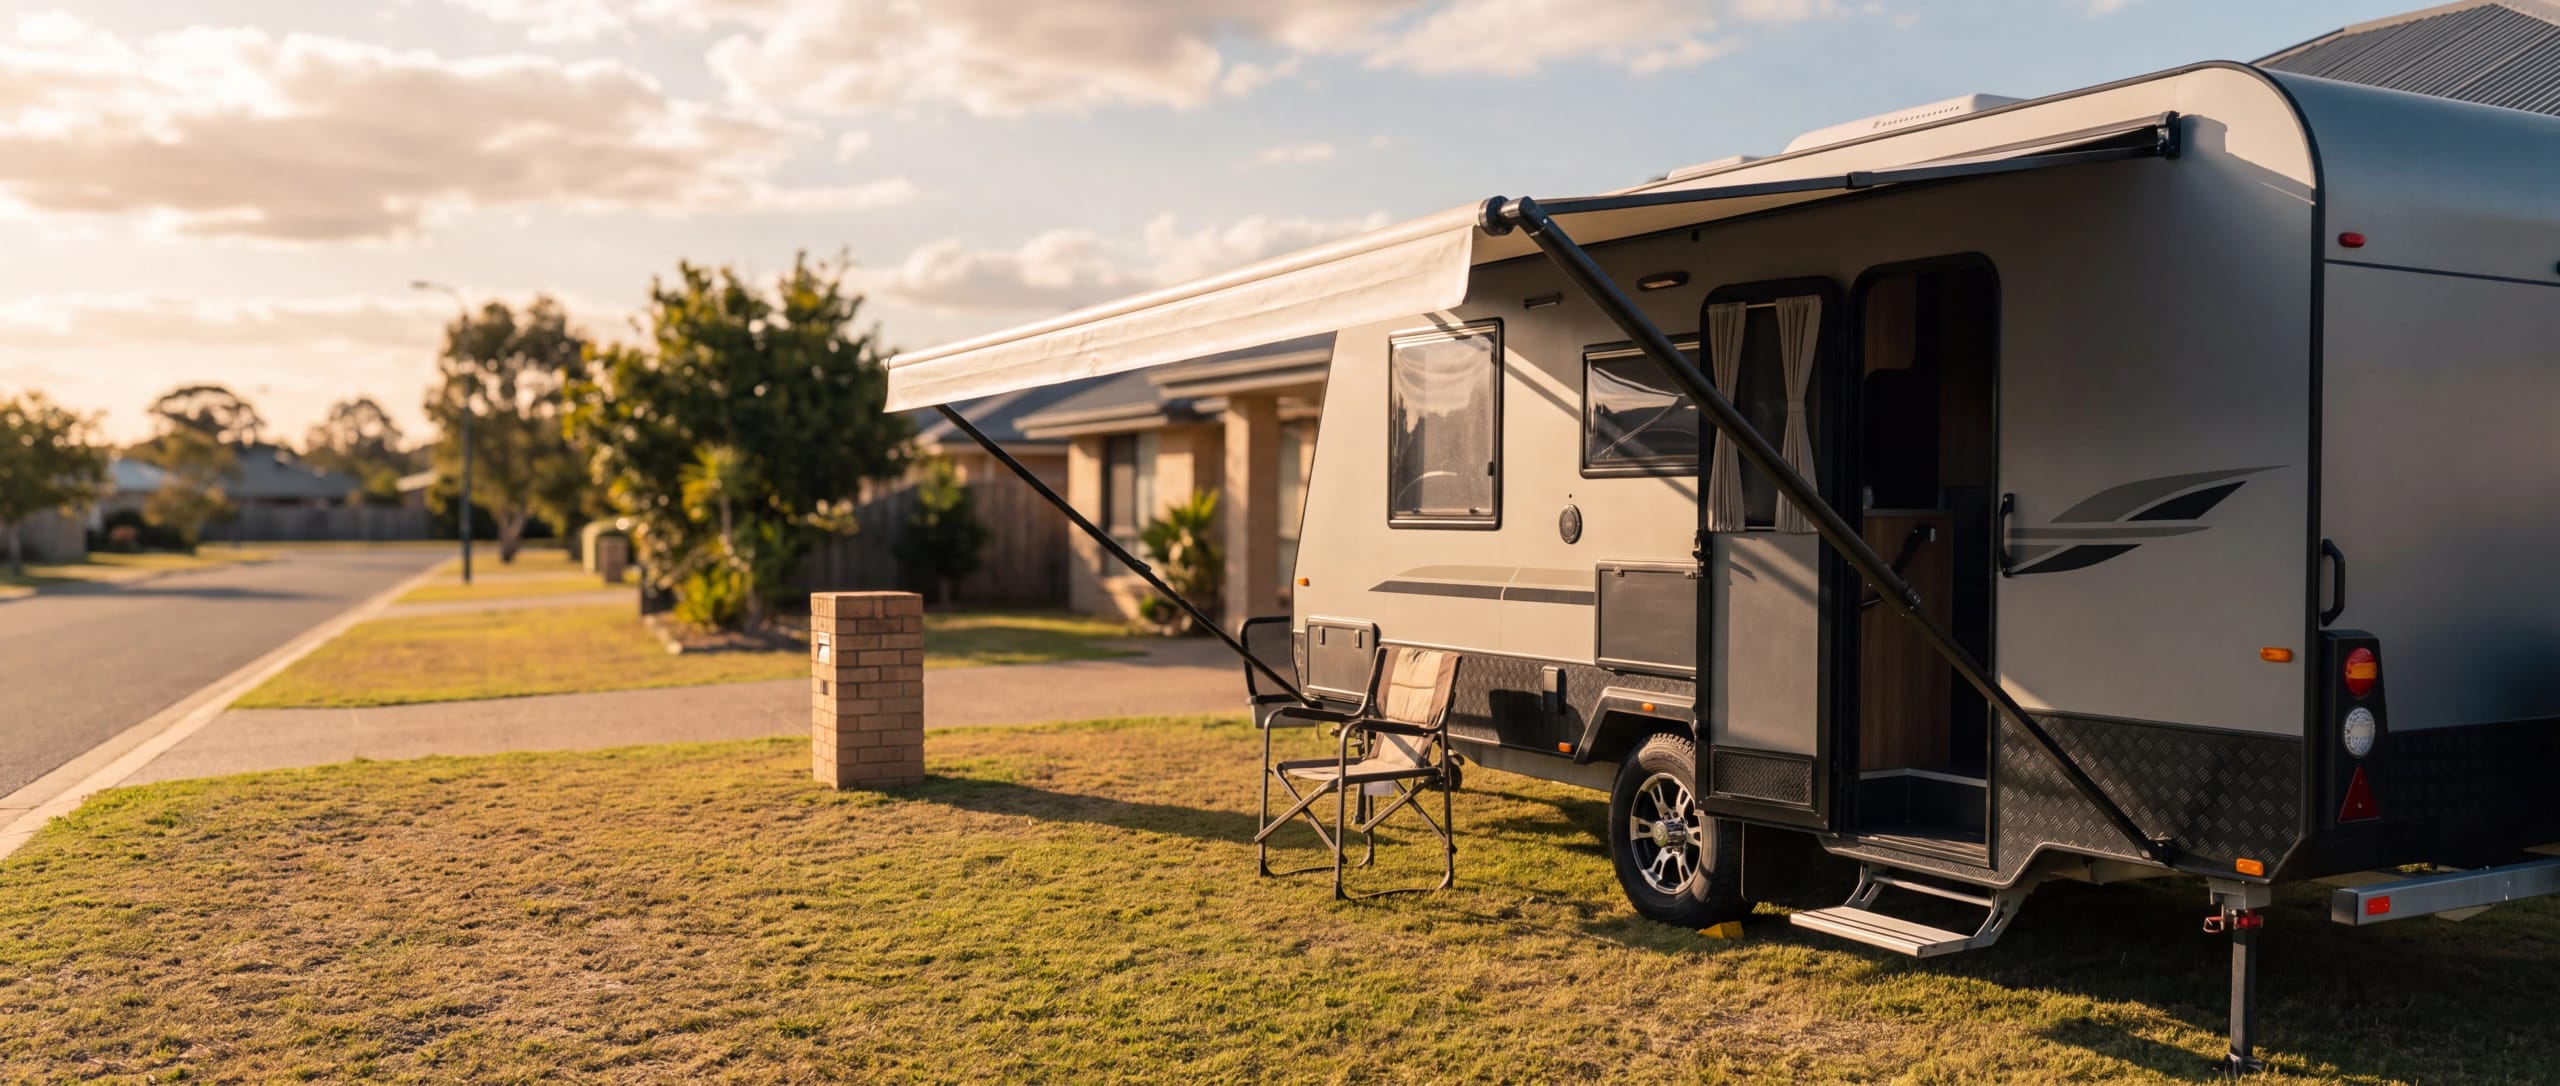
Caravan finance is a secured loan for a new or used caravan, camper trailer or motorhome, paid off over one to seven years. No deposit options are available, and you can buy from a dealer or a private seller. The van itself is the security, which helps keep the rate sharp.
New off-road tourer, used family van, camper trailer or a motorhome. Morella Finance compares caravan loan rates across Australia's banks and specialist lenders so you get the deal that suits your trip.
Caravan loans from 7.59% p.a. Comparison rate 8.43% p.a.*
Motorhome and campervan finance · No-obligation quote · Same day pre-approval possible
BROKER vs BANK
Bank vs broker,
side by side
Caravan lending has more restrictions than car finance
Age limits and asset type restrictions vary significantly across lenders. A broker matches you to the right lender before applying.
Private sale caravans need specialist lenders
Many banks won't finance private sale caravans. We access lenders who do without adding unnecessary complexity.
Older caravans require the right panel
Standard lenders often cap caravan age at 10-15 years. Specialist lenders on our panel go much further.
One application, the whole panel compared
No repeated applications, no repeated credit checks. We assess your profile once and compare the full panel.
Every caravan type is financed
Pop-top, full caravan, camper trailer, motorhome, campervan and fifth-wheel are all in scope, which is not true of every lender's asset list.
Off-road and touring vans are in scope
Off-road and touring caravans, including purpose-built Australian-made models, are accepted by lenders on our panel.
The process
Asset type, purchase price, new or used, dealer or private sale.
Your broker compares lenders to find the loan that suits your profile.
Rate, term and fee comparisons side by side.
Checks, paperwork and payment to the seller managed for you.
Some of the lenders on our panel
Compare caravan loan types side by side
The most common structures for vans and motorhomes, and where each fits.
Secured Caravan Loan
Motorhome Finance
Low-Doc (ABN)
Step 1 of 5
A caravan loan works much like a secured car loan. The van is the security, and terms usually run from one to seven years. The loan can cover a dealer purchase or a private sale. An unsecured loan, such as a personal loan, can suit an older van outside a lender's rules, but a secured loan generally costs less.
Lenders have their own rules for caravans on age, type and value. So the lender that gave you a car loan may not be the right one for your van.
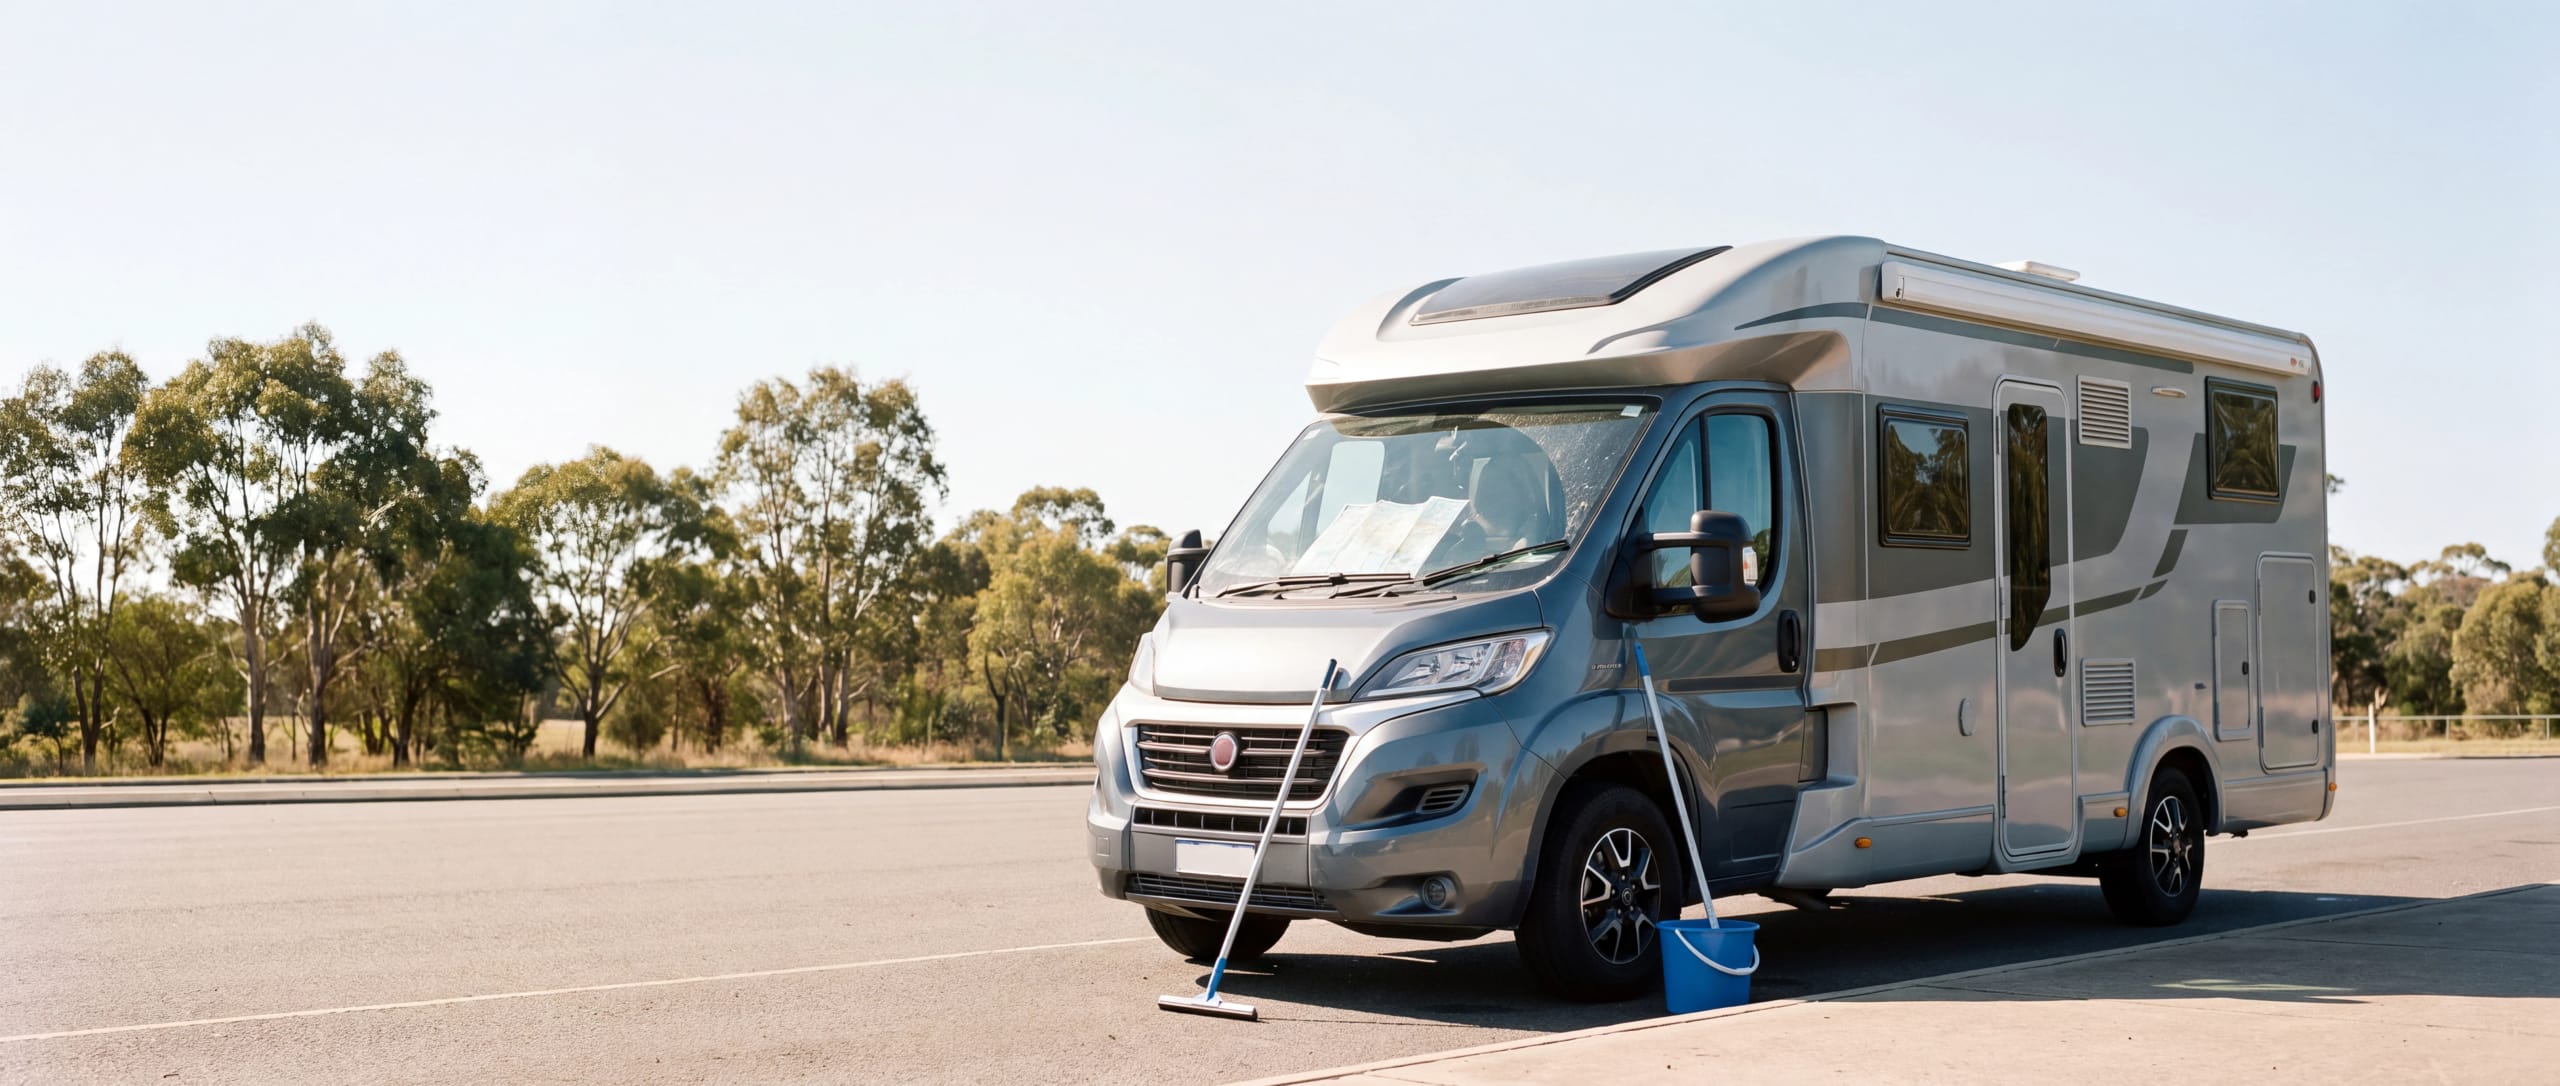
Motorised RVs are assessed differently. A towed caravan or camper trailer is one category. A motorhome or campervan with its own engine and registration is another. Some lenders finance both, some only one, and maximum ages differ between them.
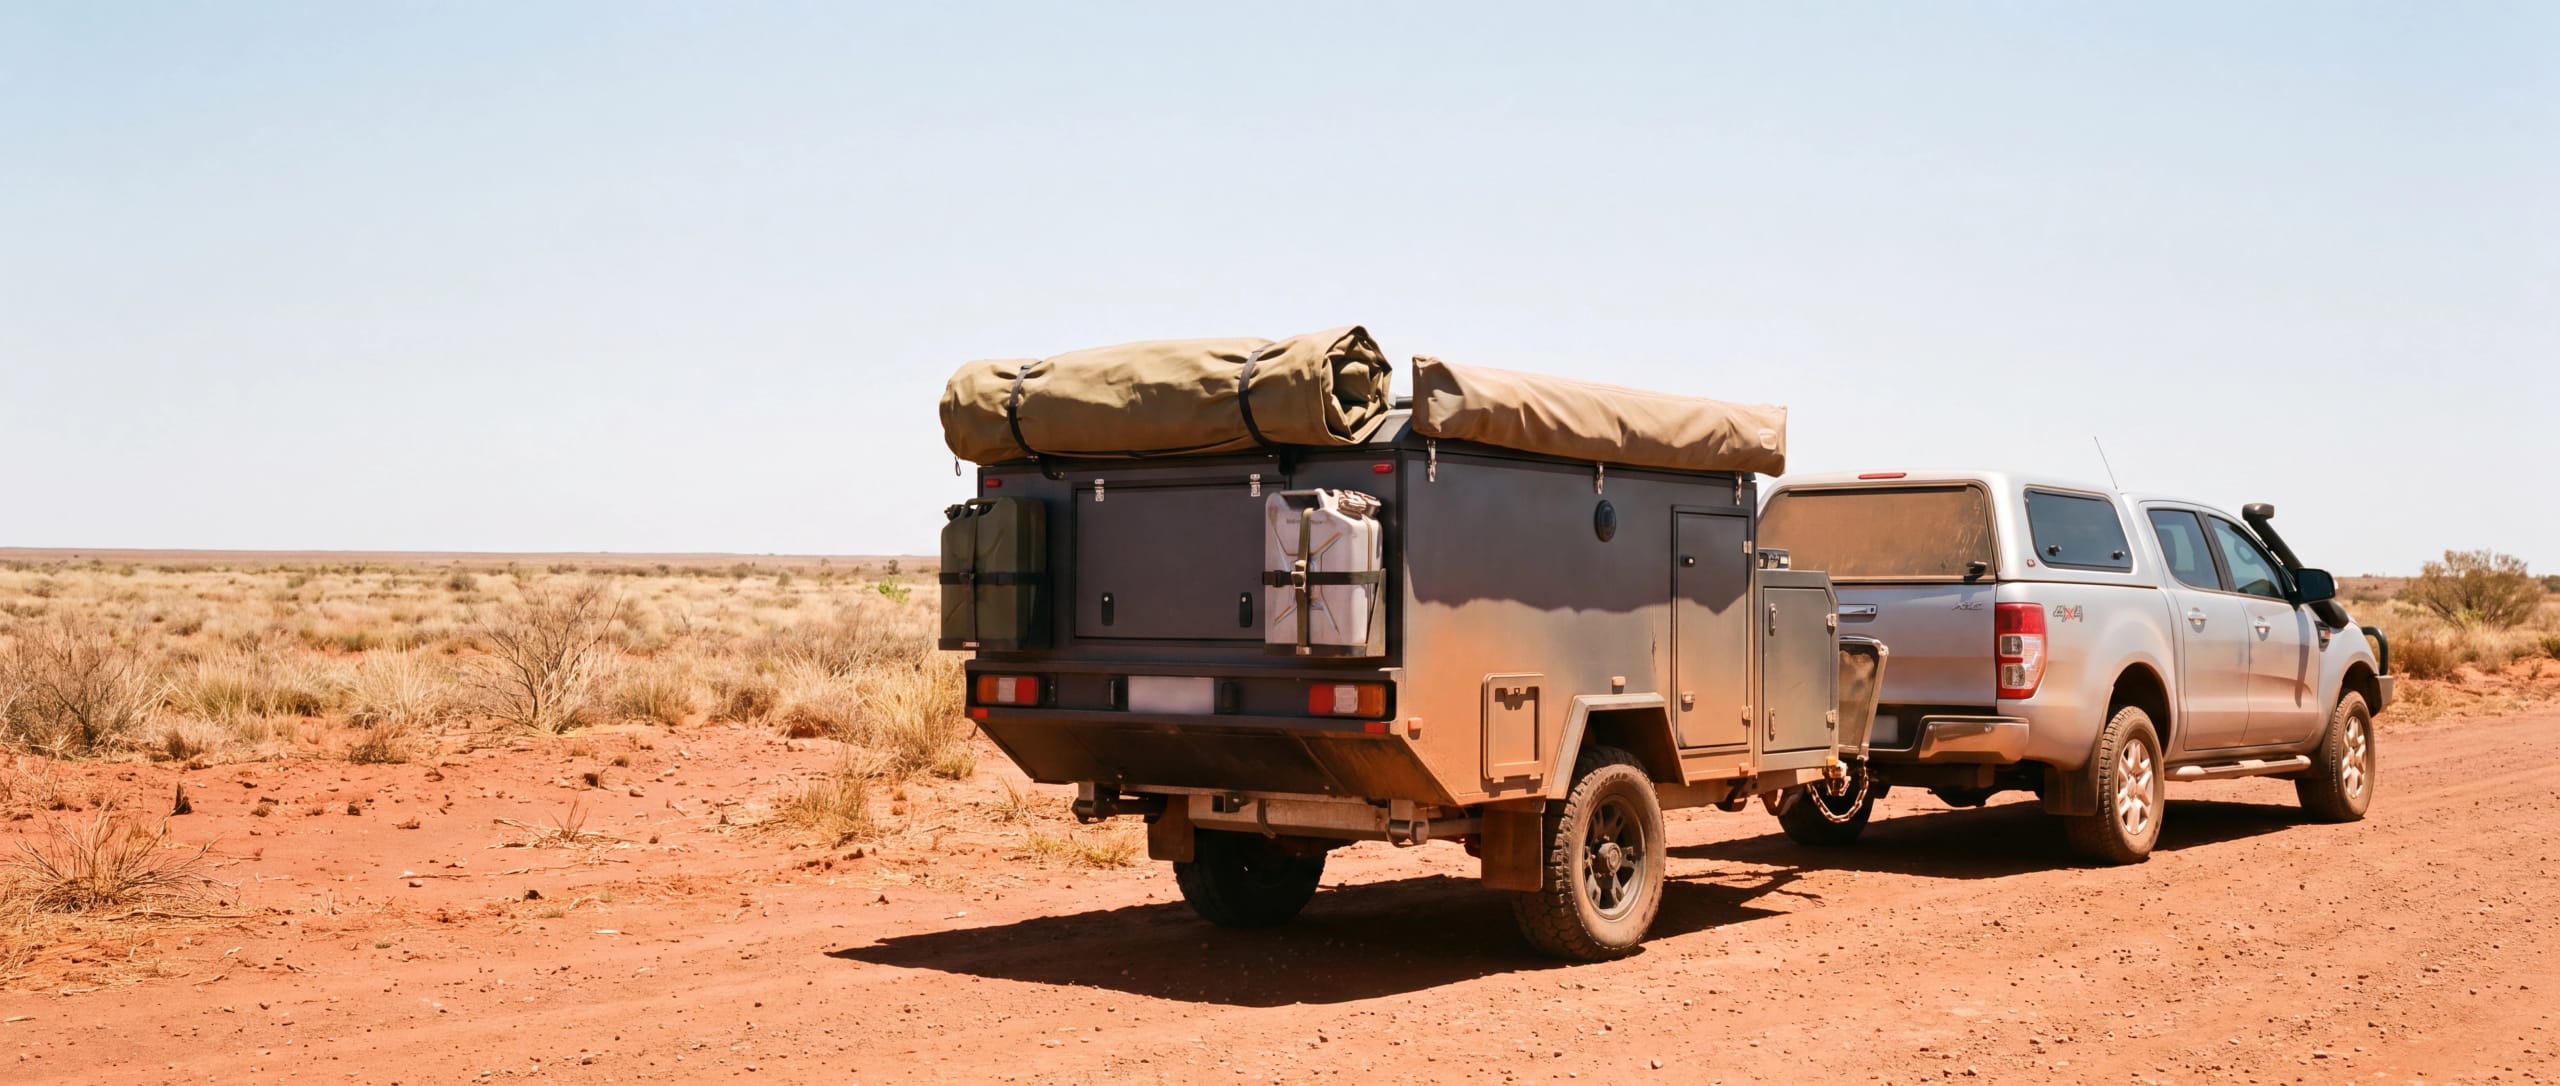
Camper trailers are financed the same way as caravans, with the trailer held as security. See camper trailer finance for new, used and off-road campers.
Deposit expectations are generally modest. Many lenders will finance the full purchase price for well-qualified borrowers, including on-road costs and accessories fitted at purchase.
A caravan is a lifestyle purchase that most families use for a decade or more. Financing spreads that cost across the years you use it rather than draining savings in one hit, and keeps cash free for the trips themselves.
Pre-approval also protects you in a market where good vans sell fast. With finance confirmed, you can commit to a dealer, a show special or a private seller with the confidence of a cash buyer.
Caravans hold value comparatively well when maintained, which supports balloon structures for buyers who want lower repayments and plan to upgrade within a few years.
Start with how you will buy. Dealer purchases are straightforward for nearly every lender. Private sales need a lender that supports direct seller payment and ownership verification, which is a smaller list.
Next, think about the van's age at the end of the loan, not the start. Many lenders set a maximum age at the end of the term. A ten-year-old van on a seven-year loan is outside the rules at some lenders and fine at others.
Then weigh the term and any balloon against your plans. A longer term lowers your loan repayments but adds to the total interest you pay over the term. If you will keep the van for years, focus on the total cost. If you upgrade often, a balloon can keep repayments lower.
One enquiry compares lenders across our panel. Your broker shortlists the ones whose rules fit your van, how you are buying it and your income. We then manage the loan application through to settlement.
When assessing your application, the lender looks at your income, living expenses, existing debts, credit history and credit score, as well as the van itself. It wants to see that the repayments fit comfortably in your budget.
Have your licence, proof of income and the van's details ready. For a private sale your broker also gathers the seller's bank details and proof of ownership. The seller is paid directly at settlement, so both sides are protected.
Get pre-approved before caravan shows and before inspecting private sales. Sellers take offers seriously when the money is ready.
Include accessories at purchase where possible. Annexes, solar and towing equipment fitted at sale can often be financed with the van rather than arranged separately later.
Check the lender's age limit before falling for an older van. Compare the total amount repayable across offers, not just the repayment.
Look at the comparison rate as well as the interest rate. It folds most fees and charges into one figure, which makes it a fairer way to weigh one loan product against another.
Already paying off a van? If your credit or income has improved since you bought it, a caravan refinance may get you a better rate or a term that suits you better.
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$773
per month
Weekly
$178
Total repayment
$46,399
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quote6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
A caravan's age
matters most.
Caravans come with lending restrictions a car never faces, including age limits and private sale rules. Your broker matches the caravan you actually want to the lenders whose policy accepts it.
Written by a licensed broker for Australian borrowers.
 Caravan Finance for Self-Employed and ABN HoldersRunning your own show should not stand between you and a caravan. What lenders actually ask of ABN holders, and how to place the application well.Australia's caravans are getting heavierAustralia's caravans are getting heavier. Vans over 2,500kg tare rose 32% in two years. See caravan weight by state from BITRE's 2026 registration data.New vs Used Caravan Finance: Which Is Right for You?New and used caravans borrow the same way but are assessed quite differently. How lender appetite, age rules and structure shift between the two.How Caravan Loan Pre-Approval WorksSorting your caravan budget before you shop changes how dealers and private sellers treat you. How pre-approval works and how to use it well.See all 8 caravan finance guides
Who we help
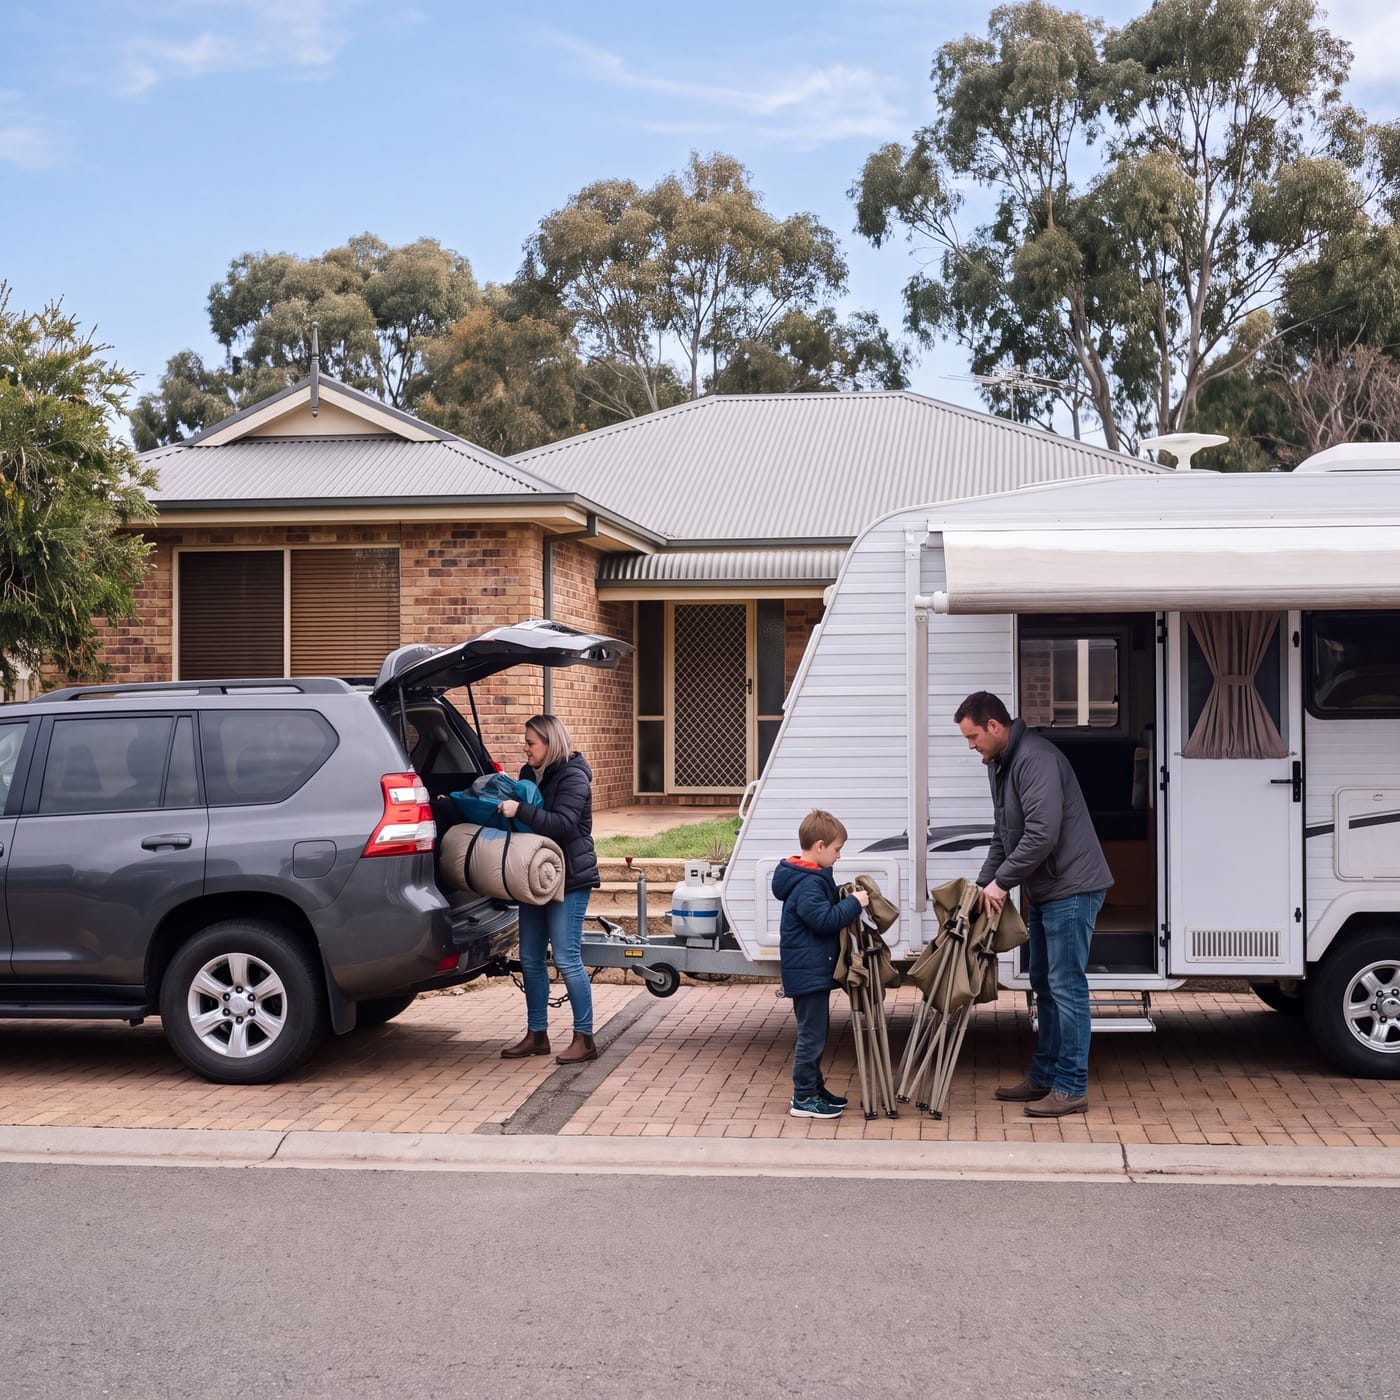
Upgrading to a bigger van for longer family trips.
Retiring and planning an extended lap of Australia.
Regular short trips, need reliable finance at the right rate.
First caravan, first loan, wanting clear advice.
Trading up from a basic van to something more capable.
18 years or older
Australian citizen, permanent resident, or eligible visa holder
Regular income: PAYG, self-employed, ABN or Centrelink considered
Valid driver's licence
Asset assessed on type, age and condition. Older caravans considered by specialist lenders.
Rates on our panel start from 7.59% p.a. (comparison rate 8.43% p.a.)*. The rate you're offered depends on your credit history, the caravan's age and the loan term. Tell us what you're buying and we'll compare lenders to find you the best rate we can. The comparison rate example and warning are at the bottom of this page.
Yes. Specialist lenders on our panel finance private sales. The process includes a PPSR check and direct payment to the seller. Your broker manages every step.
Standard lenders often cap caravan age at 10-15 years. Specialist lenders on our panel will go much further for the right applicant. The limit depends on the caravan's condition and your credit profile.
Yes, though some lenders distinguish between towed caravans and self-propelled motorhomes. Your broker identifies which lenders best suit your specific asset type.
Yes. A camper trailer is financed much like a caravan, with the trailer usually held as security. New, used and off-road campers are all considered, bought from a dealer or a private seller, and we arrange camper trailer loans from $10,000.
Some lenders may ask about your towing capacity as part of their assessment. Your broker advises on what documentation may be required for the specific lender you proceed with.
Yes. Self-employed buyers can apply with their tax returns and business financials. If you hold an ABN, low-doc options through specialist lenders may also suit, with lighter paperwork than most buyers expect.
Most lenders offer caravan loan terms from 1 to 7 years, which is the maximum term available across the panel. Longer terms reduce monthly repayments but increase total interest paid over the life of the loan. Your broker compares all available terms for your loan amount.
Not always. Many lenders finance the full purchase price for well-qualified borrowers, including on-road costs and accessories fitted at purchase. A deposit lowers the repayment but is not a requirement across the panel.
Often, yes. Specialist lenders on our panel assess past defaults and credit events on their merits, looking at what happened, how long ago and your conduct since. We match your file to lenders whose policy genuinely fits before anything is lodged.
Yes, balloon structures are widely available on caravan loans. They suit buyers who upgrade every few years, with the balloon sized against the van's realistic value at the end of the term.
Sooner than most people expect. Some lenders will refinance a loan that has been active for just 1 month, while others prefer a longer history. We weigh any exit costs against the saving before recommending a switch.
We call you within one business day, generally within the hour, to walk you through your options in everyday terms, with no obligation. Pre-approval for most standard caravan applications lands the same day, so you can commit to a van with confidence.