1 of 3
Secured Bike Loan
- Security required
- Yes, the bike
- Typical terms
- 1 to 7 years
- Balloon available
- Yes
- Best suited to
- Most road and adventure bikes
- Turnaround
- Possible same day

New sportsbike, used cruiser or a classic you've always wanted. Morella Finance compares motorbike loan rates across Australia's banks and specialist lenders so you get the right deal.
All bike types · No-obligation quote · Fast turnaround
BROKER vs BANK
Motorbike finance: bank vs broker
Lender restrictions on bikes vary enormously
Age limits, import restrictions and displacement caps vary across the panel. A broker knows which lenders suit which bikes before applying.
We search the panel, not one product
Your bank offers one rate on one product. We compare the panel in one application.
Private sale and import finance available
Many banks decline private sale motorbike finance. We access specialist lenders who don't.
One application, one soft credit check
No repeated enquiries across multiple lenders. One assessment, full panel compared.
The process
Make, model, year, price and whether it's new, used or a private sale.
Your broker compares rate and structure across the market.
See rate, term and fee comparisons before you decide.
Checks, paperwork and payment to the seller managed for you.
Some of the lenders on our panel
Bike policy is stricter and more varied than car policy. These are the things that decide the lender panel before your income is looked at.
Compare motorbike loan types side by side
The three most common structures we arrange for riders, and where each fits.
Secured Bike Loan
Unsecured Bike Loan
Low-Doc (ABN)
Step 1 of 5
Motorbike loans are usually secured against the bike, with terms from one to seven years. Road bikes, cruisers, adventure bikes, off-road machines and scooters are all financeable, though each lender draws its own lines on engine size, bike type and age.
Secured and unsecured structures both exist. Secured loans typically cost less because the lender holds the bike as collateral, while unsecured loans suit bikes that fall outside security criteria, such as older or heavily modified machines.
Private sales are common in the bike market and entirely financeable. The lender pays the seller directly once ownership is verified, protecting both sides of the deal.
Financing gets you on the road without waiting to save the full price, and keeps cash aside for the gear, insurance and servicing that riding actually costs.
Pre-approval puts you in a stronger position. Good bikes at fair prices move fast between private sellers, and a buyer with settlement ready beats one who still has to arrange the money.
Riders who use a bike for work, from couriers to mobile trades, can finance under a commercial structure with different tax treatment. Your accountant can confirm what applies.
Decide secured versus unsecured first. If the bike qualifies as security, a secured loan usually costs less. If it does not, an unsecured loan keeps the purchase possible without forcing you onto a different bike.
Check age and type rules early. Some lenders cap bike age at the end of the term, and a few decline particular categories entirely. Knowing the shortlist before you shop stops you falling for a bike no lender will finance.
Compare on total repayable, and keep the term aligned to how long you realistically keep bikes between upgrades.
One enquiry compares motorbike lenders across the lender panel without repeated credit checks. Your broker matches your bike and your profile to the right lenders and manages everything through to settlement.
You will need your licence, proof of income and the bike's details, including the VIN for used purchases. Pre-approval typically lands the same day for standard applications.
Get pre-approved before you start messaging sellers. It turns inspections into negotiations.
Factor gear and accessories into your budget rather than the loan where possible, and keep the loan matched to the bike itself.
If you are self-employed, ask about low-doc options upfront so the paperwork matches your income evidence from the start rather than being reworked mid-application.
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$366
per month
Weekly
$85
Total repayment
$17,577
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteNot every lender
finances bikes.
Policy varies more on bikes than on almost any other asset. Capacity, age, imports and modifications all change who will lend. Your broker knows which lenders say yes to your bike before an application goes anywhere.
Written by a licensed broker for Australian riders.
Who we help
Getting licensed, needs finance for their first road bike.
Moving from a learner bike to a full-sized machine.
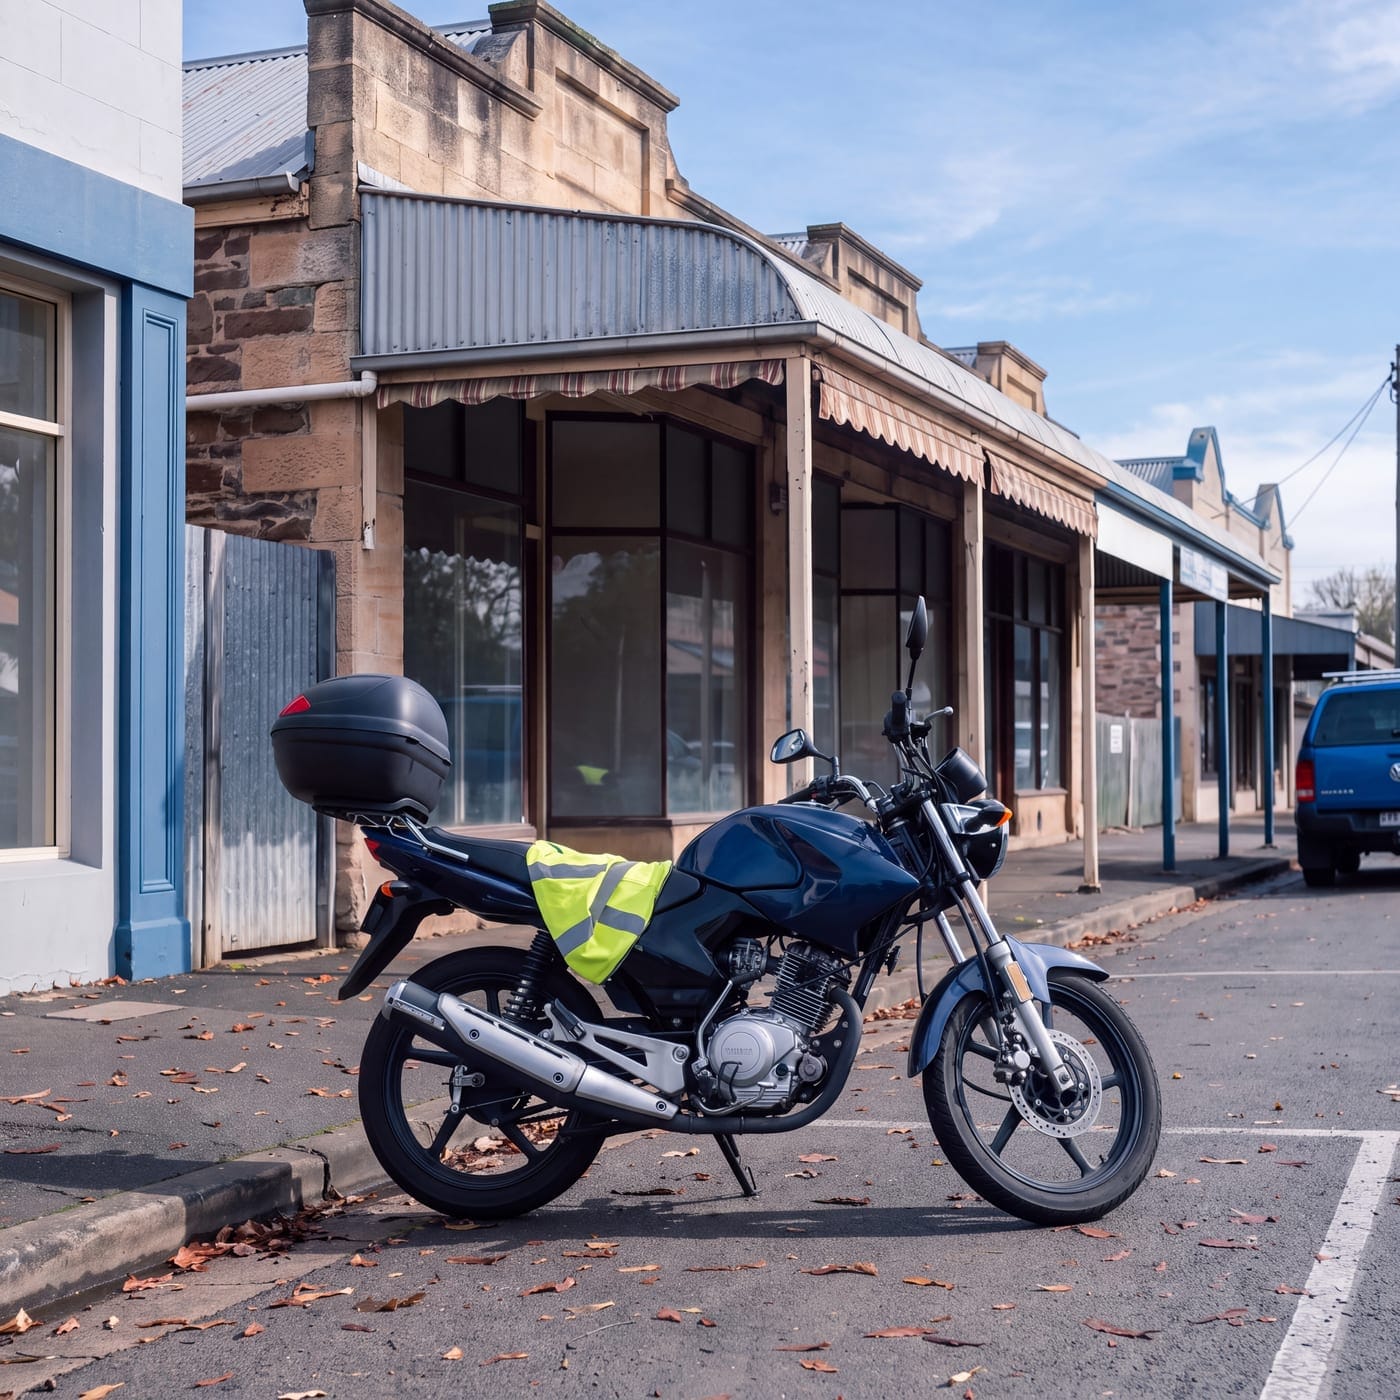
Using the bike for work. ABN or low-doc options.
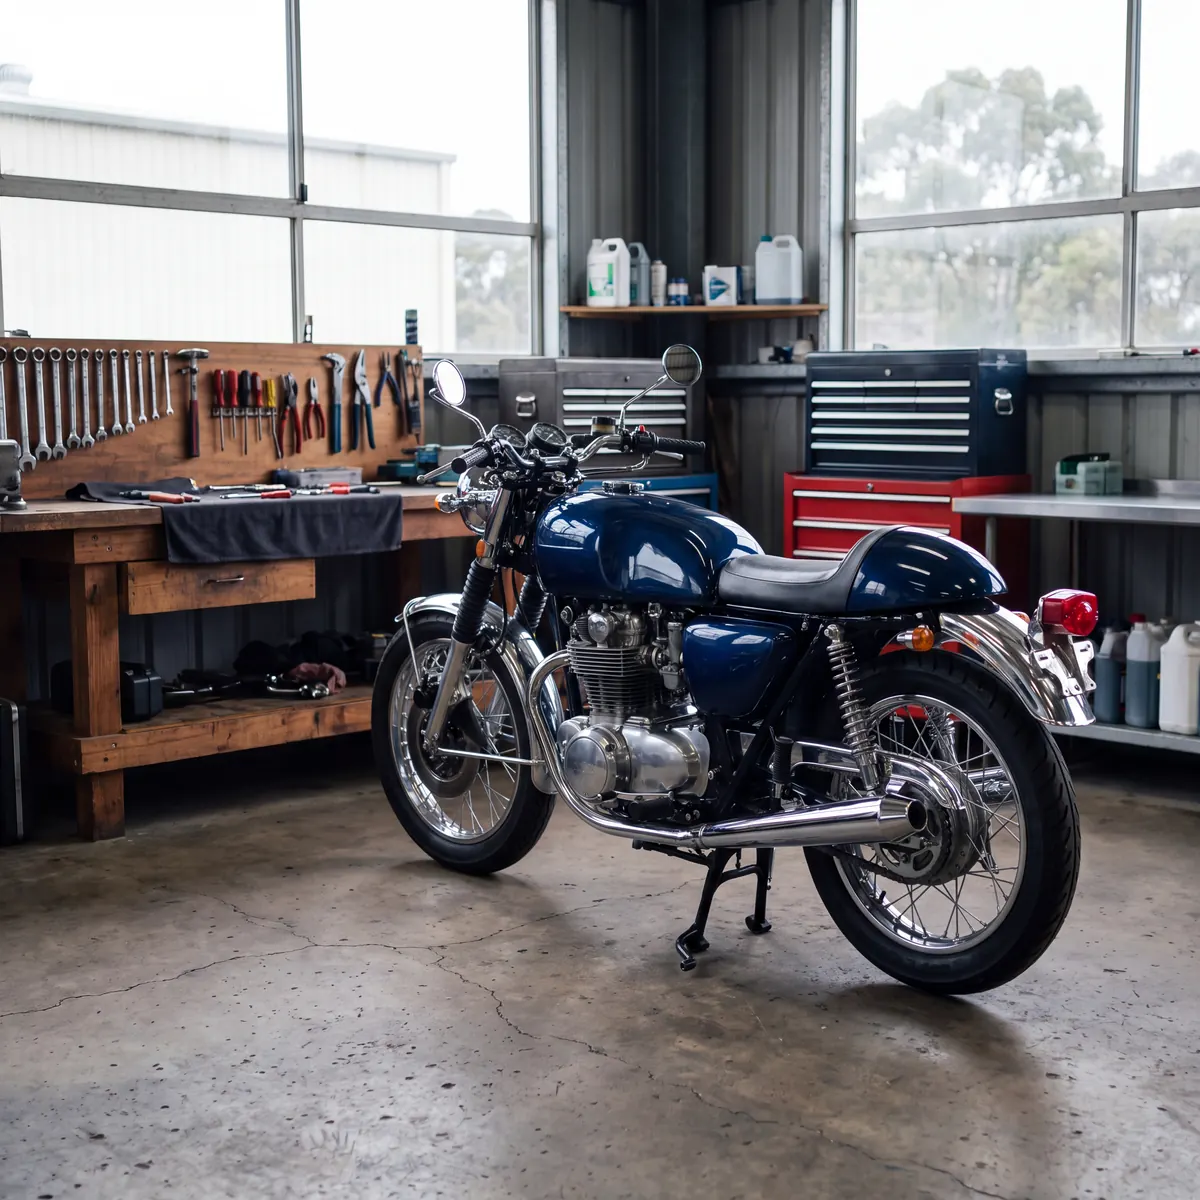
Funding a classic or vintage motorcycle purchase.
Existing bike loan with a rate that's too high.
18 years or older with a valid motorcycle licence
Australian citizen, permanent resident, or eligible visa holder
Regular income: PAYG, self-employed, ABN or Centrelink considered
Vehicle assessed on its merits, with age, import status and condition considered
Credit history reviewed holistically