
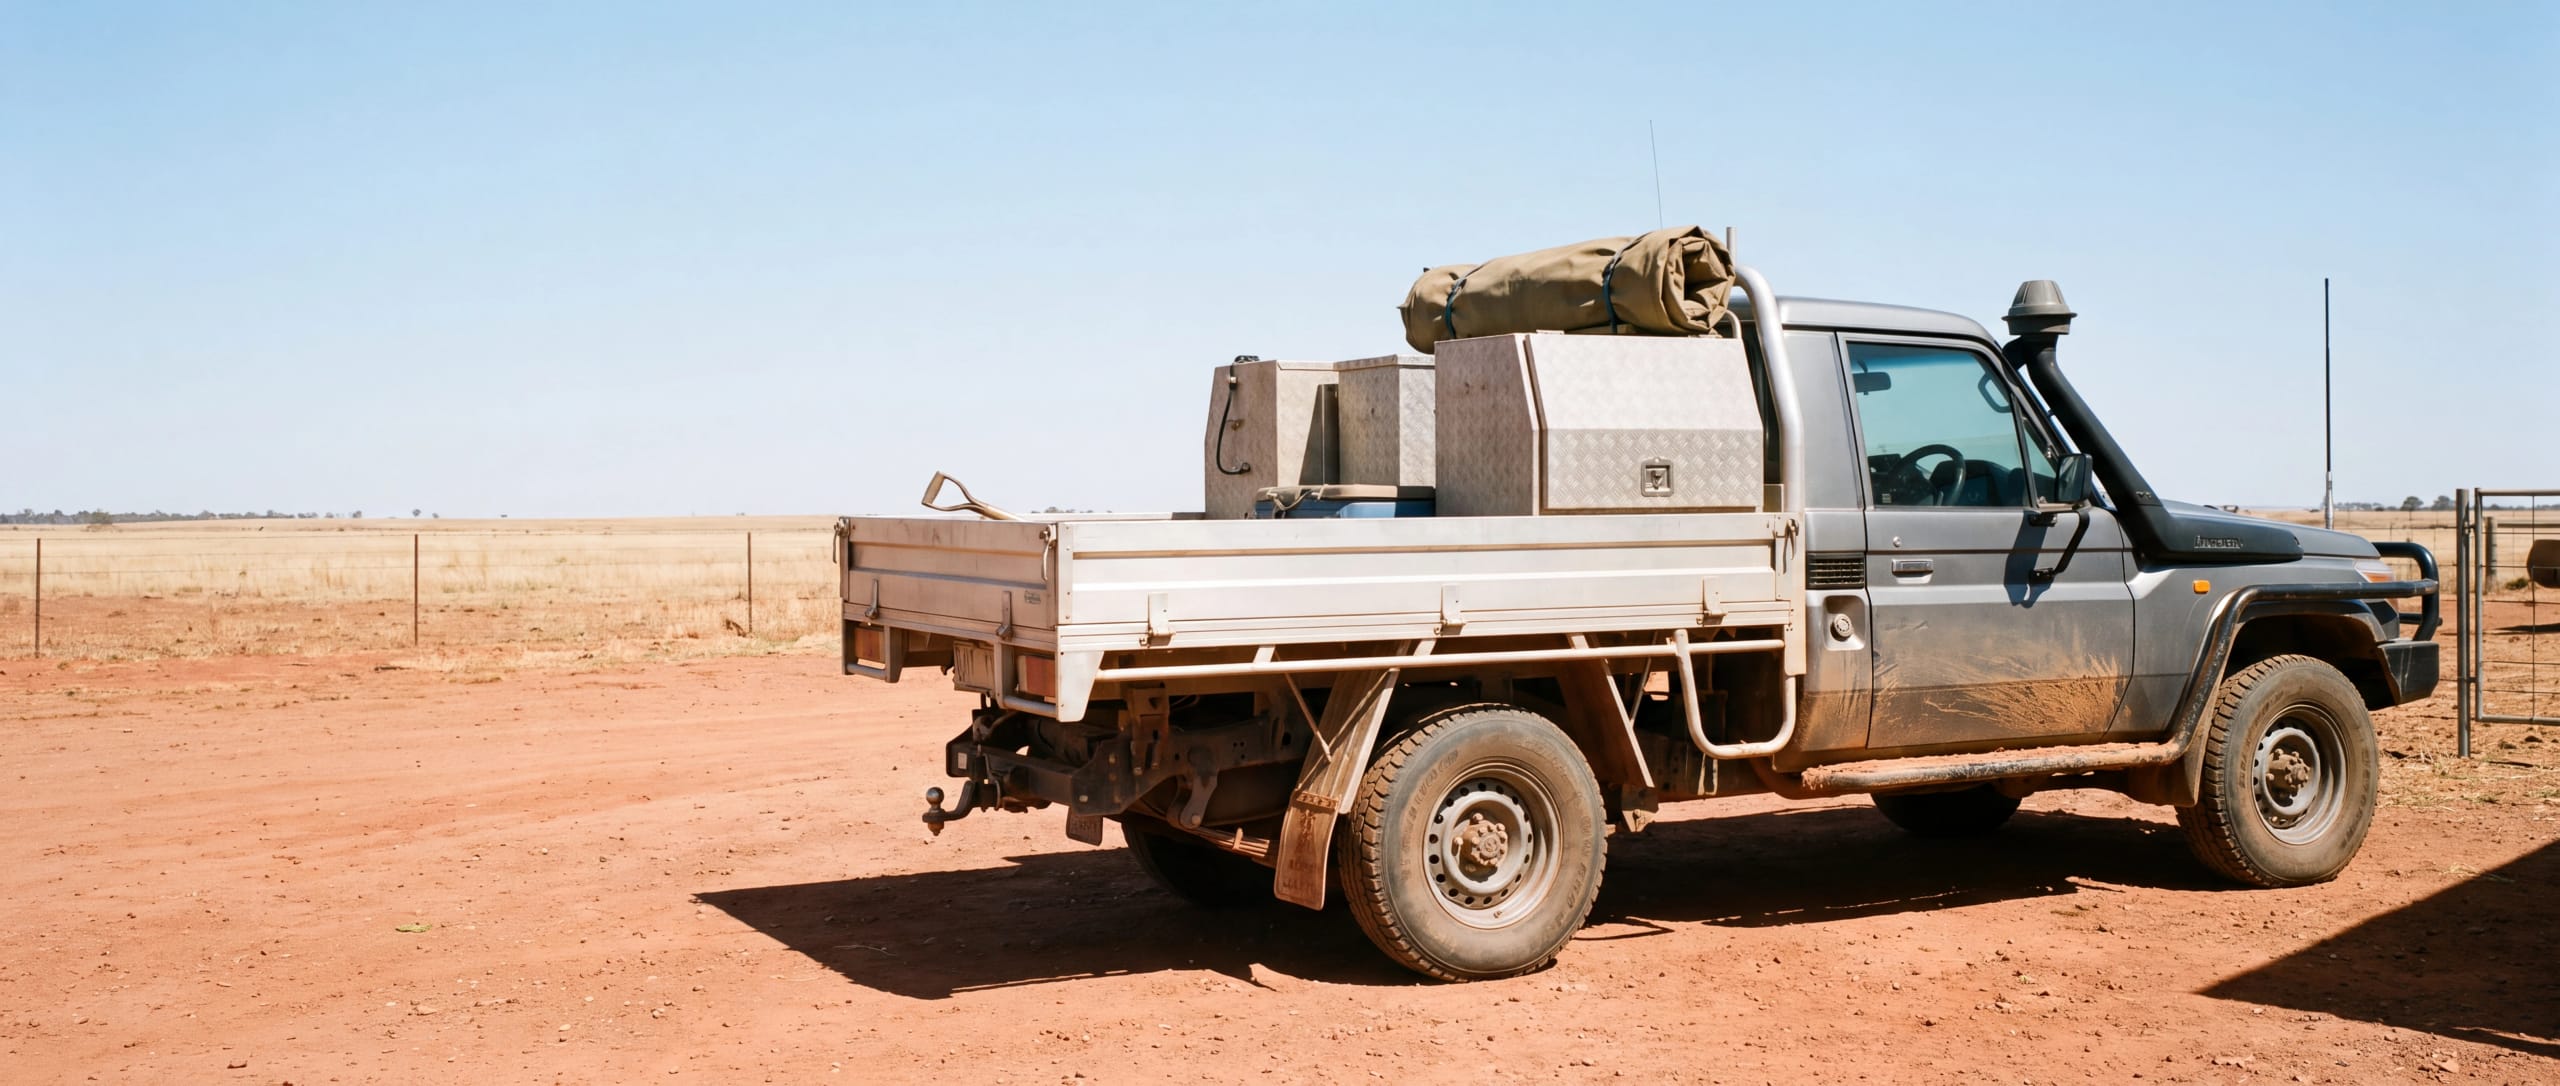
Low-Doc Car Finance Without Payslips
Self-employed without neat payslips? Most low-doc lenders on our panel just need your driver's licence. The table below shows what's typically required.
Specialist self-employed lenders · ABN welcome · No-obligation assessment · Fast decisions
LOW-DOC vs STANDARD
How low-doc car finance differs from standard lending.
Standard vs low-doc car finance
Standard lenders require full documentation most self-employed borrowers can't provide
Two years of tax returns, company financials and a PAYG summary. For many self-employed Australians, this simply doesn't reflect their current income. Low-doc lenders use alternative evidence.
Low-doc lenders keep the paperwork minimal
A driver's licence usually covers it. The only common addition is a few months of banking, and only with some lenders, only when the ABN is under 6 months old.
Pre-approval can move quickly
Because specialist lenders assess a shorter document set, straightforward low-doc applications can turn around faster than standard finance. Some reach pre-approval the same day.
Business structure matters for tax outcomes
Low-doc finance is commercial lending for business-use vehicles. A chattel mortgage may allow GST and depreciation treatment that suits your business. We help you identify the right structure and recommend confirming tax outcomes with your accountant.
The process
Low-Doc Car Finance. In 4 Steps.
Tell us about your business
ABN details, how long you've been trading and what vehicle you are looking to buy.
We identify suitable lenders
Your broker matches your documentation type to the right lenders on the specialist panel.
Submit your documentation
Usually just your driver's licence. Some lenders may also ask for a few months of banking if your ABN is under 6 months old.
Pre-approval and settlement
Receive your pre-approval and drive away with fully handled paperwork.
| Document | What it tells the lender | When it is asked for |
|---|---|---|
| Driver's licence (front and back) | Confirms your identity | Required in almost all cases. For most applicants, this is the only document needed |
| Active ABN | That the business is genuinely trading, or has continuity in the industry | Required. Some lenders will finance a brand new ABN where you've moved straight from PAYG employment in the same trade, for example an electrician going out on their own |
| Recent bank statements (for new ABNs) | Extra confidence where trading history is limited | Requested by some lenders when the ABN has been registered for less than 6 months |
Low-doc car finance without the guesswork.
Step 1 of 5
What low-doc car finance actually means
Low-doc car finance is built for self-employed Australians and ABN holders who don't have the payslips and PAYG summaries a standard application asks for. It's commercial lending, usually structured for business-use vehicles, assessed on your ABN and identity rather than a full set of financials.
For most applicants that means a driver's licence, front and back, and nothing more. Some lenders will also want a few months of banking, but generally only where the ABN has been registered for less than 6 months.
Why low-doc finance exists for self-employed buyers
Standard lending assumes an employee's income, a steady payslip and a tidy PAYG summary. Self-employed income rarely behaves that way. It comes in unevenly, gets ploughed back into the business, and often looks smaller on paper than it really is once legitimate deductions come off the top.
None of that means you cannot afford the loan. It means a standard assessment gives the wrong picture of your income, and that is what low-doc lending exists to solve.
Working out if low-doc is the right path for you
It's aimed at sole traders, contractors and small business owners with an active ABN buying a vehicle for business use. A brand new ABN doesn't automatically rule you out either. Some lenders will finance one where you've come straight from PAYG employment in the same trade, an electrician going out on their own being the classic example.
If your tax returns are current, plenty of mainstream lenders will assess you the standard way, and that option stays open. Low-doc is there for when your paperwork has not caught up with your income, not the only route available to self-employed buyers.
Applying for low-doc car finance
We match how long your ABN has been registered, and what you can document, against our lender panel, then place you with the lenders whose low-doc policy actually fits.
There's less to check on a low-doc file, so it can move quickly, sometimes reaching pre-approval the same day. Once you're approved, we take the paperwork from there.
Getting a low-doc application right
Have your driver's licence ready to go, and if your ABN is under 6 months old, keep a few months of recent banking handy in case a lender asks for it.
If the car is for business use, talk through the right structure, a chattel mortgage for example, and check the tax treatment with your accountant before you commit. Avoid applying to several lenders yourself, because each attempt lodges a credit enquiry where one well-matched application does the job.
Low-doc car finance at a glance
- Most applicants need nothing more than a driver's licence, front and back
- Banking is only asked for by some lenders when the ABN is under 6 months old
- A brand new ABN can still qualify with continuity from PAYG employment
- How long your ABN has been registered is matched against our lender panel in one go
- Well-matched low-doc applications can move quickly, sometimes the same day
Car Finance That Works for How You Actually Earn
Banks want two payslips and a PAYG summary. Your income doesn't work like that. We have specialist lenders on panel who assess self-employed applications differently.
Get my quoteShort ABN History Considered
Specialist lenders can consider ABNs from as little as 3 months of trading, depending on other factors in your application.
Licence Is Often Enough
Most low-doc lenders on our panel only need a driver's licence, front and back, to get started.
New ABNs Considered
Just gone out on your own? A handful of lenders will back a brand new ABN when you've stayed in the trade you were employed in.
Commercial Structures
Low-doc finance is business lending. We arrange chattel mortgage and other commercial structures for vehicles used in your business.
All Vehicle Types
Car, ute, van, commercial. Low-doc finance is available across all asset types for ABN holders.
Fast Pre-Approval
Know your borrowing power the same day even without full financials.
Car Finance Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$601
per month
Weekly
$139
Total repayment
$36,068
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteMore Car Finance Options
Finance first.
Then the car.
Your broker compares the market against your car, your deposit and your profile, so any offer you are shown becomes something you can measure rather than something you have to accept.
Car Finance Guides
Written by a licensed broker for Australian borrowers.
 9 guidesCar financeNew, used, refinance and private sale car loans for employed and self-employed buyers.Explore car finance
 Balloon Payments Explained: Pros, Cons and How They WorkA balloon payment lowers your monthly car loan repayment by deferring a lump sum to the end of the term. What that costs in interest, and how to plan.
 How Car Loan Pre-Approval Works (and Why It Matters)Pre-approval tells you what you can borrow before you shop, strengthens your negotiating position and takes dealer finance pressure off the table.
 Car Finance for Self-Employed and ABN HoldersNo payslips does not mean no car loan. How self-employed Australians and ABN holders get car finance, what documents lenders accept.
 How Your Credit Score Affects Your Car LoanYour credit file shapes which lenders will approve you and on what terms. How scores work in Australia, what lenders actually look at.See all 9 car finance guides
Who we help
Who We Help with Low-Doc Car Finance
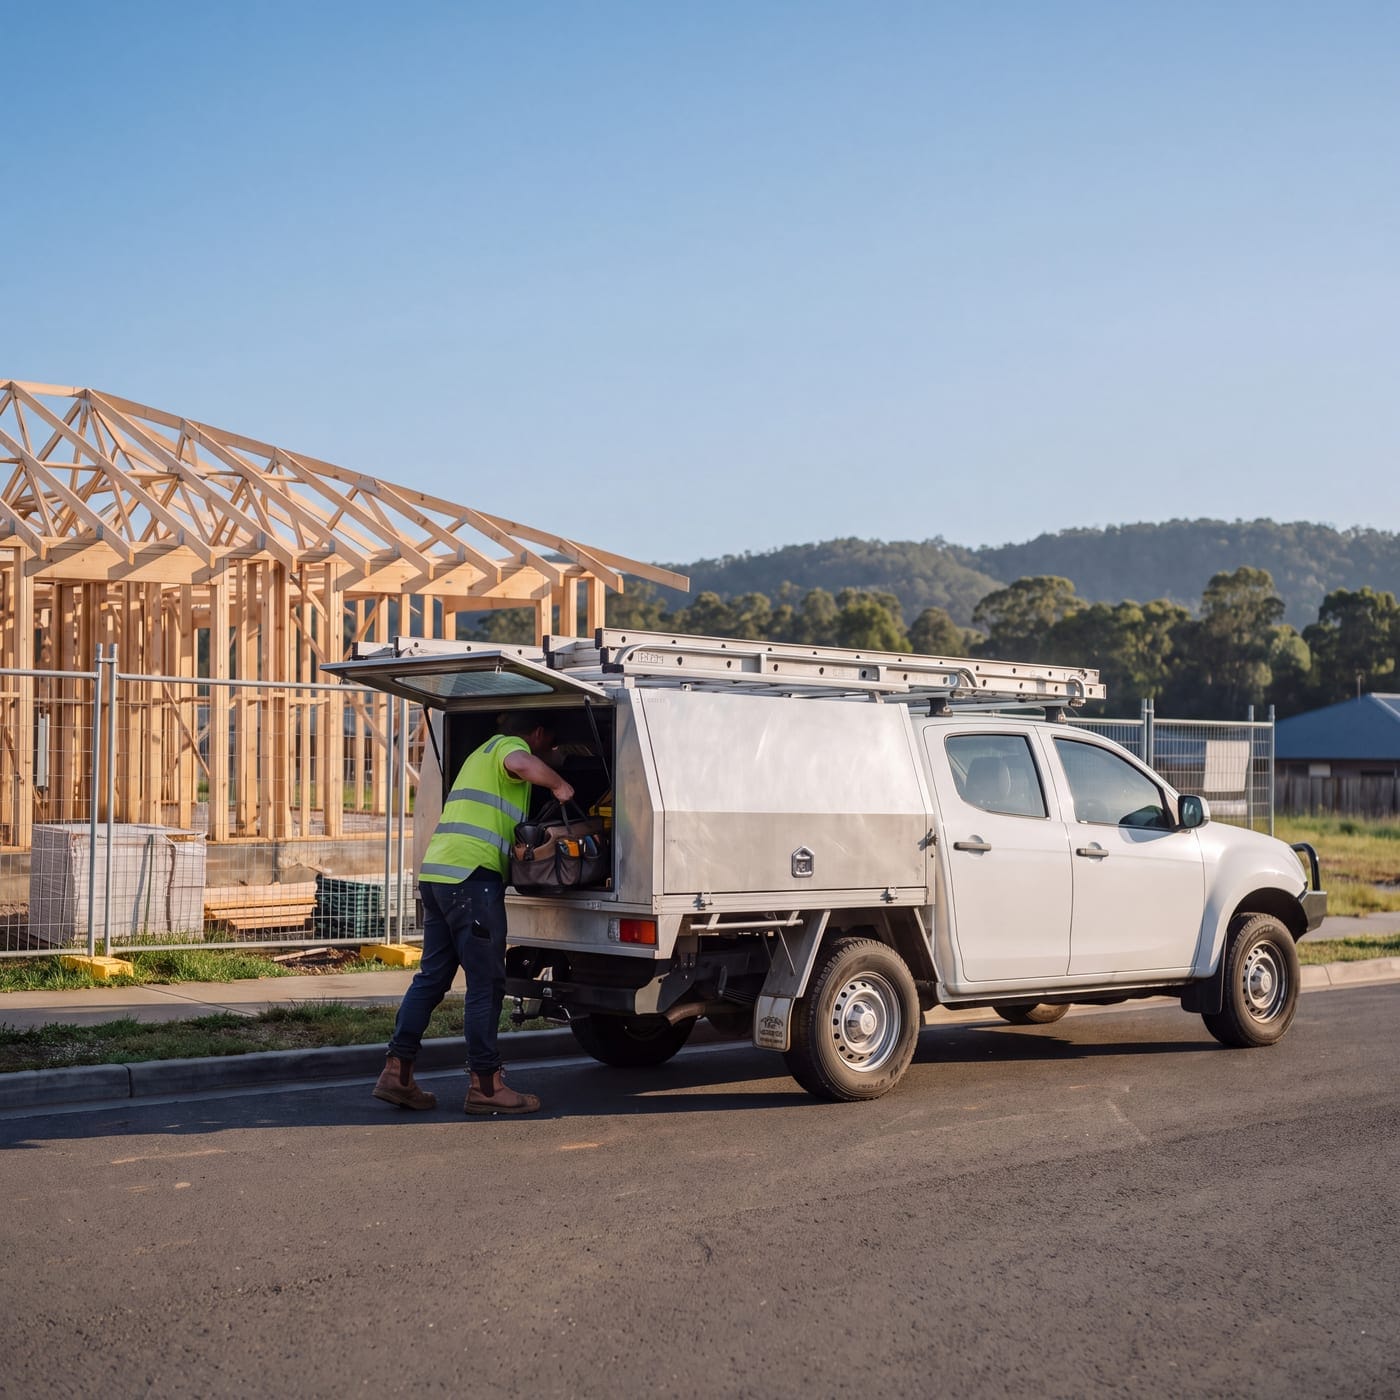
Tradies
Utes and vans with irregular income from multiple clients.
Freelancers
Variable income, strong bank history, no payslips.
Small Business Owners
Established ABN, strong cashflow, limited formal financials.
Contractors
Contract workers not classified as PAYG employees.
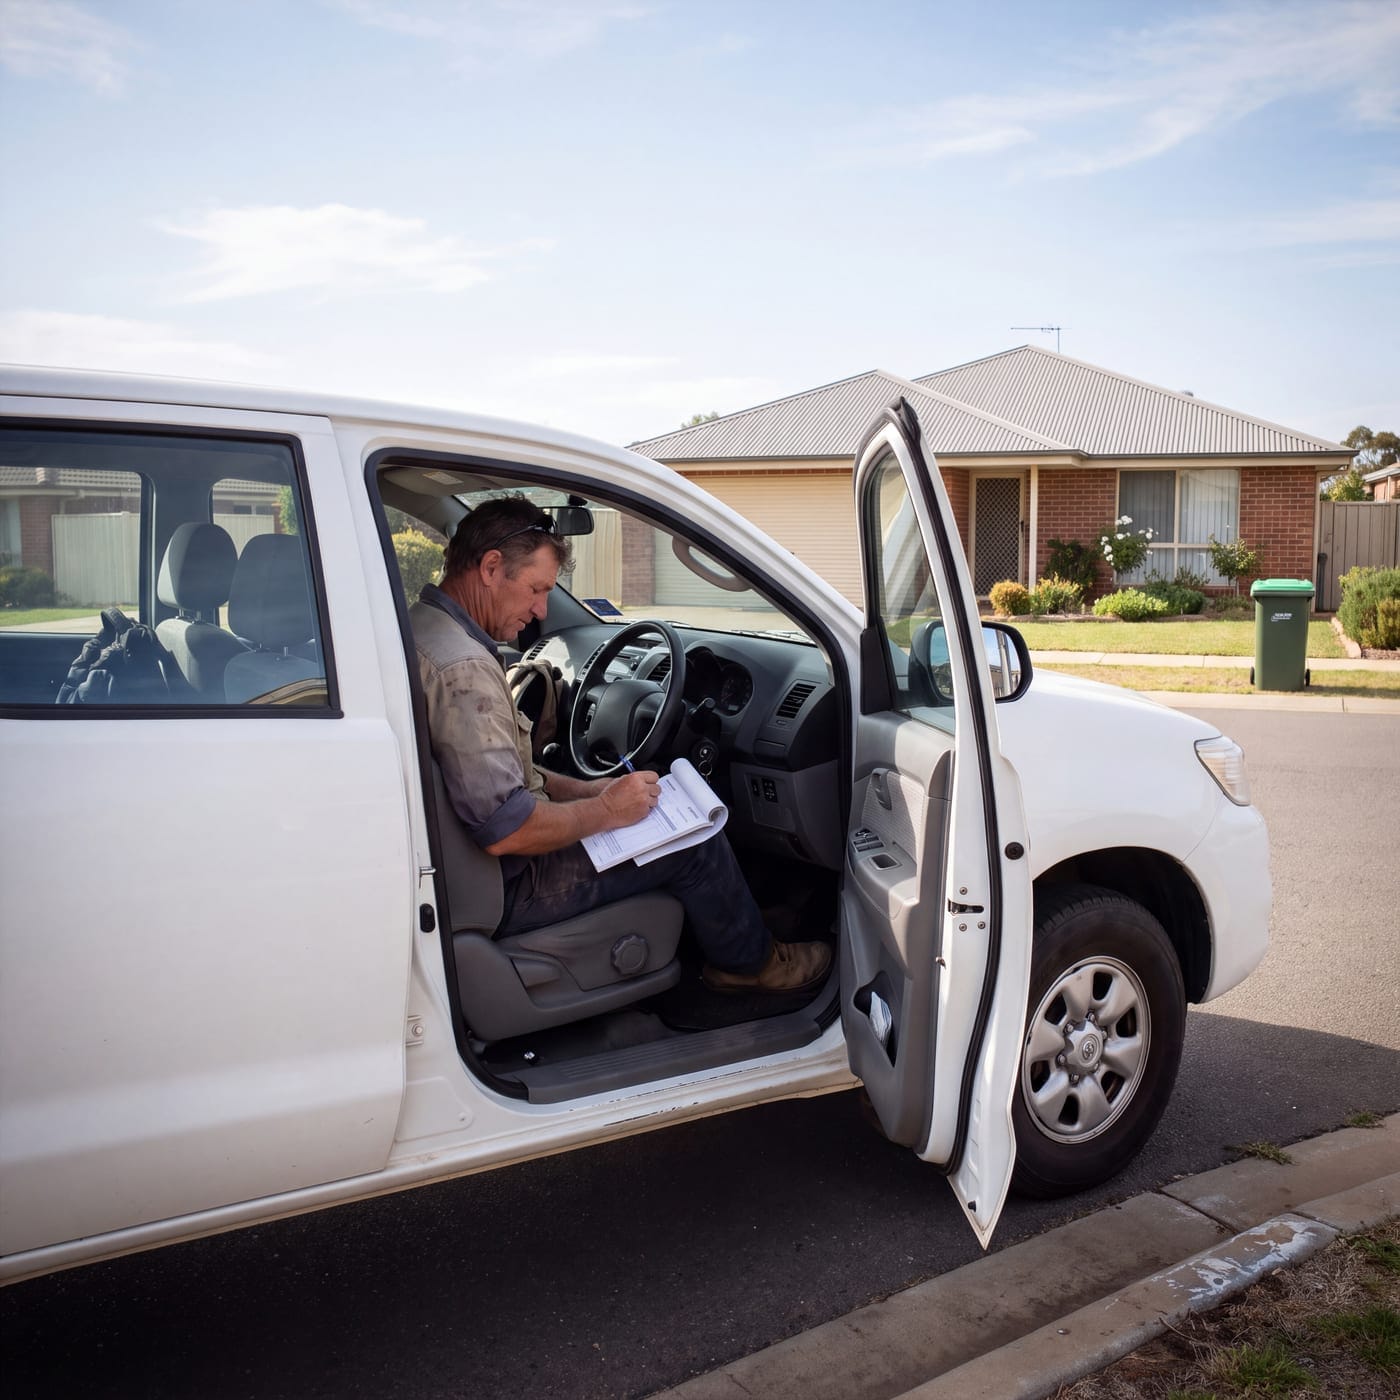
Sole Traders
Individual business operators needing vehicle finance.
18 years or older
Active ABN. A small number of specialist lenders consider ABNs from 3 to 6 months, and a brand new ABN can be considered where your work continues on from previous employment in the same field.
Australian citizen, permanent resident, or eligible visa holder
Driver's licence, front and back. Recent banking may be requested where the ABN is under 6 months old.
Credit history reviewed holistically. ABN trading history and cashflow considered.