1 of 3
New Equipment
- Security required
- Yes, the equipment
- Typical terms
- 1 to 5 years
- Balloon available
- Yes
- Best suited to
- New machinery purchases
- Turnaround
- Possible same day

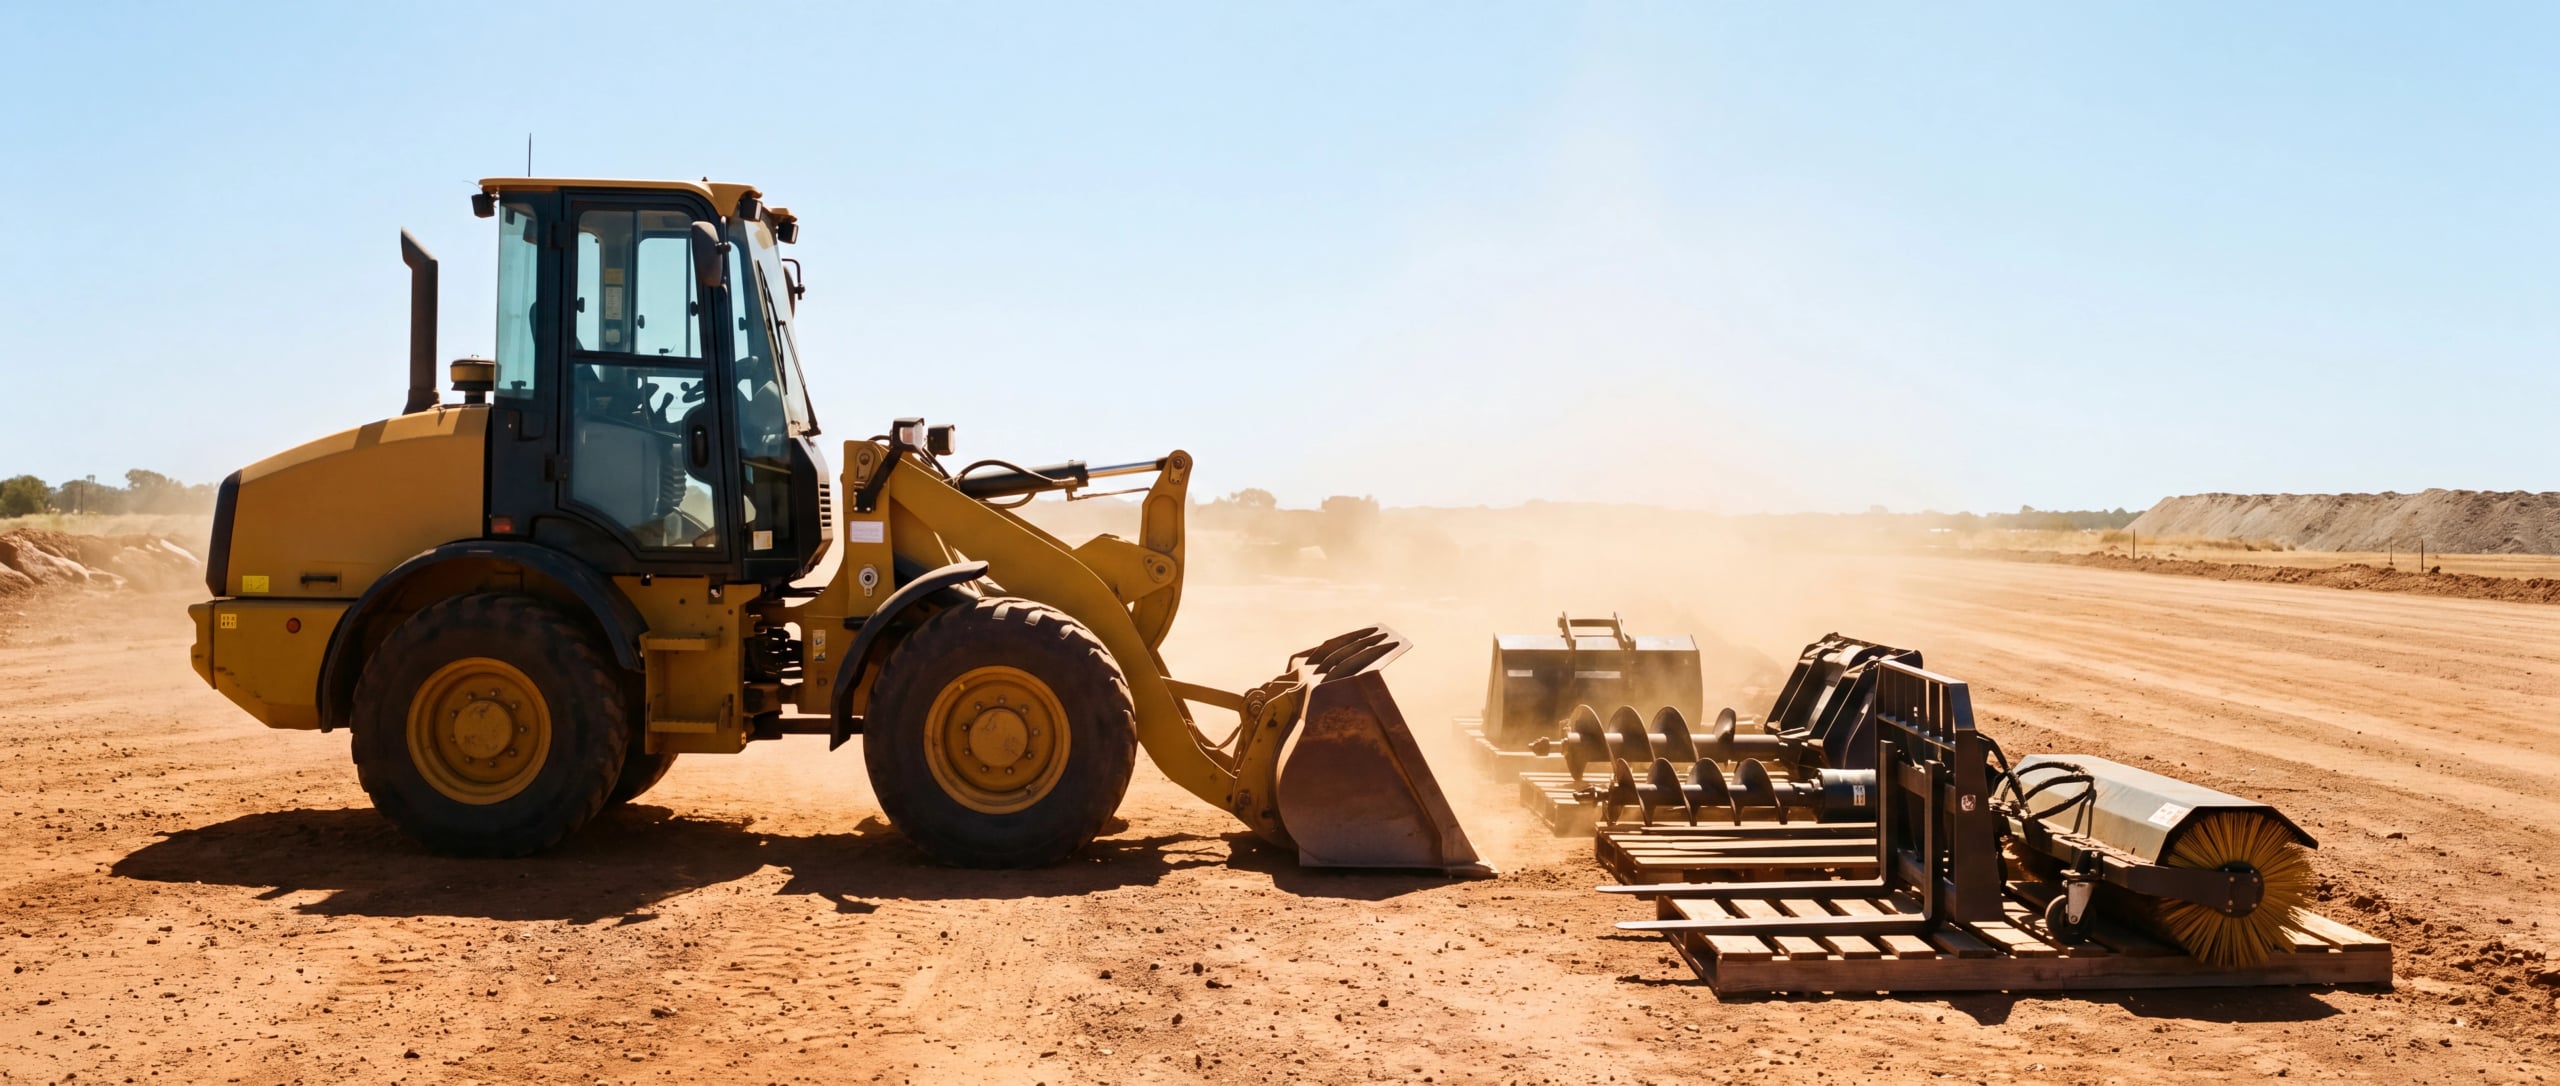
Equipment finance lets a business buy machinery, plant, tools or technology and pay for it over time, with the equipment as security. The usual structures are a chattel mortgage, a lease or hire purchase. It suits sole traders, companies and newer ABNs buying new, used or from a private seller.
Whether you're buying construction plant, manufacturing equipment or agricultural machinery, we compare equipment lenders across our panel to find a structure that suits your business.
All equipment types. Same day pre-approval possible.
Broker vs bank,
a real comparison
Asset-specific structures
Equipment finance structures differ by asset type, business use and tax position. We match the right one to your situation.
GST and depreciation considerations
The correct structure can affect how GST and depreciation are treated. We work alongside your accountant.
New and used assets covered
We arrange finance for both new equipment from dealers and quality used plant from the secondary market.
Low doc options available
Self-employed and small business owners with non-standard income documentation can still access equipment finance.
The process
Share details about the asset you need, how it will be used and your business structure.
We search the market for structures and rates suited to your asset type.
We present options with rates and terms explained in everyday terms before you decide.
Once approved, we manage settlement and your equipment is ready to generate revenue.
Some of the lenders on our panel
Compare equipment finance structures side by side
Common ways to fund plant and machinery, and where each fits.
New Equipment
Used and Auction
Low-Doc (ABN)
Step 1 of 5
Equipment finance funds the plant and machinery a business depends on, such as earthmoving gear, manufacturing lines, agricultural machinery, medical and workshop equipment. The asset itself secures the loan, most commonly under a chattel mortgage.
Lenders classify equipment by how readily it can be resold. Wheeled and tracked assets with strong secondary markets are the easiest to finance. Specialised or fixed plant needs a lender who is comfortable with that industry, which is why a wide panel helps.
New, used, dealer, auction and private purchases can all be funded, with terms usually between one and seven years.
Equipment earns money over years, and financing lines the cost up with the income it produces. Working capital stays in the business for materials, wages and growth.
A chattel mortgage may allow upfront GST credit and deductions for interest and depreciation, subject to your structure. Confirm with your accountant.
Financing also makes upgrading easier. When a machine reaches the end of its working life, a sensible balloon means replacement is something you planned for rather than a sudden demand on cash.
Match the loan term to how long you'll actually use the machine, not the longest term the lender will offer. When you sell or trade it in, any finance still owing has to be paid out as part of that sale.
Use a lender who actually knows the asset. Yellow goods, agricultural machinery and specialised plant each have lenders who understand that market and lenders who do not. The ones who do tend to approve faster and value the equipment more accurately.
If you are buying used or at auction, speak to your broker before you bid. The valuation and the settlement can then be ready by the time you win it.
One enquiry compares equipment lenders across the lender panel. Your broker shortlists lenders that actively fund your industry and asset type, then runs the application, valuation and settlement.
Have your ABN details, financials or bank statements, and the equipment details ready. Pre-approval is possible the same day for many straightforward applications, and there are low-doc options for businesses without current financials.
Buy based on what the machine earns you each week versus what it costs you each week, including the finance repayment.
Don't rule out used equipment with a good service history. There are lenders who'll fund it, and the numbers often stack up better than buying new.
Talk to your accountant early about how depreciation will work for the purchase. Keep your paperwork up to date too, so you are not ruling out lenders without realising it.
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$1,547
per month
Weekly
$357
Total repayment
$92,797
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quote6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
The machine earns
before it is paid for.
Equipment finance should follow the work, not the calendar. Your broker matches the term and the repayment shape to how the asset actually earns, across the lenders that understand your industry.
Written by a licensed broker for Australian businesses.
 5 guidesEquipment financeMachinery, plant and business equipment financed against the asset itself.Explore equipment finance
 Machinery Finance: New, Used and Private SaleHow machinery finance treats new stock, used gear and private sales, from excavators to tractors and forklifts, and where each deal tends to fit.Should You Buy or Finance Business Equipment?Paying cash feels virtuous and is sometimes wrong. How to weigh working capital, asset life and opportunity cost when choosing to buy outright or finance.How to Finance Equipment as a Sole TraderSole traders reach the same equipment finance market as companies. How you are assessed, the documents that work and what a new ABN changes.Low-Doc Equipment Finance ExplainedLow-doc equipment finance funds business assets on alternative income evidence. Who it suits, the documents lenders accept.See all 5 equipment finance guides
Who we help
Excavators, bobcats, cranes and civil construction plant financed around project timelines.
Tractors, harvesters and agricultural machinery finance for farms and agribusiness.
CNC machines, production lines and manufacturing plant financed for Australian businesses.
Specialist trade equipment for mechanics, fabricators and industrial operators.
Any business needing equipment financed with the right structure and tax treatment.
Australian registered business (sole trader, company, trust or partnership)
ABN registered (brand new to established, lender-dependent)
Equipment used for genuine business purposes
Acceptable business credit history
Financial statements, BAS or bank statements available
We arrange finance for a wide range of business assets including construction plant, agricultural machinery, manufacturing equipment, medical devices and trade equipment. If your business uses it to generate income, it can likely be financed.
If your business is GST-registered and the equipment is used for business purposes, you may be eligible to claim the GST input tax credit. The treatment depends on the finance structure. Confirm with your accountant.
It depends on your tax position and whether you want to own the asset at the end of the term. We present both options with the implications explained so you can decide alongside your accountant.
Yes. We arrange finance for quality used plant and equipment from dealers and private sellers. Asset age and condition affect lender eligibility.
Typically ABN, financial statements or BAS, and business bank statements. Low doc options are available for businesses with non-standard income documentation.
Pre-approval is typically possible the same day we receive your application and supporting documents.
Some lenders consider newer ABNs, particularly where the operator has industry experience and the equipment has a strong resale market. Options are more limited than for established businesses, and we will tell you honestly where you stand.
Not always. Established businesses frequently fund the full equipment price under a chattel mortgage. Deposits help marginal applications and can shorten approval times, but they are not a blanket requirement.
Terms typically run 1 to 7 years, matched to the machine's productive life. Balloons are available on many structures and are best sized against the equipment's realistic resale value at term end.
Yes. Used, private sale and auction equipment can all be financed, with valuation and ownership checks handled as part of settlement. Talk to your broker before auction day so funding is ready when the hammer falls.
We call you within one business day, generally within the hour, to talk through your options without the jargon, with no obligation. Pre-approval for most standard equipment applications follows the same day.