
Car Finance
Buying a Car Privately: How Finance Works for Private Sales
By Joseph Nowland, Director and Senior Finance Broker · 18 July 2026 · 3 min read
Last reviewed 26 July 2026
Yes, you can finance a private sale
A persistent myth says car finance is only for dealer purchases. In reality, a large share of the lenders on our panel finance private sales routinely, using the same secured used car loan structure with a settlement process adapted for a private seller instead of a dealership.
The differences are procedural, not fundamental. The lender needs the confidence a dealer would normally provide, meaning proof that the seller actually owns the car, that no other lender has money owing against it, and that the payment lands safely. The process below exists to establish exactly that.
Agree the deal before the handover
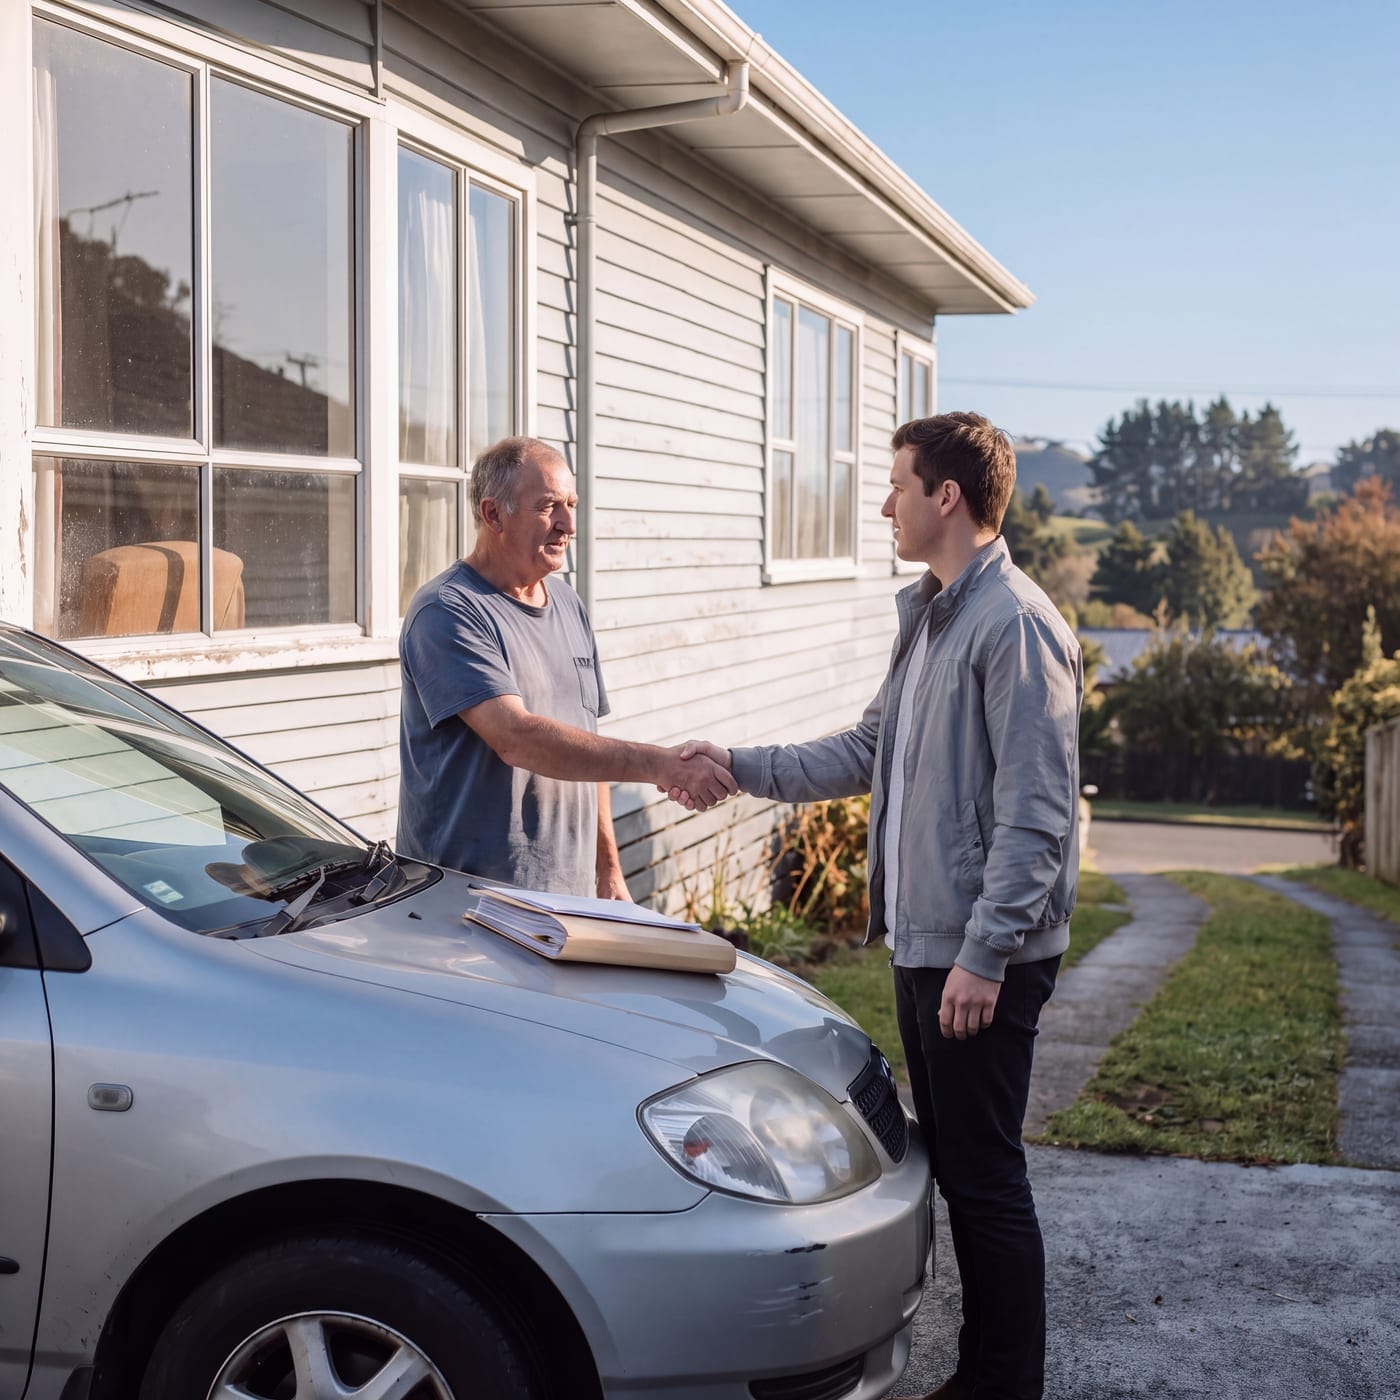
Once you have found the car and agreed a price, hold off on handing over money or collecting keys. Instead, gather the details the finance needs, which are the make, model, year, kilometres, VIN, registration, the agreed price, and the seller's name and contact details.
This is also the moment for pre-approval if you do not already have it. Sellers respond to buyers whose money is organised, and a confirmed budget stops the negotiation drifting.
The checks that protect you
Before settlement, we confirm the car is what the seller says it is. A PPSR (Personal Property Securities Register) search against the VIN shows whether any lender has a registered interest in the car, because buying a car with money owing on it can transfer that problem to you. Ownership and registration details are verified at the same time.
Some lenders also want a vehicle inspection or condition report for older cars, and an independent inspection is worth considering for your own sake even when the lender does not require one. A few hundred dollars of checking beats inheriting someone else's mechanical problems.
Ready to compare your options?
A broker searches the panel so you see what they can offer for your profile. Takes two minutes.
Get my quoteSettlement, done safely
The part that surprises first-timers is that the lender pays the seller directly. The seller provides their bank details and, where finance is still owing on the car, a payout letter from their lender. At settlement, funds go straight from your lender to the seller, or partly to the seller's financier to clear their loan, and the transaction is documented at every step.
This is safer for both sides than cash in a car park. The seller sees cleared funds from a financial institution, you get a documented transfer tied to the checks above, and nobody stands around while a bank app spins.
Once payment clears, you collect the car, transfer the registration, and the loan runs like any other secured car loan from that point on.
What it needs from you and the seller
You provide your driver's licence, proof of address, income evidence, and the loan paperwork your broker prepares. The seller provides photo ID, proof of ownership such as registration papers, bank details for payment, and a payout letter if their own loan is still running.
Timing runs a little longer than a dealer purchase. Allow roughly three to seven business days from approval to settlement, mostly for the verification and direct payment steps. Your broker keeps both you and the seller informed so the extra days do not turn into confusion.
Private sale finance, compared properly
Not every lender does private sales, and the ones that do vary in how smoothly they run them. That makes lender choice matter more here than in most car purchases. One enquiry with Morella Finance compares private-sale-friendly lenders across the lender panel and manages the whole settlement, checks included, so the better price a private sale offers is not cancelled out by process risk.
Ready to compare your options?
This guide is general information. When you are ready, see how it applies to your situation.

This guide is general information, not financial or credit advice. Consider your circumstances and check details with your broker or accountant.
Start here
Compare lenders in two minutes
No obligation, no impact on your credit score at quote stage. A broker will follow up with real options matched to your situation.
Step 1 of 3
What are you financing?
Select a finance type and tell us your loan amount.
Keep reading
Related guides
 Car Finance 101: The Complete Guide for First-Time BuyersThinking about financing your next car? How a car loan actually works, what lenders look at, and how the process runs from enquiry to settlement.
 How Car Loan Pre-Approval Works (and Why It Matters)Pre-approval tells you what you can borrow before you shop, strengthens your negotiating position and takes dealer finance pressure off the table.
 How Your Credit Score Affects Your Car LoanYour credit file shapes which lenders will approve you and on what terms. How scores work in Australia, what lenders actually look at.