
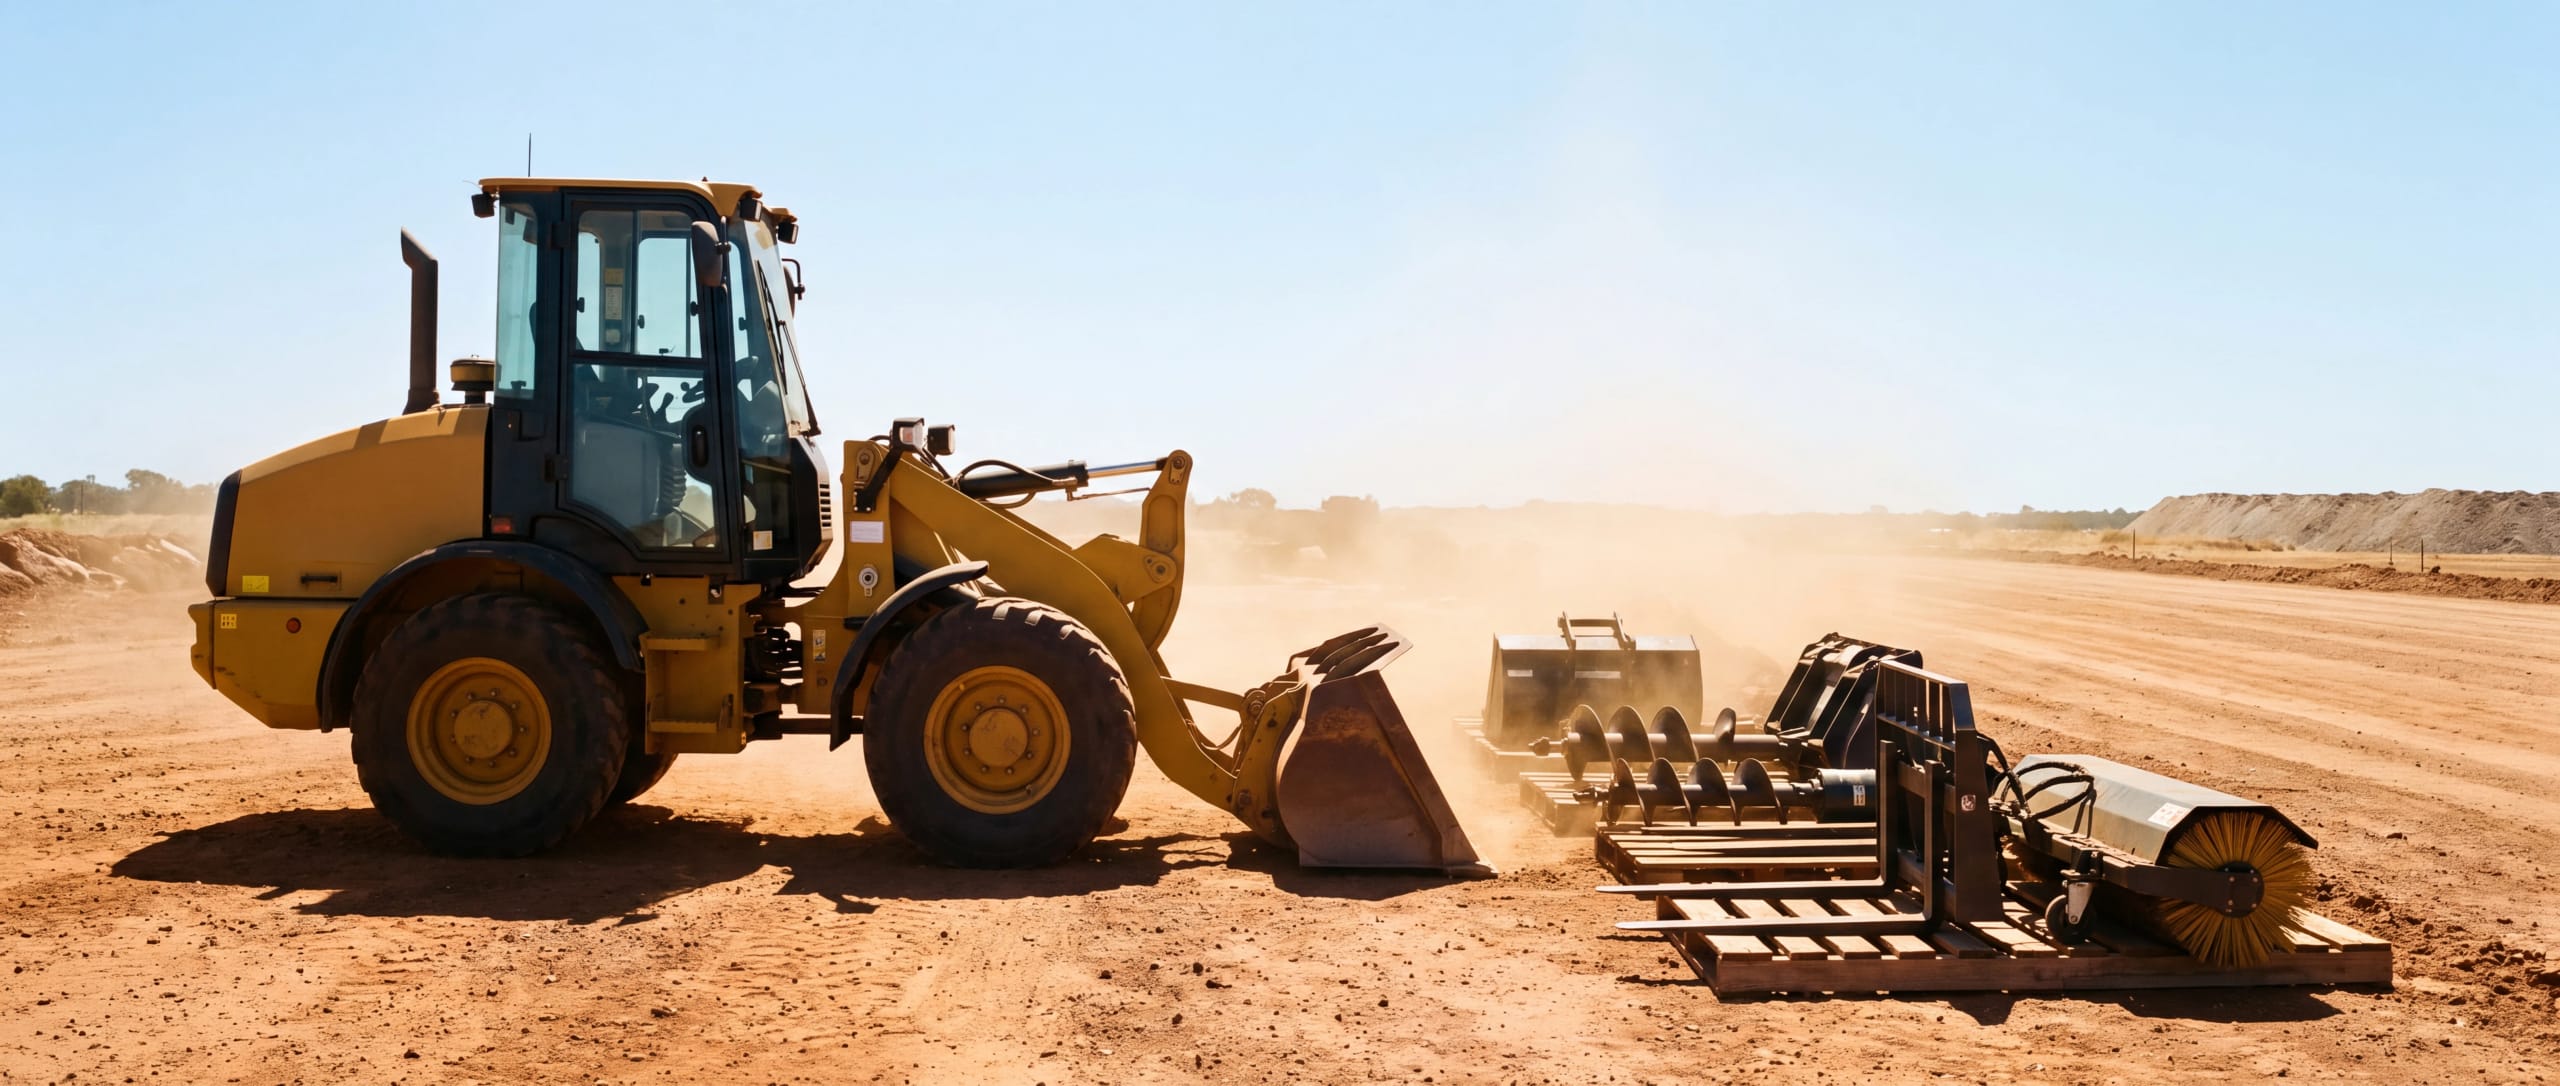
Machinery and Heavy Equipment Finance for Your Business.
From excavators and cranes to harvesters and CNC machines, we compare machinery finance lenders across our panel to find the right structure for your asset purchase.
All machinery categories. Same day pre-approval possible.
Machinery Finance: Broker vs Bank
Broker vs bank,
a real comparison
Heavy plant specialist lenders
Some of the strongest machinery finance pricing comes from lenders who specialise in construction, agricultural and industrial assets.
Asset-specific assessment
Lenders assess machinery differently from vehicles. We match you to those who understand the asset class.
New and used machinery covered
We arrange finance for new plant from dealers and quality used machinery from the secondary market.
Low doc options
Self-employed operators and small businesses with non-standard income can still access machinery finance.
The process
How Machinery Finance Works
Tell us about the machinery
Share details about the plant you're buying, its purpose and your business structure.
We compare the market
We search the panel of equipment and machinery lenders for suited rates and structures.
Review your options
Rates and terms are explained in plain terms before you decide.
Settle and deploy
Once approved, we manage settlement and your machinery is ready to work.
Machinery finance, explained plainly.
Step 1 of 5
Understand machinery finance
Machinery finance funds the plant a business works with, from excavators and loaders through to agricultural and workshop equipment, with the machine itself held as security. It works like any other equipment loan, with the repayments set over a term that suits the working life of the machine.
The lender registers its interest on the PPSR. The assessment looks at the machine and the business together rather than at either on its own.
New, used, dealer, auction and private purchases can all be funded. Where you are buying shapes the shortlist as much as what you are buying.
Why choose machinery finance
A machine earns across years. Heavy equipment finance lets you pay for it over the long term instead of paying the full price up front, so the cost lines up with the income it produces.
Keeping that cash in the business protects your cash flow for materials, wages and the next job. That is usually a better use of it than owning the machine outright a year sooner. Finance also lets the business acquire equipment when the work demands it, rather than waiting until the cash is on hand.
A final balloon payment lowers the regular repayments. Set sensibly, it also makes replacement a planned event rather than something forced by a breakdown.
Deciding if machinery finance fits
Lenders classify plant by how readily it resells. Wheeled and tracked machines with active secondary markets are the most straightforward to place.
Specialised or fixed plant needs a lender who understands that industry, which is why a wide panel matters.
Hours matter the way kilometres do on a vehicle, and a high-hour machine with documented servicing often assesses better than a low-hour one without records.
How to apply for machinery finance
Start with the ABN, the trading history and the machine, including its make, model, year and hours. That combination sets the shortlist. Each lender sets its own eligibility criteria for trading history, business credit and the type of machine.
If you are buying at auction, bring your broker in before you bid, so the valuation and the settlement are arranged ahead of time.
One enquiry compares lenders, and pre-approval on a straightforward application is possible the same day.
Tips for machinery finance
Buy on what the machine earns each week against what it costs each week, with the repayment included in that sum.
Do not dismiss used plant with a solid service history. There are lenders who will fund it and the numbers frequently work out better than buying new.
Chattel mortgage, hire purchase and finance lease are the main loan options, and they differ in who owns the machine during the term. Ask your accountant how each one affects your tax position and your balance sheet before you choose.
Keep the business paperwork current so lenders are not ruled out unnecessarily.
Machinery finance at a glance
- The machine is held as security with the interest registered on the PPSR
- Lenders classify plant by how readily it can be resold
- Hours are read alongside age, and a documented service history matters
- Dealer, auction and private purchases can all be funded
- Lenders compared through one enquiry, with same day pre-approval possible
Machinery Finance for Australian Businesses
Heavy plant and equipment is one of the most significant capital investments a business makes. We help you finance it with the right structure from day one.
Get my quoteA Panel of Lenders
We compare equipment and machinery finance lenders across our full panel to find the right structure for your business.
Same Day Pre-Approval Possible
Know your borrowing capacity before committing to an equipment purchase or signing a supplier contract.
All Equipment Types
From construction plant and agricultural machinery to medical equipment and manufacturing assets.
Low Doc Options
Self-employed business owners with non-standard income documentation are catered for.
New and Used Equipment
We arrange finance for both brand-new equipment from dealers and quality used assets from the secondary market.
One Contact, Start to Finish
A dedicated broker manages your application from enquiry through to settlement. No handoffs, no repeated explanations.
Equipment Finance Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$1,547
per month
Weekly
$357
Total repayment
$92,797
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteAbout the starting rate
6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
More Equipment and Business Finance Options
The machine earns
before it is paid for.
Equipment finance should follow the work, not the calendar. Your broker matches the term and the repayment shape to how the asset actually earns, across the lenders that understand your industry.
Equipment Finance Guides
Written by a licensed broker for Australian businesses.
 5 guidesEquipment financeMachinery, plant and business equipment financed against the asset itself.Explore equipment finance
 Machinery Finance: New, Used and Private SaleHow machinery finance treats new stock, used gear and private sales, from excavators to tractors and forklifts, and where each deal tends to fit.Should You Buy or Finance Business Equipment?Paying cash feels virtuous and is sometimes wrong. How to weigh working capital, asset life and opportunity cost when choosing to buy outright or finance.How to Finance Equipment as a Sole TraderSole traders reach the same equipment finance market as companies. How you are assessed, the documents that work and what a new ABN changes.Low-Doc Equipment Finance ExplainedLow-doc equipment finance funds business assets on alternative income evidence. Who it suits, the documents lenders accept.See all 5 equipment finance guides
Who we help
Who We Help with Machinery Finance
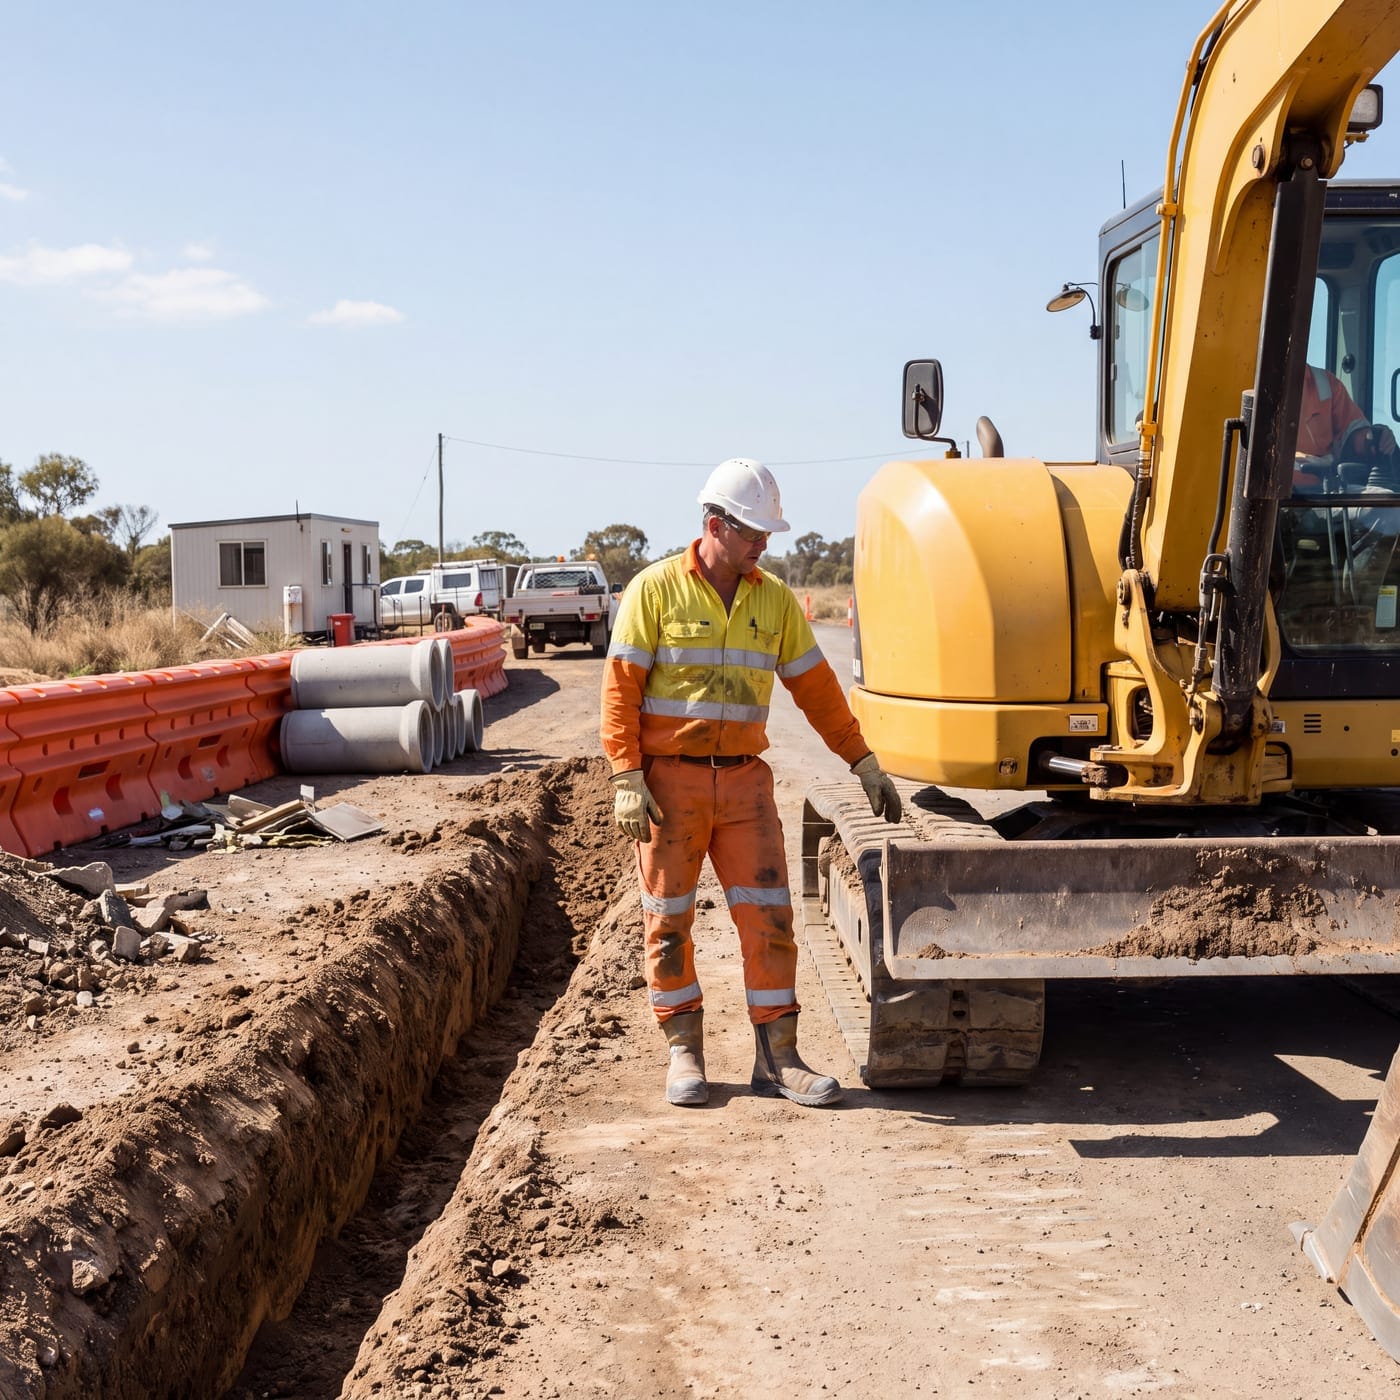
Civil Contractors
Excavators, graders and civil plant for construction and infrastructure projects.
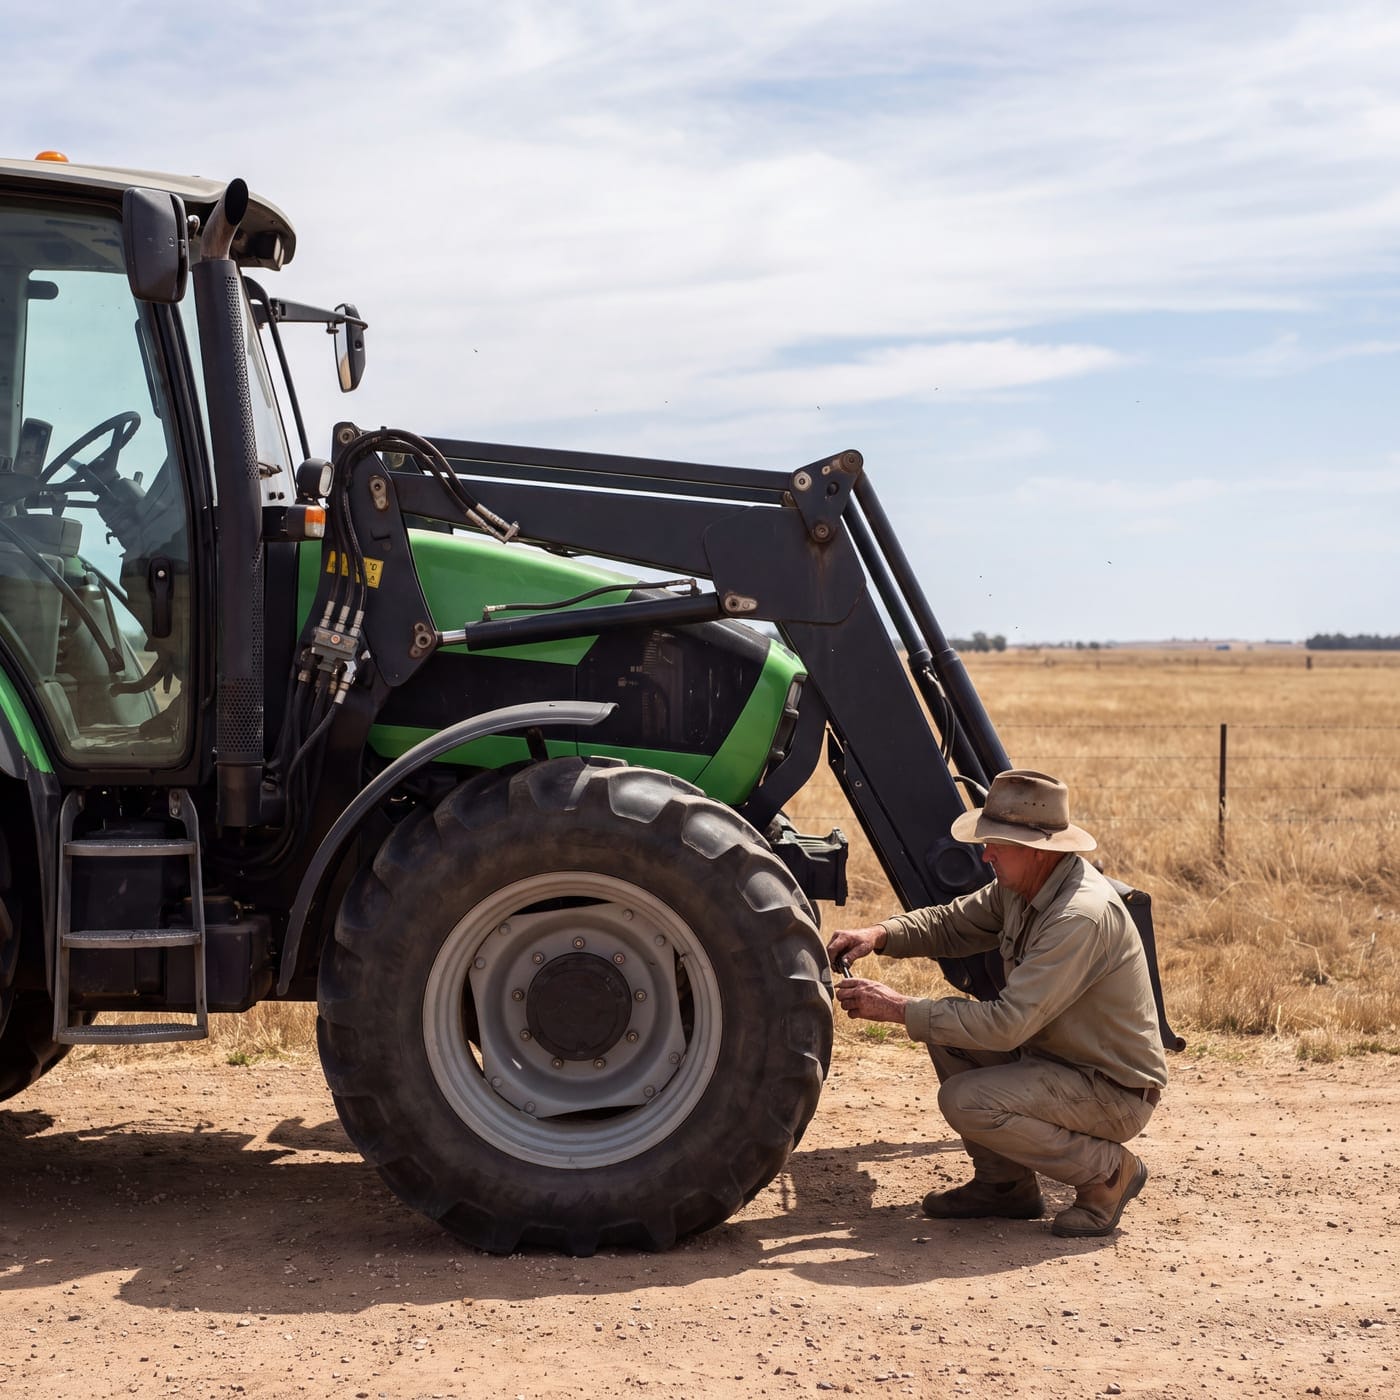
Farmers and Agribusiness
Tractors, harvesters and agricultural machinery for farms and rural businesses.
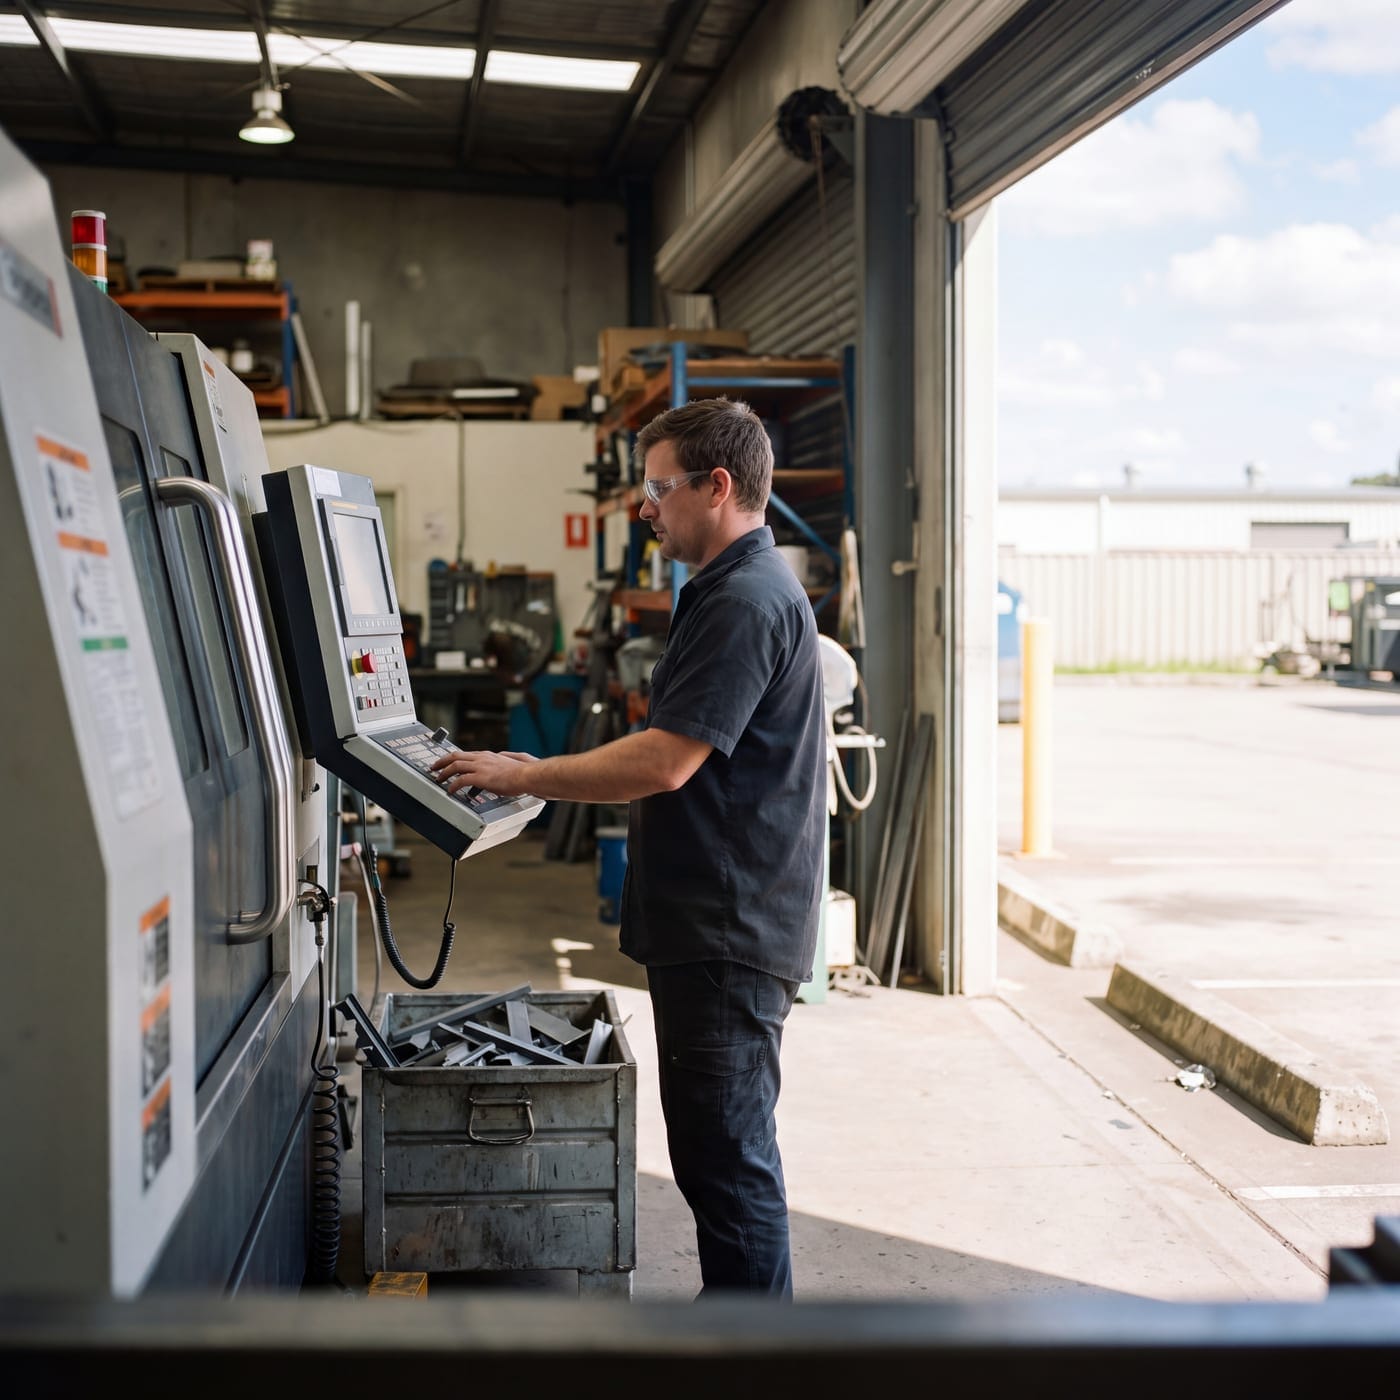
Manufacturers
CNC machines, lathes and industrial plant for manufacturing businesses.
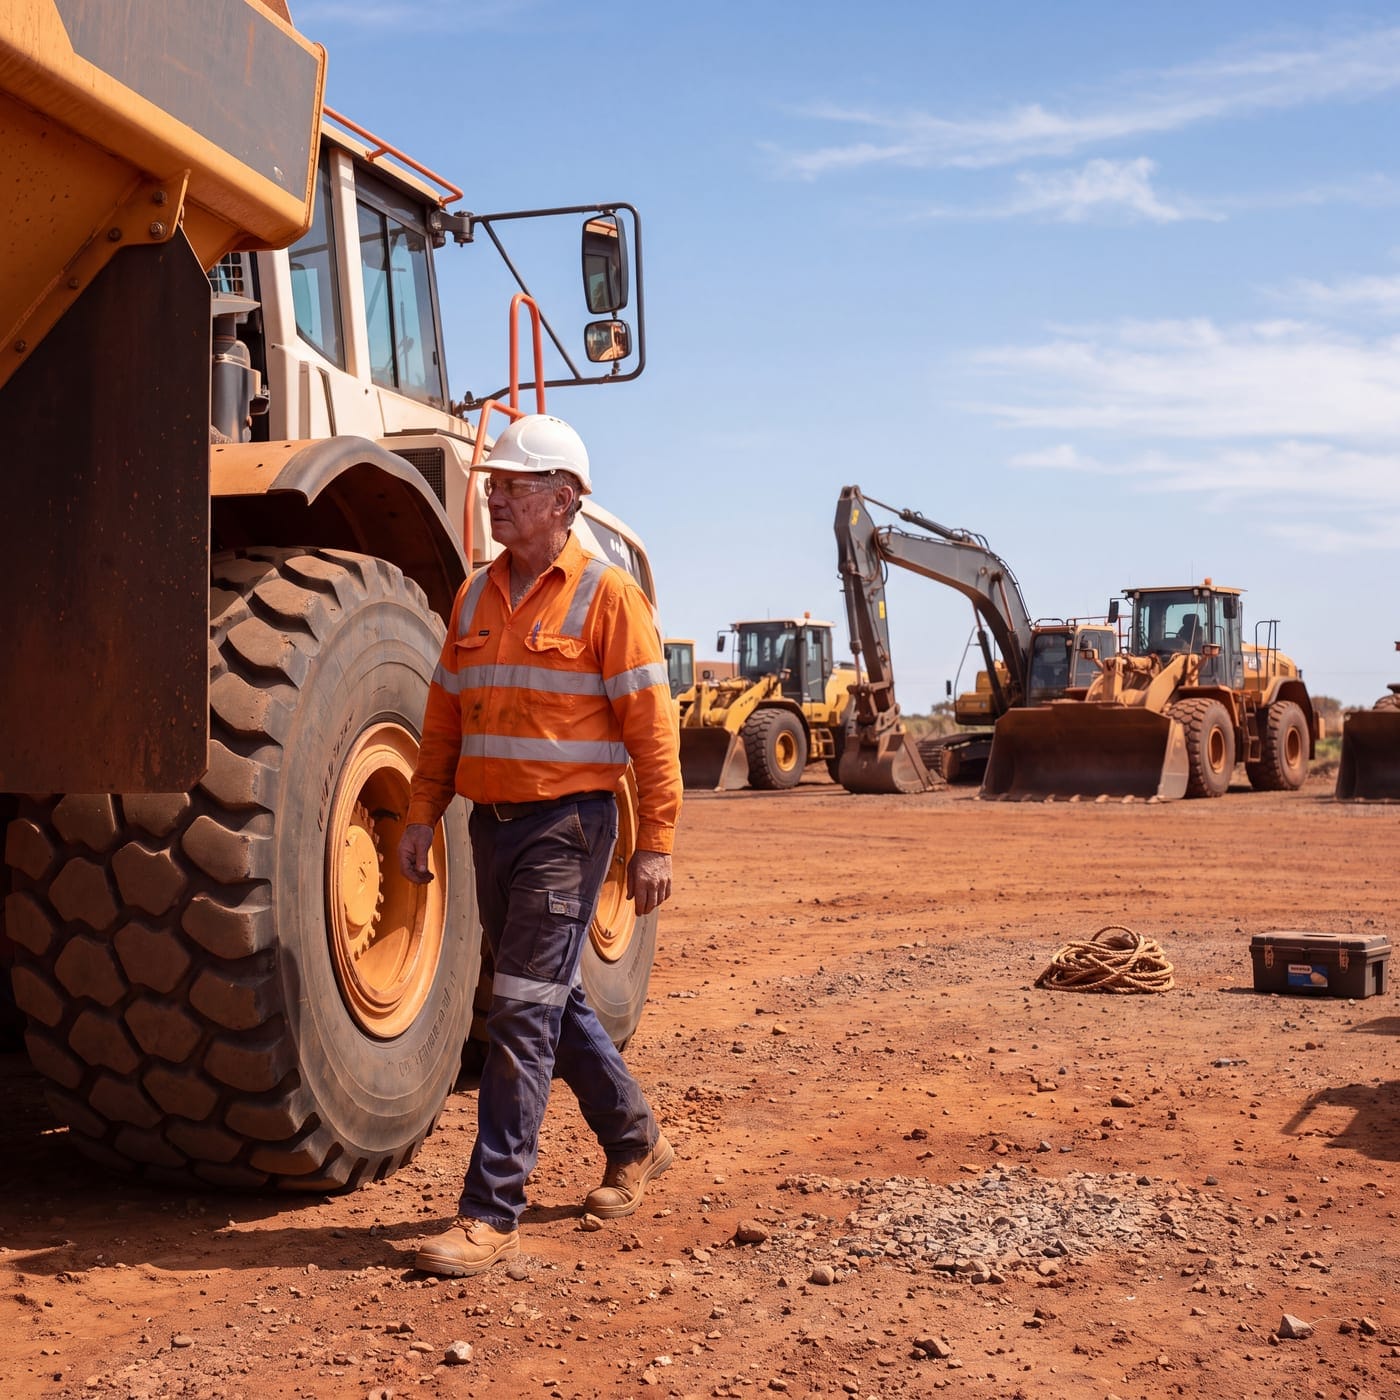
Mining Contractors
Specialist plant and equipment for mining and resource sector operations.
Industrial Operators
Any business requiring specialist machinery financed with the right structure.
Australian registered business
ABN registered with acceptable trading history
Machinery used for genuine business purposes
Acceptable business credit history
Financial statements, BAS or bank statements available
Machinery Finance FAQs
We finance a wide range of heavy plant and equipment including excavators, cranes, bulldozers, agricultural machinery, manufacturing plant and industrial equipment. If your business uses it to generate income, it can likely be financed.
Yes. We arrange finance for quality used plant from dealers and private sellers. Asset age, condition and intended use affect lender eligibility.
You own the machinery from day one. The lender holds a mortgage over it until the loan is repaid. Ask your accountant how it affects your tax position.
Yes. Low doc options are available for self-employed operators and small business owners, assessed on an active ABN and a driver's licence in place of full financials. Banking is requested only where the ABN is under 6 months old.
Requirements vary by lender and asset value. Some lenders offer low-deposit options for established businesses. We advise on what's available for your specific application.
Pre-approval is typically possible the same day we receive your application details and supporting documents.