
Commercial Vehicle Finance. The Right Structure for Your Business.
From work vans to light commercials, we compare commercial vehicle lenders to find a structure that matches your business's tax position and cash flow.
Chattel mortgage, lease and hire purchase. Same day pre-approval possible.
Commercial Vehicle Finance: Broker vs Bank
Broker vs bank,
a real comparison
Structure selection
Chattel mortgage, finance lease or hire purchase each have different implications. We help you choose the right one for your business.
Large lender panel
We access commercial lenders including specialists for specific vehicle types and industries.
GST and depreciation guidance
We work alongside your accountant to ensure the structure aligns with your tax position.
Fast pre-approval
Know your commercial vehicle budget before you commit to a purchase order.
The process
How Commercial Vehicle Finance Works
Tell us about your business
Share details about the vehicle you need, how it will be used and your business structure.
We compare the market
We search the panel for structures suited to your vehicle and business type.
Review your options
Rates, terms and structures are presented clearly in plain English before you decide.
Settle and deploy
Once approved, we handle settlement and your vehicle is ready for work.
Commercial vehicle finance, explained plainly.
Step 1 of 5
Understand commercial vehicle finance
Commercial vehicle finance funds the vans, utes and light trucks a business runs, with the vehicle itself standing as security and the lender's interest recorded on the PPSR.
The structure is the first decision rather than an afterthought, because a chattel mortgage, a lease and a hire purchase each place ownership and the balance sheet treatment differently.
Terms run from one to seven years, and the application is assessed on the business as much as on the person signing it.
Why choose commercial vehicle finance
A work vehicle earns while it is being paid for, so matching the repayment to the revenue it generates keeps working capital where the business needs it.
Financing also keeps a replacement cycle predictable. A vehicle reaching the end of its useful life becomes a planned changeover rather than an unbudgeted expense.
Depending on the structure and how the vehicle is used, there may be GST and depreciation consequences. Your accountant should confirm what applies to your situation.
Deciding if commercial vehicle finance fits
The test is how the vehicle is used, not what it looks like. A ute driven mainly for personal use may actually be better suited to consumer finance.
How long the business has been trading affects which lenders are available. Established businesses can access more of the panel, while newer ABNs are matched to lenders who assess them on their own terms.
If the vehicle needs a body, tray or fit-out, sort that out before you apply, so the finished vehicle is what gets financed rather than just the bare cab.
How to apply for commercial vehicle finance
Start with the ABN, how long the business has traded and what the vehicle will do. Those three shape which lenders are worth approaching.
One enquiry compares lenders rather than lodging separately with each, which keeps enquiries off your file and the credit report intact.
Same day pre-approval is possible for straightforward applications, and your broker manages the supplier payment through to delivery.
Tips for commercial vehicle finance
Talk to your accountant about the right structure before you sign anything. It's much harder to undo the wrong choice later than to get it right from the start.
Match the loan term to how long you'll actually use the vehicle. You don't want to still be paying off a van you've already retired from the fleet.
Keep your business paperwork up to date. An outdated ABN or registration detail is the sort of thing that can slow down an otherwise straightforward application.
Commercial vehicle finance at a glance
- Terms run from 1 to 7 years with the vehicle held as security
- Chattel mortgage, lease and hire purchase each sit differently on the books
- How the vehicle is used decides whether it is commercial or consumer lending
- Bodies and fit-outs are best decided before the application, not after
- One enquiry covers lenders, with same day pre-approval possible
Commercial Vehicle Finance for Every Business Type
The right finance structure depends on your business type, how you use the vehicle and your accounting approach. We match all three.
Get my quoteA Panel of Lenders
We compare commercial vehicle and fleet lenders across our full panel to find the right structure for your business.
Same Day Pre-Approval Possible
Know your borrowing power before you commit to a purchase or tender a fleet order.
All Vehicle Categories
From light commercial utes and vans to heavy trucks and semi-trailers, we finance the full commercial range.
Fleet Finance Available
Financing multiple vehicles for your business? We arrange fleet structures that scale with your operation.
Low Doc Options
Self-employed and small business owners with non-standard income documents are catered for.
Rate Comparisons Upfront
We present rates and structures side by side, jargon-free, before you commit to anything.
Commercial Finance Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$1,409
per month
Weekly
$325
Total repayment
$67,637
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteAbout the starting rate
6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
More Commercial Finance Options
Choosing the Right
Structure.
There are several ways to finance a commercial vehicle, and the right one depends on how the business is set up and how the vehicle is used. Your broker matches the structure to the business, and you confirm the treatment with your accountant.
Commercial Finance Guides
Written by a licensed broker for Australian businesses.
 8 guidesCommercial financeUtes, trucks and work vehicles for ABN holders, including low-doc options.Explore commercial finance
 GST and Tax Treatment of Vehicle Finance in Plain EnglishHow GST, deductions and depreciation sit alongside business vehicle finance, laid out simply for the conversation with your accountant.New ABN? How to Finance a Work VehicleA young ABN narrows the lender pool without closing it. What lenders want to see, and the evidence that carries a new business over the line.Chattel Mortgage vs Lease vs Hire Purchase: Which Structure Suits Your Business?Three structures finance most Australian business vehicles, and they differ on ownership, tax mechanics and what happens at the end of the term.
 Chattel Mortgage Explained: The Complete GuideThe chattel mortgage is the workhorse of Australian business vehicle finance. How it works, who it suits, how balloons fit.See all 8 commercial finance guides
Who we help
Who We Help with Commercial Vehicle Finance
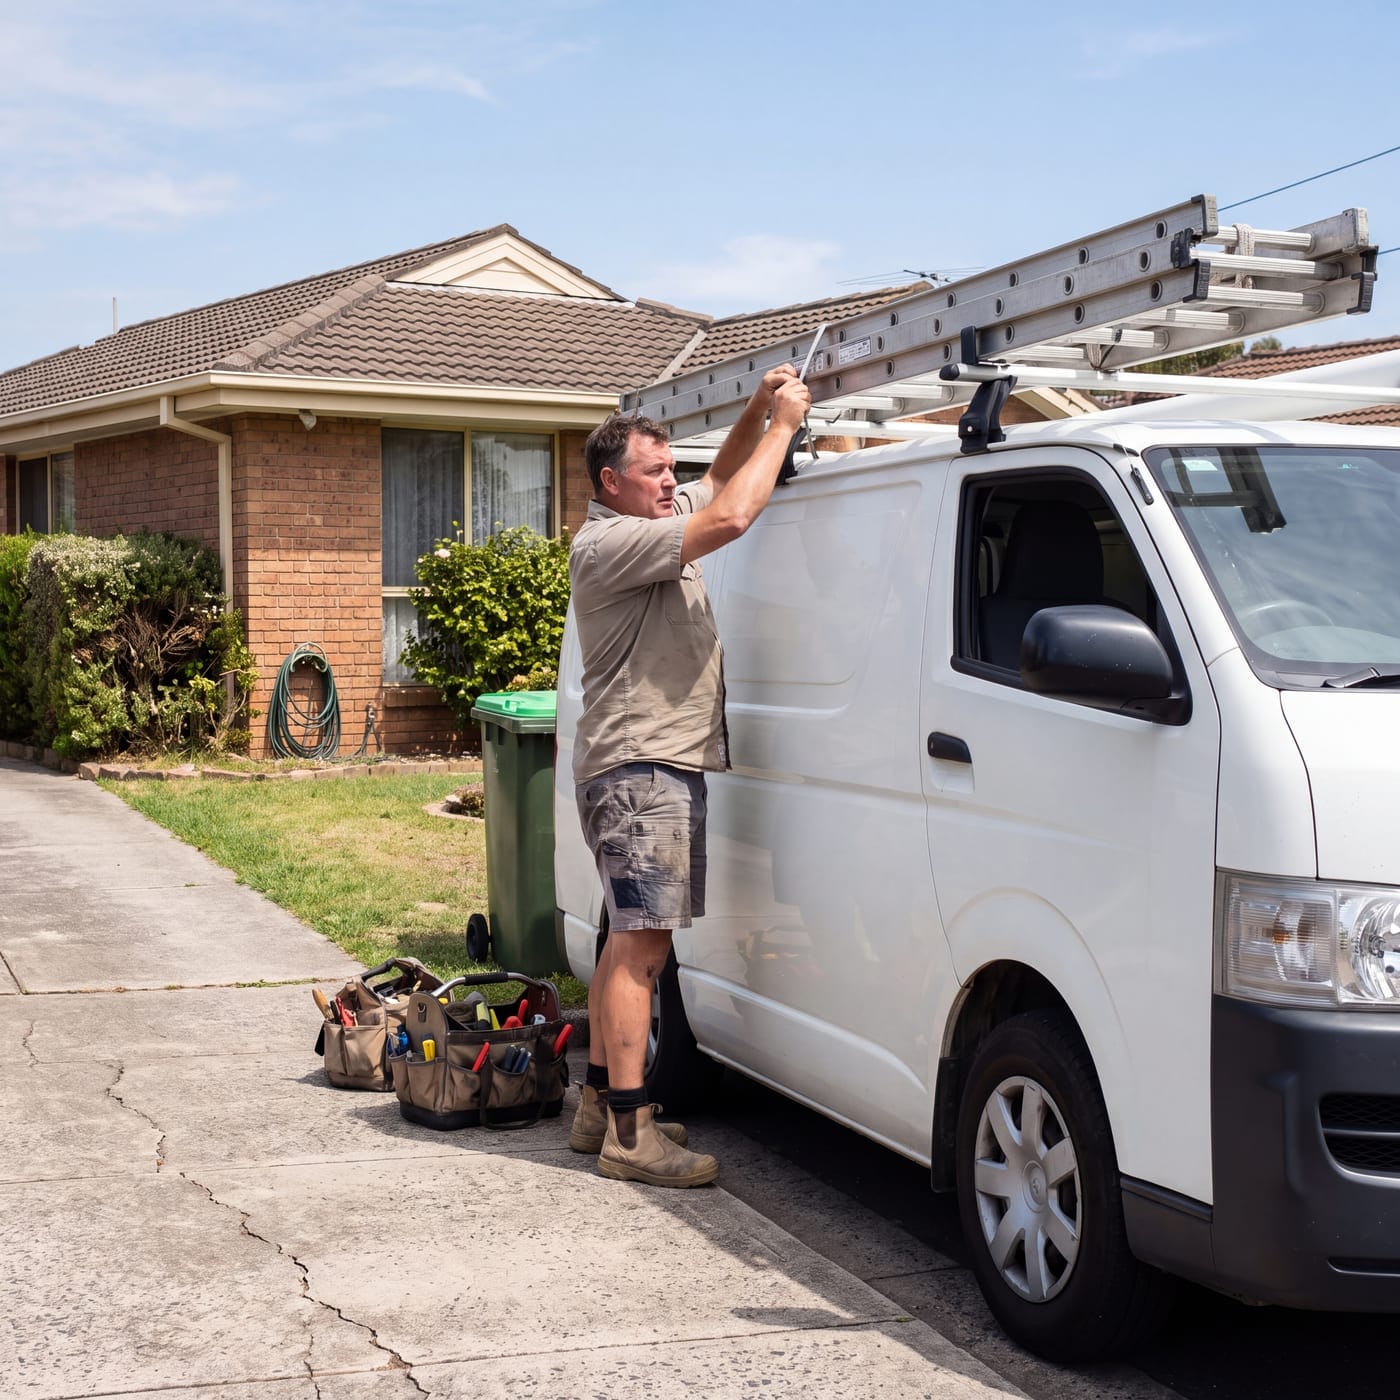
Tradespeople
Work vans, utes and trailers financed around the way your business earns and spends.
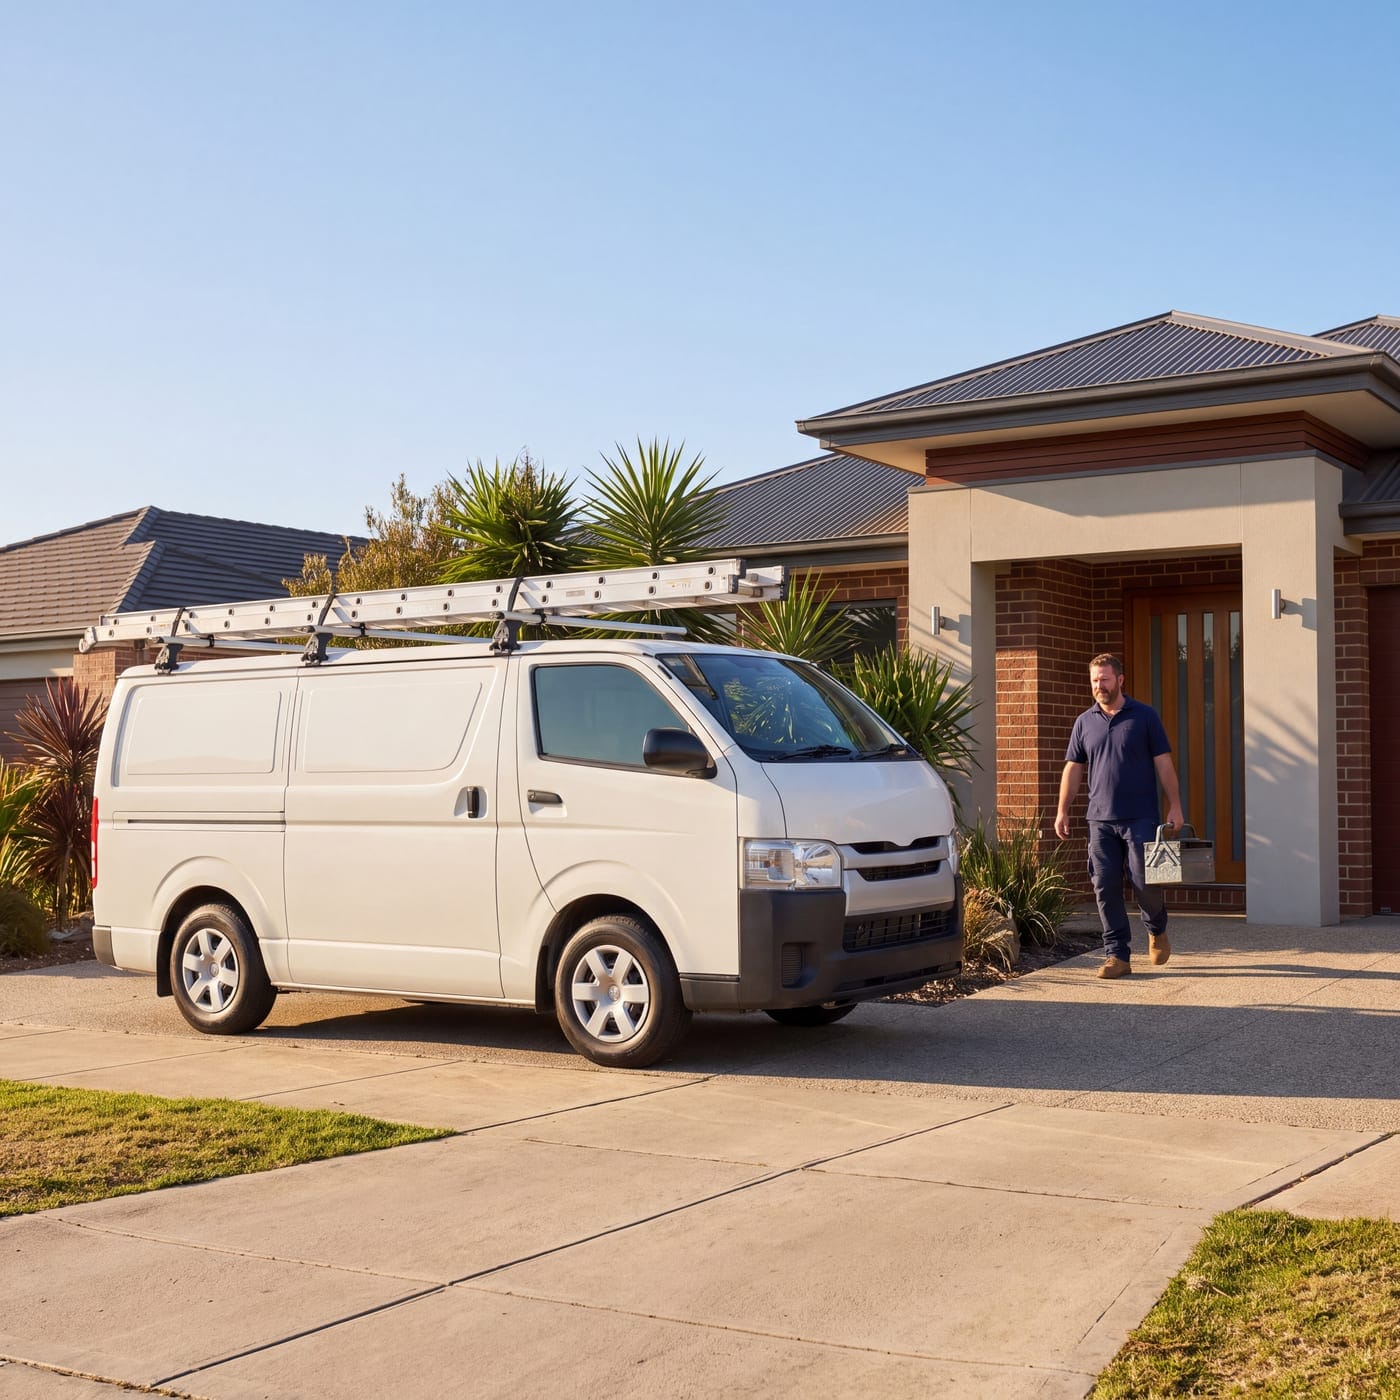
Service Operators
Light commercial vehicles for mobile service businesses and delivery operators.
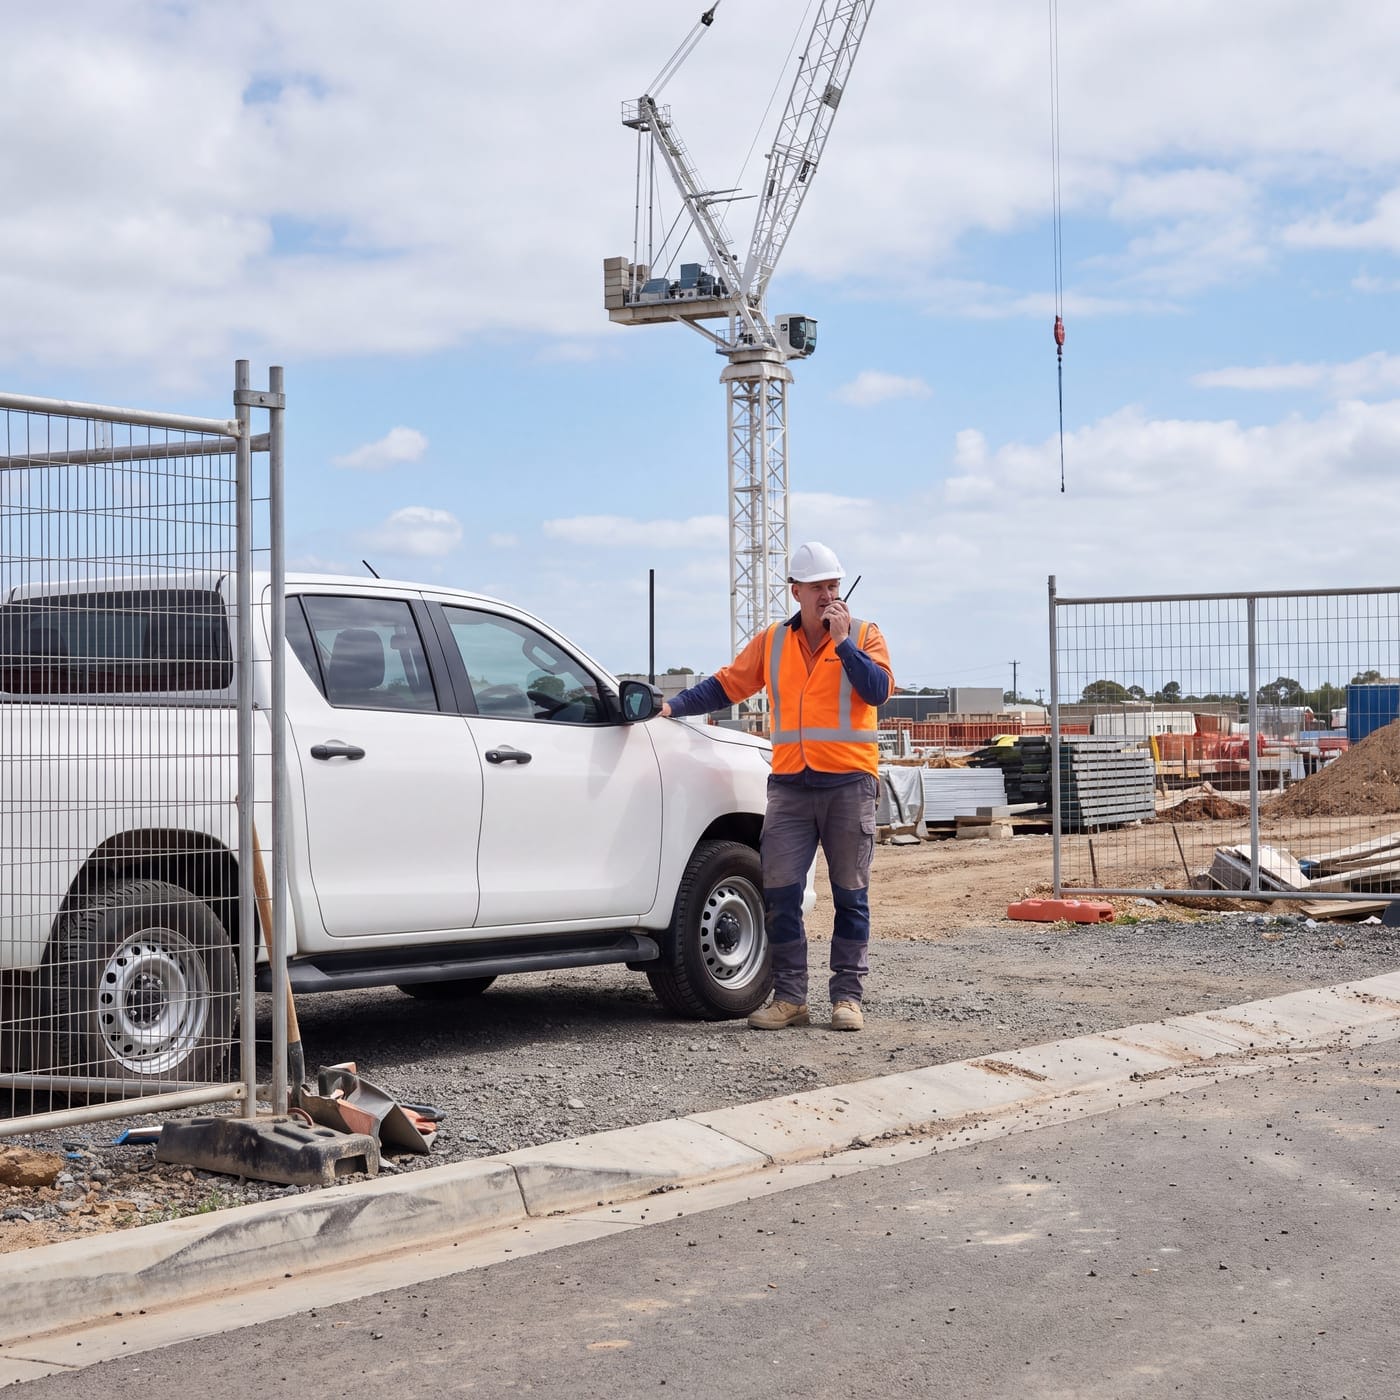
Construction Firms
Commercial vehicles to support a building or civil construction project.
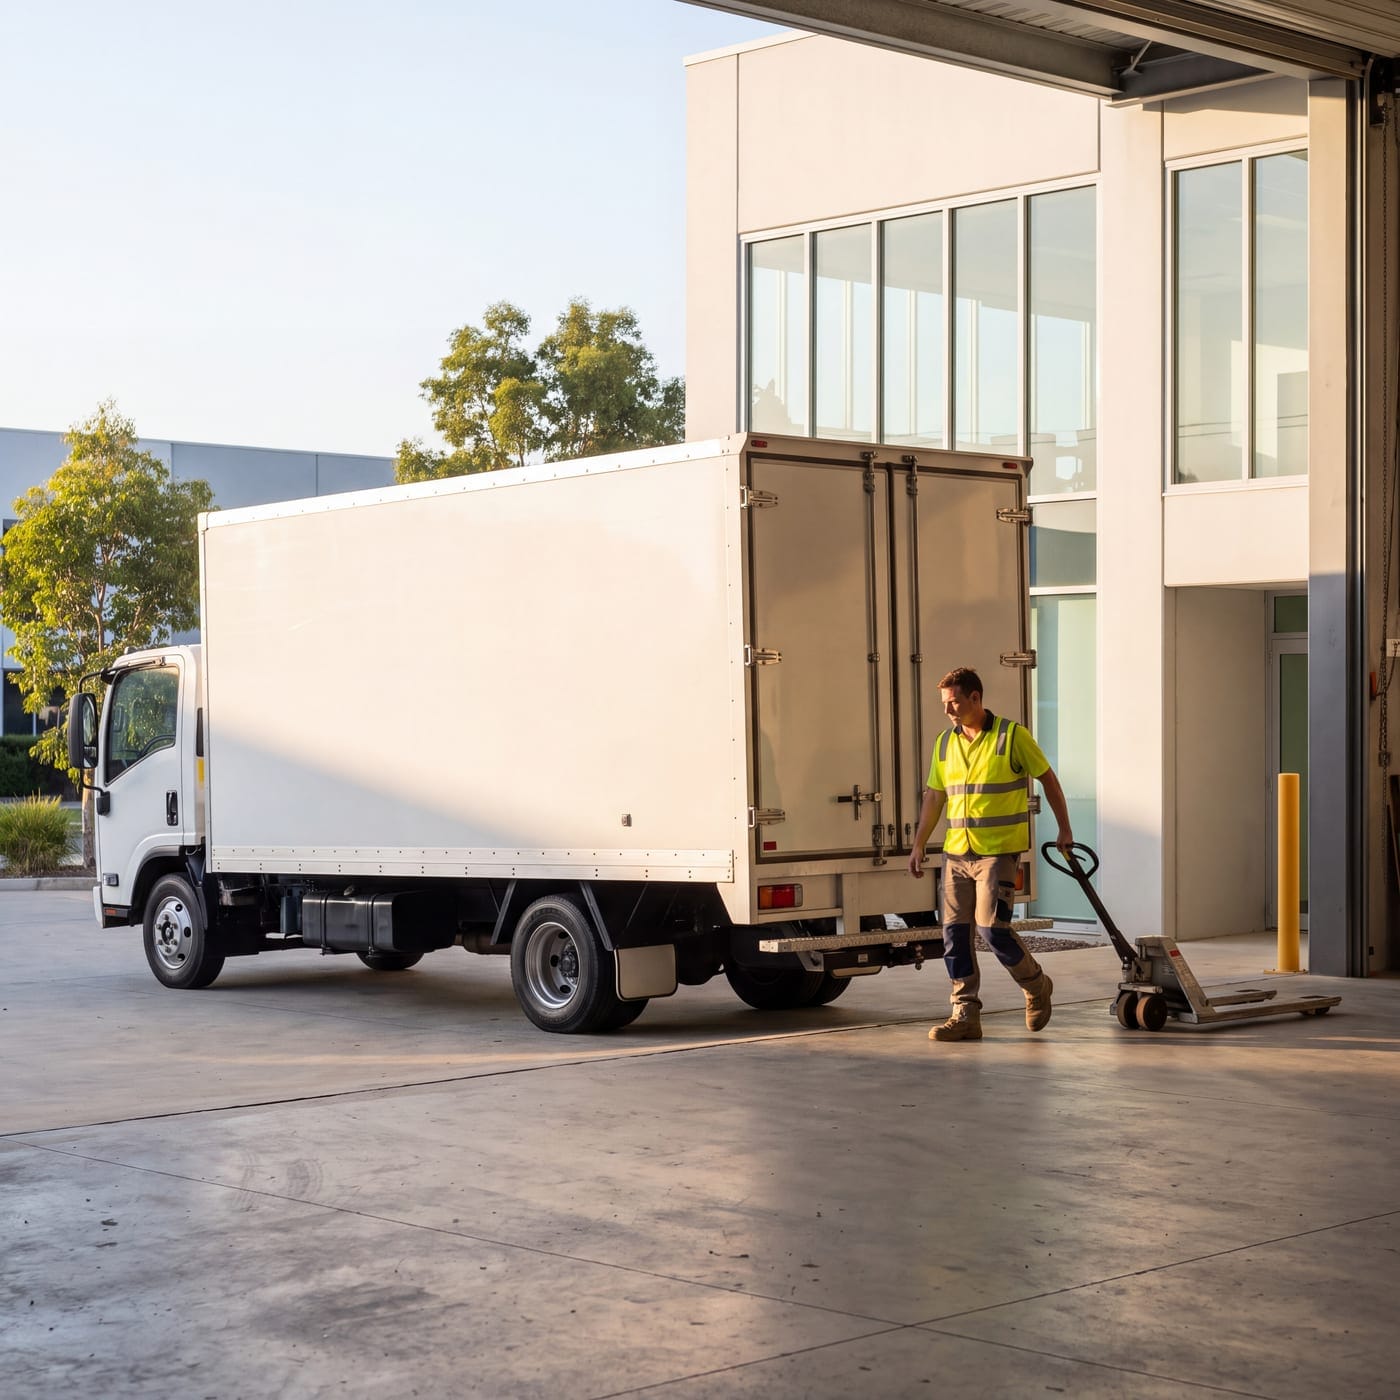
Logistics Businesses
Work vans and light trucks for delivery and logistics operations.
Business Owners
Any business needing a commercial vehicle with the right structure from day one.
Australian registered business (sole trader, company, trust or partnership)
ABN registered (brand new to established, lender-dependent)
Vehicle used for genuine commercial or business purposes
Acceptable business credit history
Financial statements, BAS or bank statements available
Commercial Vehicle Finance FAQs
Yes. Sole traders are eligible for chattel mortgage and other commercial vehicle finance products. ABN registration and income documentation are typically required.
It depends on your tax position, business structure and whether you want to own the vehicle. We present both options with the implications explained so you can decide with your accountant.
Yes. We arrange commercial finance for both new and used work vehicles. Age and condition criteria vary by lender.
Some lenders require a deposit for commercial vehicle finance. Others don't. We advise on what's required for your specific application.
If your business is GST-registered, you may be able to claim the GST input tax credit on the purchase. The treatment depends on the finance structure. Confirm with your accountant.
Pre-approval is typically possible the same day we receive your application and supporting documents.