
Ute Finance for Tradies and ABN Holders.
Whether you're a sole trader or running a trades business, we compare work ute lenders to find a structure that suits your business and your tax position.
Chattel mortgage and commercial finance. Same day pre-approval possible.
Ute Finance: Broker vs Going Direct
Broker vs bank,
a real comparison
Commercial structure access
Work utes used for business qualify for chattel mortgage and other commercial structures. We match the right one to your situation.
New and used covered
New dual cab utes from dealers and quality used vehicles from private sellers and dealers alike.
Sole trader friendly
Many of our lenders work well with sole traders and small trades businesses.
Pre-approval before you shop
Know your budget before you visit a dealer or negotiate on a private sale.
The process
How Ute Finance Works
Tell us about your ute and business
Share the ute you want, how you'll use it and your business structure.
We compare the market
We search the panel for rates and structures suited to your situation.
Review your options
Structures and rates explained simply before you decide.
Get your keys
We manage settlement and your work ute is ready to go.
Ute finance, explained plainly.
Step 1 of 5
Understand ute finance
A work ute is financed as a commercial asset when the business uses it to earn, with the vehicle held as security and the interest registered on the PPSR.
Whether the loan is written as consumer or commercial lending depends on how you use the ute, not on which ute it is.
Terms run from one to seven years, and trays, canopies and racks can be financed with the vehicle when they form part of the purchase.
Why choose ute finance
For a trade, the ute is the business. Financing keeps cash available for tools, materials and wages instead of tying it up in a single vehicle.
Fitting the ute out at the time of purchase is easier when the tray or canopy goes on the same loan, rather than being paid for separately later.
GST and depreciation may apply, depending on the structure you choose and how the vehicle is used. Confirm the treatment with your accountant.
Deciding if ute finance fits
If the ute mostly does private kilometres, consumer lending is usually the better fit, and it asks for different paperwork.
New utes sit inside almost every lender's policy. Used ones bring age rules into play, measured at the end of the term rather than the start.
Work utes live hard lives, so condition and history matter to a used purchase as much as the price does.
How to apply for ute finance
Bring the ABN, how long you have traded and the ute you are looking at, including any tray or canopy that goes with it.
Low-doc options are available where your returns are not current. They run on the ABN, and some lenders ask for recent banking where the ABN is under 6 months old.
One enquiry reaches the panel, and pre-approval on a standard application is possible the same day.
Tips for ute finance
Decide on the fit-out before you apply, so the tray and canopy are financed with the vehicle.
Check the payload once the fit-out is on. A ute loaded with a service body carries far less than the brochure figure suggests.
Keep the tax question with your accountant from the start, because how the ute is used affects what can be claimed against it.
Ute finance at a glance
- How you use the ute decides whether the loan is commercial or consumer
- Trays, canopies and racks can be financed as part of the purchase
- Used utes bring age rules into play, measured at the end of the term
- Low-doc options run on the ABN where returns are not current
- One enquiry compares lenders rather than approaching each in turn
Ute Finance Built for Tradespeople
A work ute is one of the most common business asset purchases in Australia. We make the finance side straightforward.
Get my quoteA Panel of Lenders
We compare commercial vehicle and fleet lenders across our full panel to find the right structure for your business.
Same Day Pre-Approval Possible
Know your borrowing power before you commit to a purchase or tender a fleet order.
All Vehicle Categories
From light commercial utes and vans to heavy trucks and semi-trailers, we finance the full commercial range.
Fleet Finance Available
Financing multiple vehicles for your business? We arrange fleet structures that scale with your operation.
Low Doc Options
Self-employed and small business owners with non-standard income documents are catered for.
Rate Comparisons Upfront
We present rates and structures side by side, jargon-free, before you commit to anything.
Commercial Finance Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$1,437
per month
Weekly
$332
Total repayment
$68,965
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteMore Commercial Finance Options
Choosing the Right
Structure.
There are several ways to finance a ute, and the right one depends on how the business is set up and how the ute is used. Your broker matches the structure to the business, and you confirm the treatment with your accountant.
Commercial Finance Guides
Written by a licensed broker for Australian businesses.
 4 guidesCommercial financeUtes, trucks and work vehicles for ABN holders, including low-doc options.Explore commercial finance
 Chattel Mortgage Explained: The Complete GuideThe chattel mortgage is the workhorse of Australian business vehicle finance. How it works, who it suits, how balloons fit.
 Ute Finance for Tradies: The Complete GuideYour ute is a tool of trade, and financing it right matters. Structures, fitouts, self-employed income, new versus used.
 Truck Finance 101: Owner-Drivers and FleetsHow truck finance works in Australia, from a first prime mover to a growing fleet, covering what lenders assess, structures and terms, and trailers.
 Low-Doc Commercial Finance: What You Need to QualifyLow-doc commercial finance funds business assets on alternative income evidence. What lenders accept, how ABN age and credit feed the decision.Browse the full guide library
Who we help
Who We Help with Ute Finance
Builders and Carpenters
Quality ute finance for building tradespeople with tools and materials to carry.
Electricians and Plumbers
Work ute finance suited to licensed tradespeople operating as sole traders or small businesses.
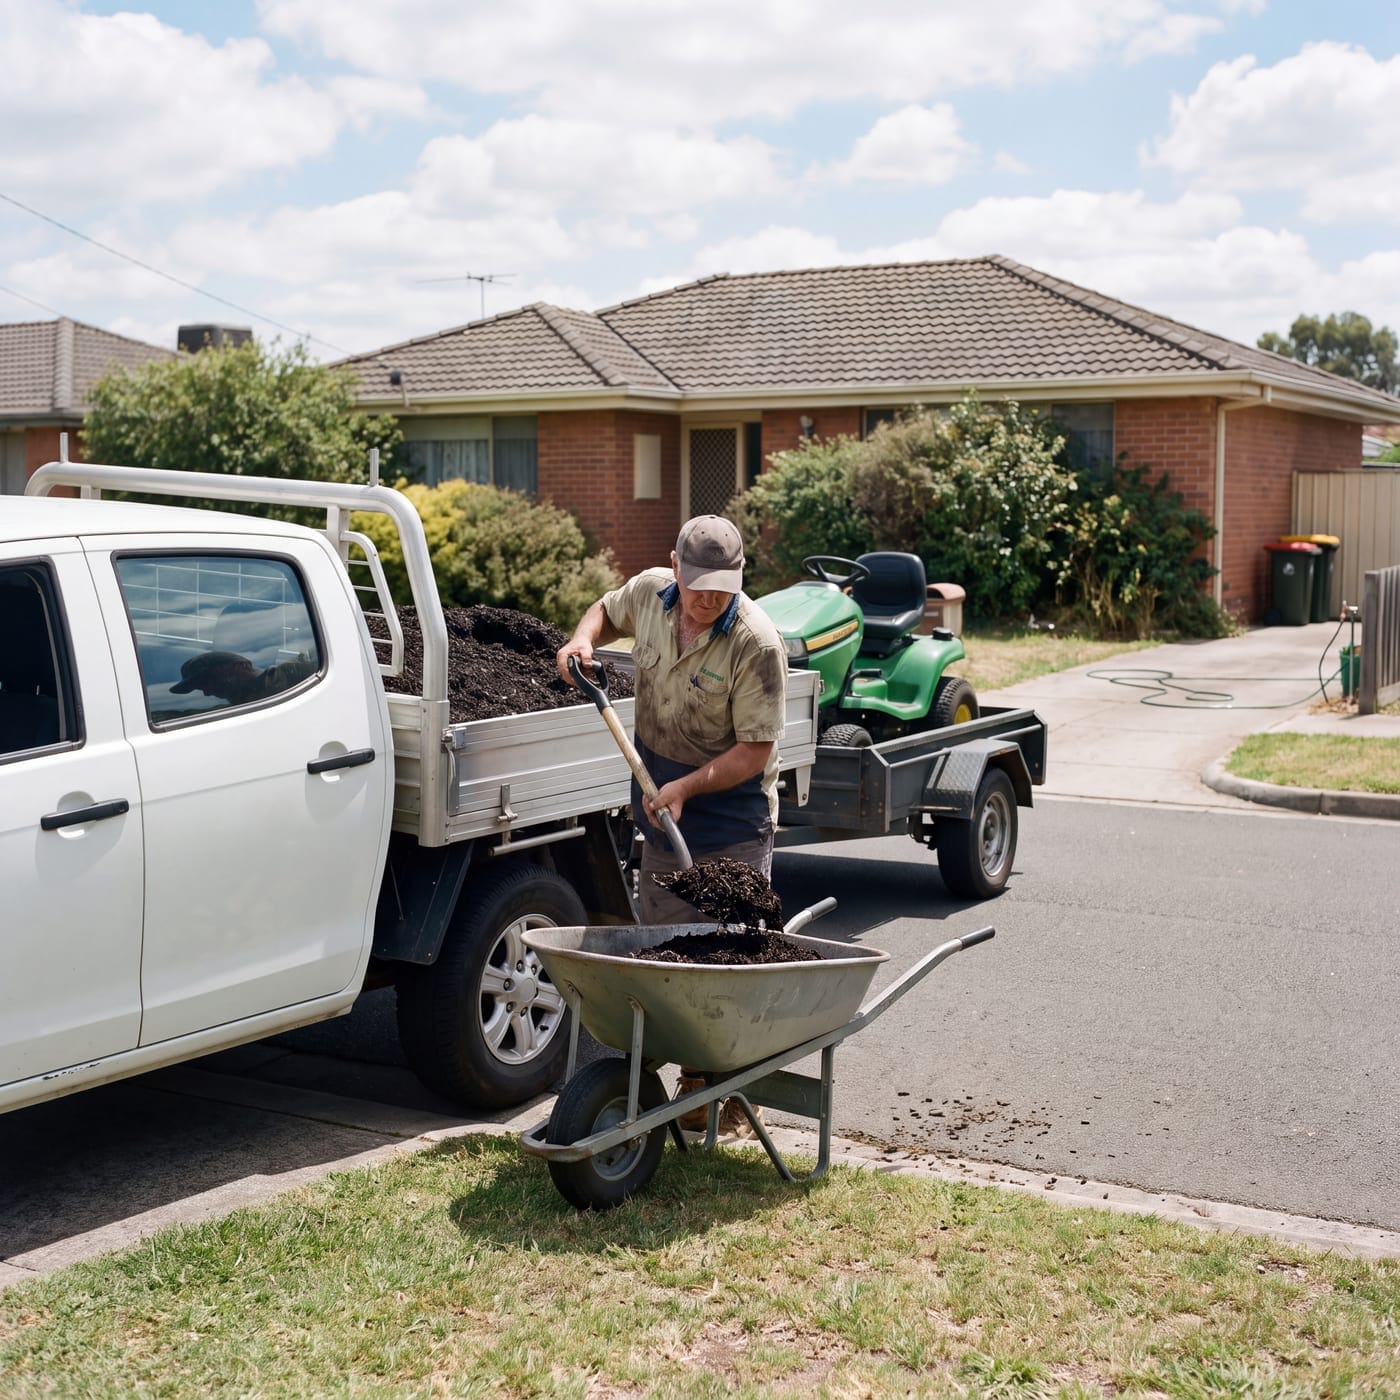
Landscapers
Dual cab and single cab ute finance for landscaping and garden service businesses.
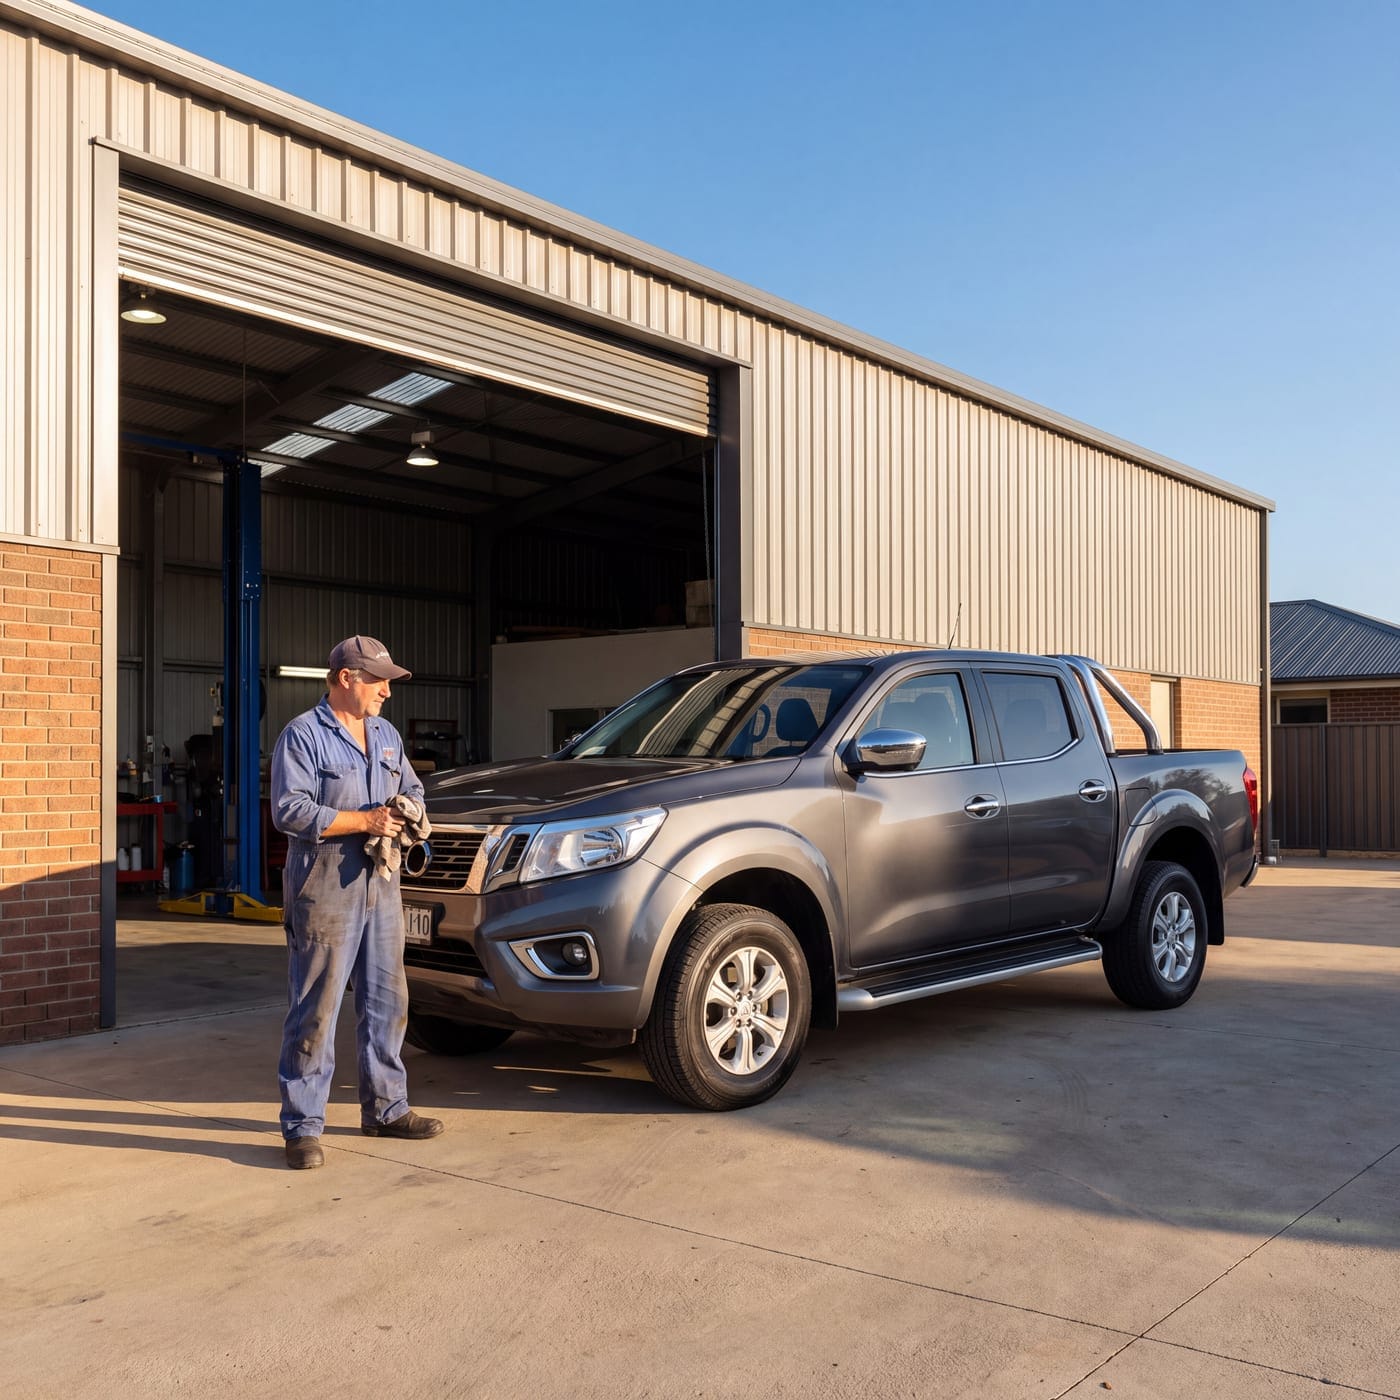
Mechanics
Work utes for mobile mechanics and automotive service operators.
Small Trade Businesses
Any trades business needing a reliable work ute financed the right way.
Australian citizen or permanent resident
ABN registered or standard employment
Vehicle to be used for business or personal purposes
Acceptable credit history
Income documentation available (payslips, BAS or financials)