
Low-Doc Caravan Finance. Built for Self-Employed Buyers.
Self-employed and don't have payslips? Morella Finance works with specialist lenders who accept alternative income documentation for caravan and motorhome loans.
Specialist self-employed lenders · ABN welcome · Minimal paperwork · Fast decisions
LOW-DOC vs STANDARD
Low-doc caravan finance versus standard lending.
Standard vs low-doc caravan finance
Standard lenders require documentation self-employed buyers often can't provide
Two years of tax returns, company financials and PAYG summaries. Low-doc lenders use alternative evidence instead.
Paperwork stays minimal
Your driver's licence typically does the whole job. A newer ABN, under 6 months, is the one situation where some lenders want banking too.
Pre-approval can move quickly
Specialist lenders assess a shorter document set, so straightforward low-doc applications can be pre-approved faster than standard finance, sometimes the same day.
Commercial structures for business use
Low-doc finance is business lending. Where the caravan is used in your business, a commercial structure such as a chattel mortgage applies.
The process
Low-Doc Caravan Finance. In 4 Steps.
Tell us about your business and the van
How long you've had your ABN, a basic rundown of what your business does, and the caravan or motorhome you're looking at.
We identify suitable lenders
Your broker matches your documentation to the right specialist lenders.
Submit your evidence
Usually just your driver's licence. Some lenders may also ask for a few months of banking if your ABN is under 6 months old.
Pre-approval and settlement
Pre-approval issued and paperwork handled end to end.
| Document | What it tells the lender | When it is asked for |
|---|---|---|
| Driver's licence (front and back) | Confirms your identity | Required in almost all cases. For most applicants, this is the only document needed |
| Active ABN | That the business is genuinely trading, or has continuity in the industry | Required. Some lenders will finance a brand new ABN where you've moved straight from PAYG employment in the same trade, for example an electrician going out on their own |
| Recent bank statements (for new ABNs) | Extra confidence where trading history is limited | Requested by some lenders when the ABN has been registered for less than 6 months |
Low-doc caravan finance, explained plainly.
Step 1 of 5
Understand low-doc caravan finance
Low-doc caravan finance serves self-employed buyers and ABN holders.
The assessment is built on the applicant's profile and ABN history instead of on lodged tax returns, which removes the wait for a return to be finished before you can buy.
In most cases the only documentation needed is a driver's licence. Banking is only required with some lenders, and generally where the ABN is under 6 months old.
Why choose low-doc caravan finance
Business income frequently shows lower on paper than the business generates, and a low-doc assessment avoids being judged on that gap.
It also keeps the timing workable. Travel plans and van availability rarely wait for an accountant to complete a lodgement.
A newly registered ABN is not an automatic barrier, particularly where the work continues on from previous employment in the same field.
Deciding if low-doc caravan finance fits
If your returns are current and straightforward, a full-doc application opens more of the panel.
Low-doc earns its place where returns are outstanding, where income is seasonal, or where you are looking for the quickest and easiest route.
The van still has to suit a lender that offers low-doc on caravans, so the documentation and the asset are decided together rather than separately.
How to apply for low-doc caravan finance
Have your ABN details and licence ready, along with the van or motorhome you are considering. Those three shape the shortlist.
Keep a few months of banking on hand if the ABN is newer, so a request does not hold up an otherwise quick application.
Try not to apply to several lenders directly. Every attempt marks your file, where one well-matched application does the same job.
Tips for low-doc caravan finance
Confirm your ABN registration details are current before applying, since out-of-date details stall files that would otherwise sail through.
Say whether the van is for private travel or business use at the outset, because the two sit in different parts of the panel.
Ask your broker exactly what the recommended lenders need, so you are not gathering documents nobody asked for.
Low-doc caravan finance at a glance
- The file is built on your ABN rather than on lodged tax returns
- A licence carries most applications, with banking sometimes asked for under 6 months of ABN
- A newly registered ABN is considered where the work continues from previous employment
- The van still has to suit a lender that writes low-doc on caravans
- Lenders are compared in one go, with same day pre-approval possible
Caravan Finance That Works for How You Earn
Banks want payslips and tax returns. Your income doesn't always come in that form. We have specialist lenders who assess caravan loan applications using alternative documentation.
Get my quoteAll Caravan Types
Pop-top, full-caravan, motorhome, campervan, off-road. All financed.
New and Used
Dealer and private sale caravans considered.
Fast Pre-Approval
Know your budget before visiting any dealer or seller.
Self-Employed Welcome
Low-doc options for ABN holders.
Direct Seller Payment
For private sales we pay the seller directly, keeping settlement secure for both sides.
One contact, start to finish
One contact from enquiry to settlement. No handoffs, no repeated explanations.
Caravan Finance Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$773
per month
Weekly
$178
Total repayment
$46,399
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteAbout the starting rate
6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
More Caravan Finance Options
A caravan's age
matters most.
Caravans come with lending restrictions a car never faces, including age limits and private sale rules. Your broker matches the caravan you actually want to the lenders whose policy accepts it.
Caravan Finance Guides
Written by a licensed broker for Australian borrowers.
 8 guidesCaravan financeCaravans, camper trailers and motorhomes, bought from a dealer or privately.Explore caravan finance
 Caravan Finance for Self-Employed and ABN HoldersRunning your own show should not stand between you and a caravan. What lenders actually ask of ABN holders, and how to place the application well.Australia's caravans are getting heavierAustralia's caravans are getting heavier. Vans over 2,500kg tare rose 32% in two years. See caravan weight by state from BITRE's 2026 registration data.New vs Used Caravan Finance: Which Is Right for You?New and used caravans borrow the same way but are assessed quite differently. How lender appetite, age rules and structure shift between the two.How Caravan Loan Pre-Approval WorksSorting your caravan budget before you shop changes how dealers and private sellers treat you. How pre-approval works and how to use it well.See all 8 caravan finance guides
Who we help
Who We Help with Low-Doc Caravan Finance
Tradies
Caravan for remote work travel or accommodation.
Freelancers
Variable income, strong bank history, no payslips.
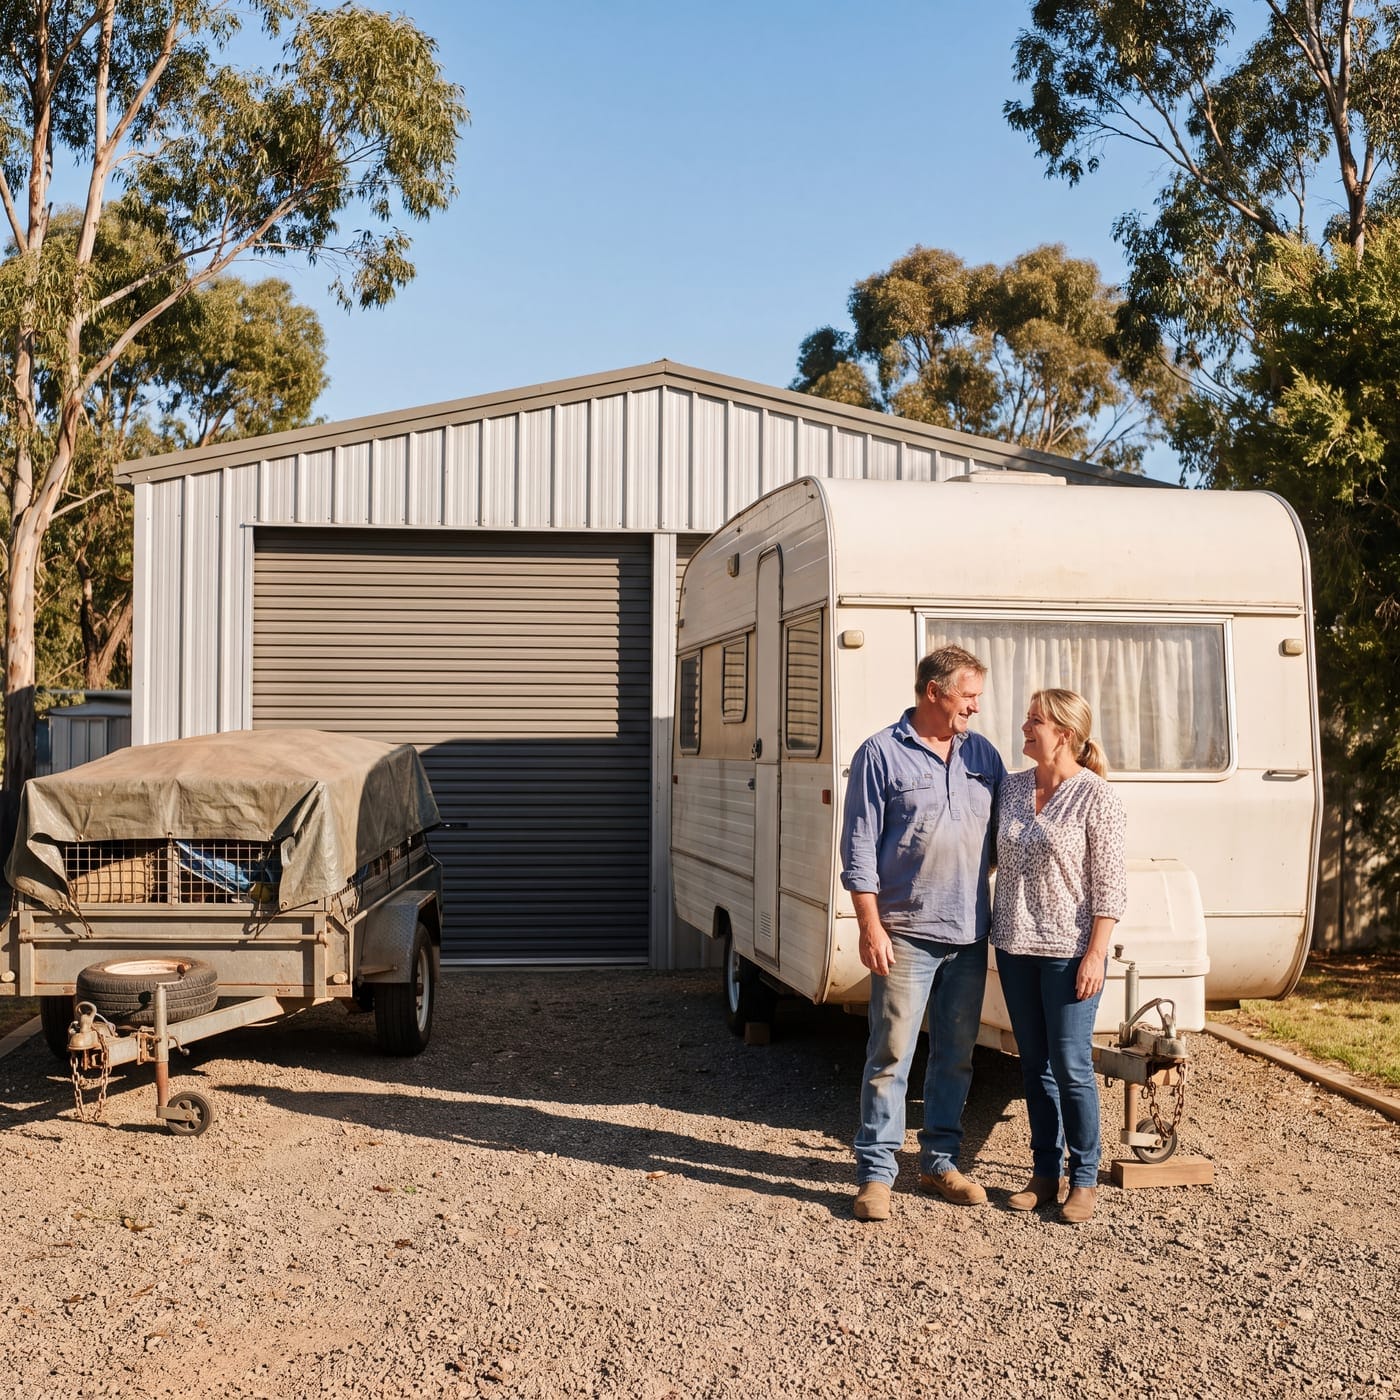
Small Business Owners
Established ABN, strong cashflow, limited formal financials.
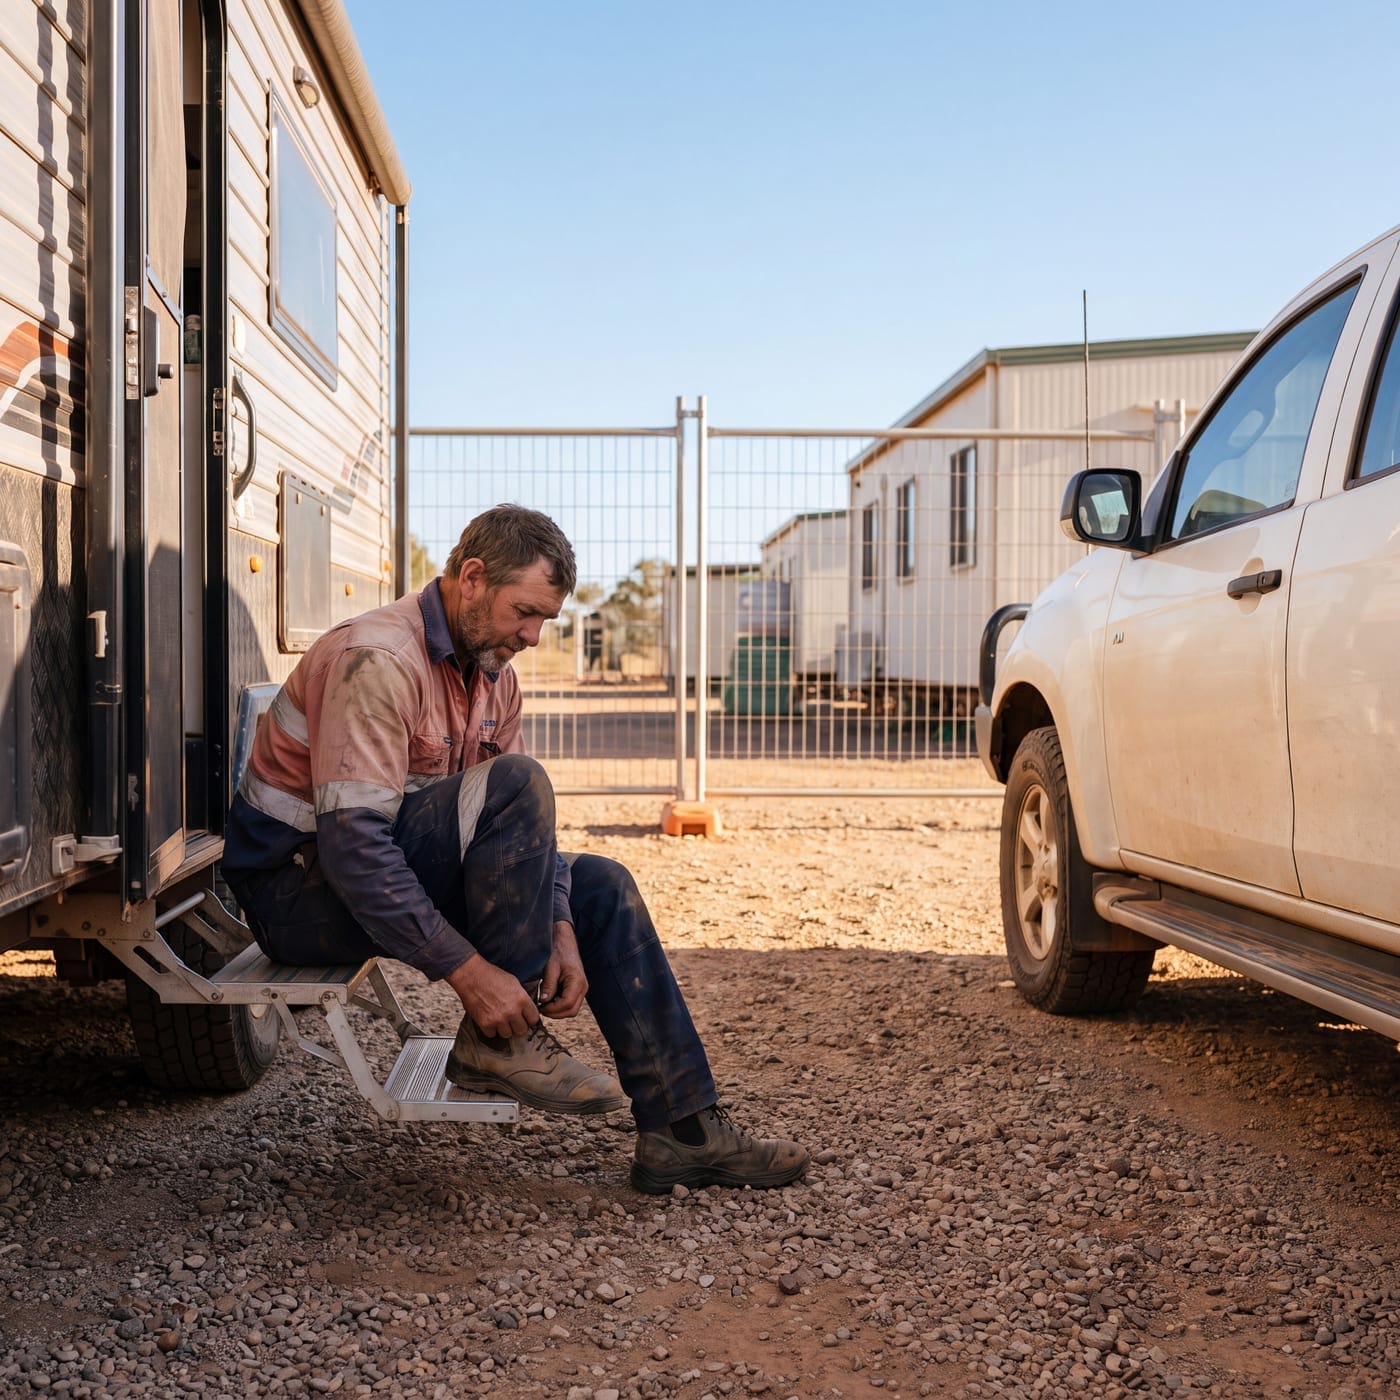
Travelling Workers
Caravan for extended regional work placements.
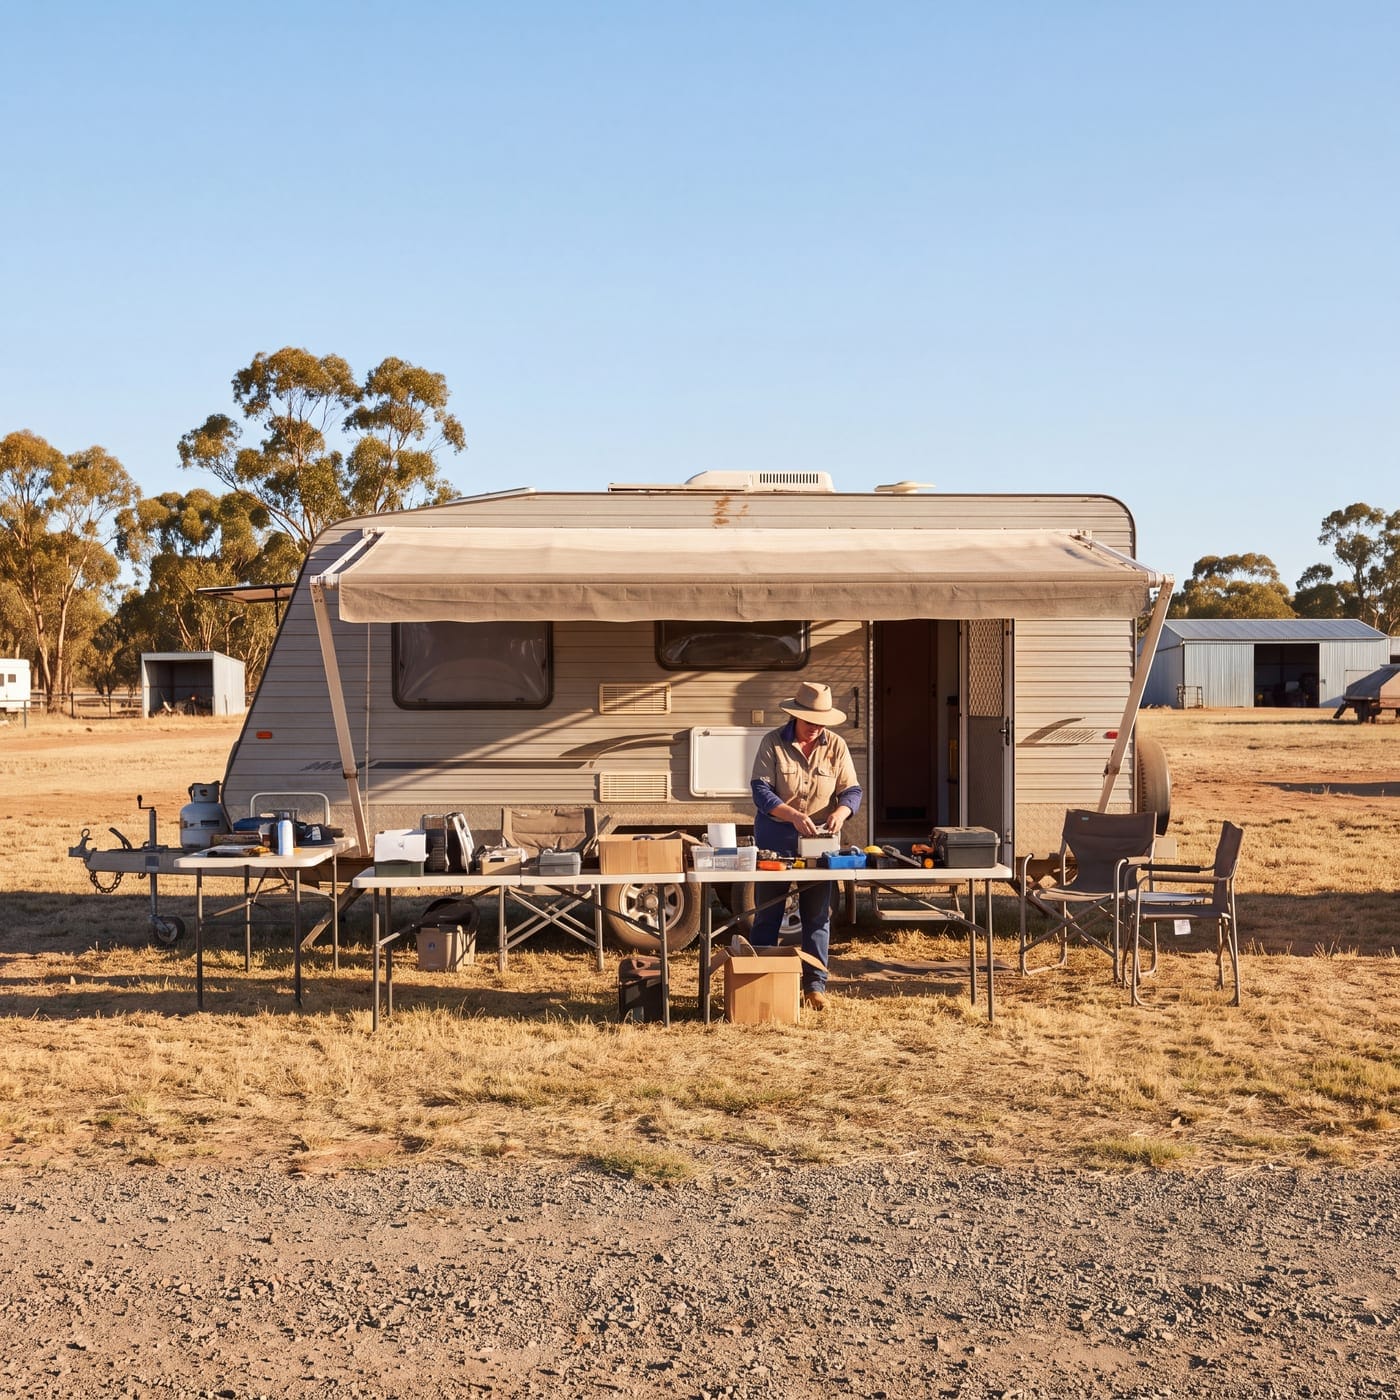
Mobile Business Operators
Caravan used as mobile business or office.
18 years or older
ABN registered (brand new to established, lender-dependent)
Australian citizen, permanent resident, or eligible visa holder
Driver's licence (front and back), with banking sometimes requested for ABNs under 6 months old
Credit history reviewed holistically
Low-Doc Caravan Finance. Common Questions.
Low-doc caravan finance is designed for self-employed Australians and ABN holders who cannot provide standard income documentation. The application runs on your licence and ABN rather than financial statements, and some lenders will even take on a brand new ABN when the business continues work you previously did as an employee.
No. Low-doc lending doesn't rely on tax returns. Your licence handles identification, your ABN confirms your business, and banking is only needed if your ABN is newer. Your broker tells you exactly what documentation the recommended lenders require.
Most specialist low-doc lenders require a minimum of 12 months ABN registration. Some prefer 24 months. We do have lenders that can offer finance to new ABNs depending on other factors. Newer ABNs face more limited options. Your broker will assess which lenders will consider your specific ABN tenure.
Straightforward low-doc applications can be pre-approved quickly, sometimes the same day, because specialist lenders assess a shorter document set. Your broker will give you a realistic timeframe once they see your documentation.
If the caravan is used primarily for business, ask your accountant how the finance affects your tax position. Your broker identifies the right loan structure.
Low-doc caravan finance is typically available up to $300,000 depending on the lender and your ABN trading history. Your broker gives a realistic borrowing estimate based on your documentation.