
Marine Finance
Buying a Boat Privately: Finance, HIN and Encumbrance Checks
By Joseph Nowland, Director and Senior Finance Broker · · 6 min read
Can you get finance for a private boat sale?
Yes. Boats change hands privately more than almost any other financed asset, and lenders have built private sale boat finance processes to match. The loan is the same secured structure as any used boat loan. The difference is the verification and settlement work wrapped around it.
Three questions have to be answered before money moves. Does the seller actually own the boat, is anything still owed against it to another financier, and will the payment land safely? A dealer answers those questions by existing. In a private purchase, the process answers them instead, and each step protects you as much as the lender.
Here is how a private boat purchase with finance usually runs.
- Get pre-approval first. Pre-approval before you negotiate keeps the timeline tight.
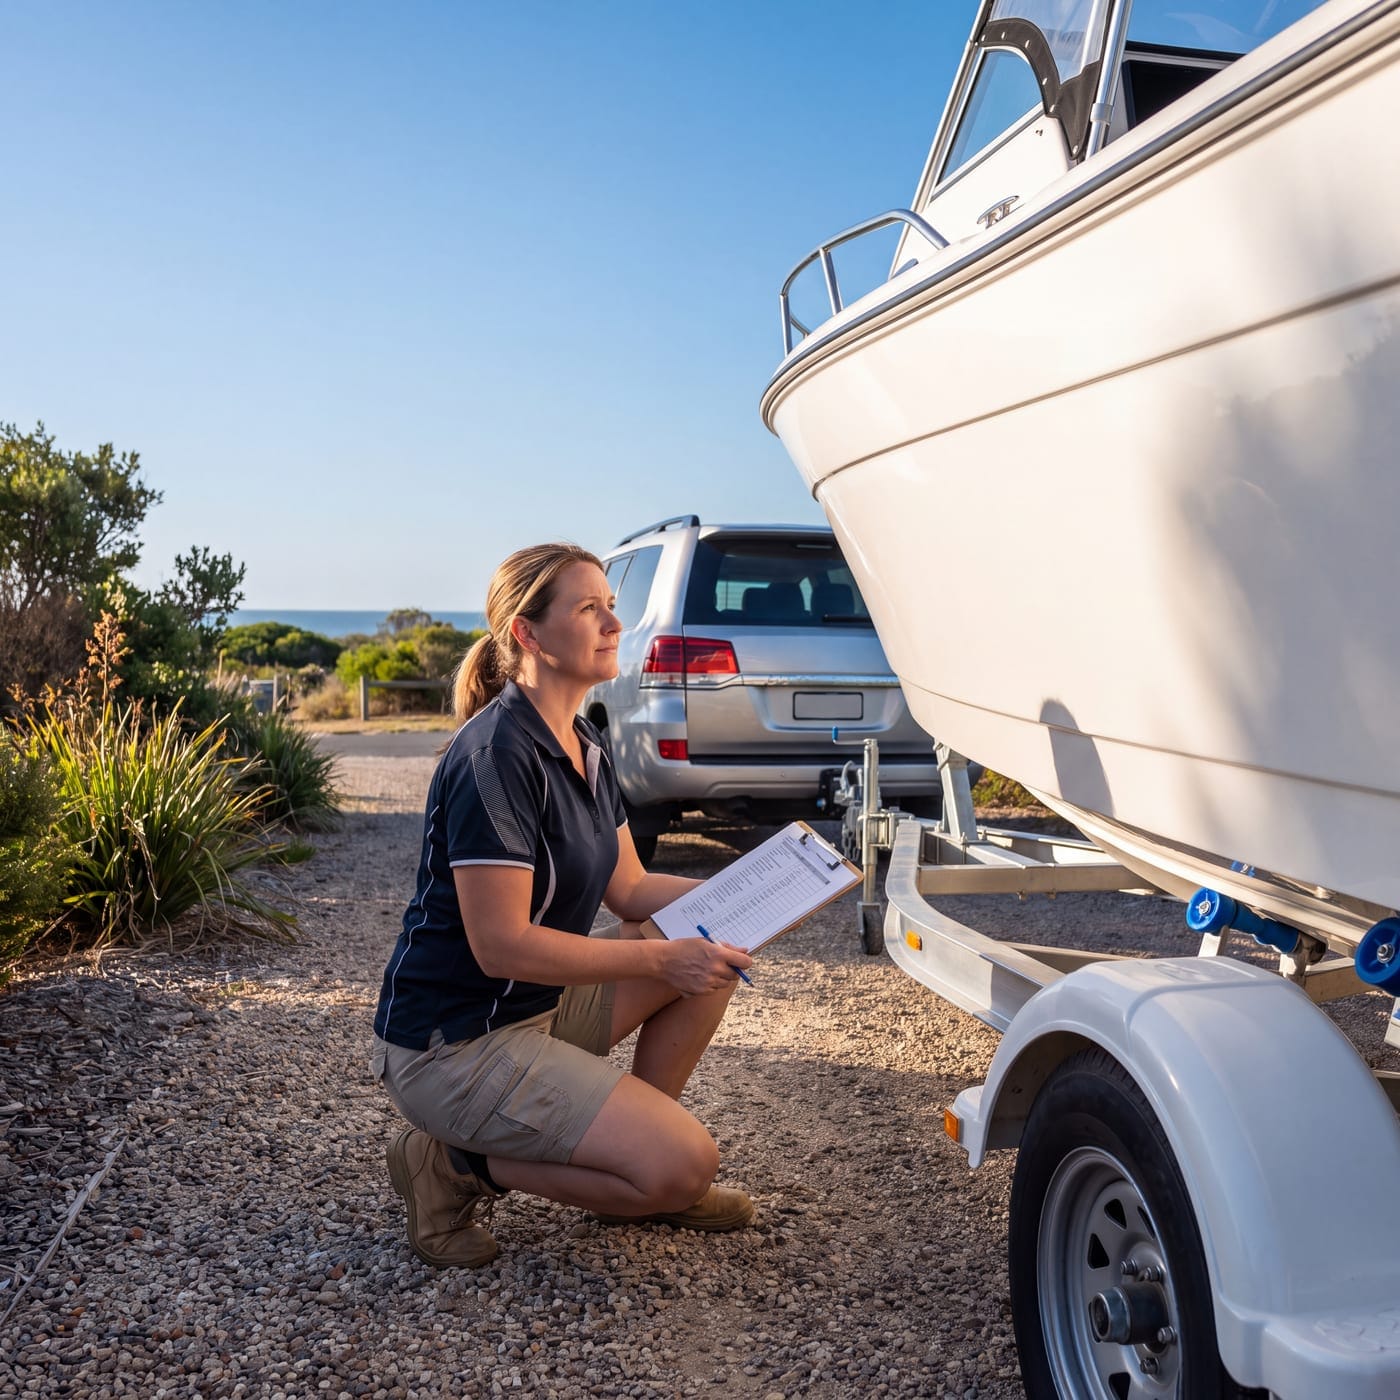
- Check the HIN. Confirm the HIN on the hull matches the registration papers and the seller's description. A missing, damaged or mismatched HIN needs resolving before any money moves.
- Search the PPSR on all three assets. Check the hull, the outboard motor and the trailer, since any of them can carry its own encumbrance. Your broker or lender runs these checks, and you can also search the PPSR yourself early in the negotiation.
- Arrange an inspection. An independent inspection is worth arranging even when the lender does not require one. For larger vessels, a proper survey does the same job.
- Collect the seller's documents. The seller provides photo ID, registration papers for the boat and trailer, the HIN and engine serial details, and bank details for payment. If finance is owing, they also provide a payout letter.
- Settle through the lender. Your lender pays the seller directly, or pays the seller's financier first to clear the encumbrance. Allow roughly one to three business days from formal approval to settlement.
- Collect the boat and transfer the registrations. Once payment clears, you collect the boat and transfer the registrations. An interstate purchase generally means re-registering both the boat and trailer in your home state.
What is a HIN and why does it matter?
The Hull Identification Number is the boat's equivalent of a vehicle's VIN, a unique code moulded or affixed to the hull that identifies the vessel regardless of who owns it or which state it is registered in. Australian-supplied boats have carried HINs for decades, and state registration systems key off them.
For finance, the HIN is how the boat is identified on the Personal Property Securities Register (PPSR) and in the loan security. Before settlement, confirm the HIN on the hull matches the registration papers and the seller's description. A missing, damaged or mismatched HIN is a stop sign. It can indicate an unregistered import, a rebuild or, at worst, a stolen vessel, and it needs resolving before any money moves.
How do encumbrance checks work on a boat?
A PPSR search against the boat's identifiers shows whether any lender holds a registered security interest over it. Buy an encumbered boat without clearing the debt and the previous owner's lender can still have rights over your new pride and joy. The search is quick, inexpensive and non-negotiable.
Boats have a wrinkle cars do not, because the package often includes three separately identifiable assets. The hull carries the HIN, the trailer has its own registration and identifiers, and an outboard motor has a serial number. Any of the three can be separately encumbered, so a thorough check covers the boat, the motor and the trailer rather than stopping at the hull.
Your broker or lender runs these checks as part of settlement, but there is nothing stopping you searching the PPSR yourself early in the negotiation. Finding an encumbrance is not fatal. It just means the seller's loan gets paid out at settlement, documented properly.
| Part | How it is identified | What to check |
|---|---|---|
| Hull | Hull Identification Number (HIN) | The HIN on the hull matches the registration papers and the seller's description, and a PPSR search shows nothing owing |
| Outboard motor | Serial number | A PPSR search against the serial number, plus the engine serial details from the seller |
| Trailer | Its own registration and identifiers | A PPSR search against the trailer, plus its registration papers from the seller |
Ready to compare your options?
A broker searches the panel so you see what they can offer for your profile. Takes two minutes.
Get my quoteHow does settlement work in a private boat sale?
The lender pays the seller directly. The seller provides bank details and, where money is still owing on the boat, a payout letter from their financier. At settlement, funds flow from your lender to the seller, or partly to the seller's financier first to clear the encumbrance, with every step documented.
This is exactly the protection a private sale needs. The seller sees cleared funds from an institution, you get a documented transfer tied to the HIN and PPSR checks, and nobody exchanges a boat for a bank cheque in a car park hoping for the best. Once payment clears, you collect the boat, transfer the registrations, and the loan runs like any other secured marine loan.
Can you buy a boat interstate with finance?
Yes, and the best-priced boats are often a state away. Settlement is electronic, so the lender's checks and direct payment work identically at distance. What needs managing is the physical side. Inspect the boat where it lies or arrange an independent inspection there, because photographs conceal exactly the faults that cost money, and factor transport or the delivery drive into the budget.
Registration is state-based for both boat and trailer, and an interstate purchase generally means re-registering both in your home state, each with its own process. Check your state's requirements before settlement so the boat is not stranded, legally speaking, between systems. The documented settlement process through marine finance lenders suits interstate deals well, since verified ownership, cleared encumbrances and institution-to-institution payment protect two parties who may never meet.
What do you and the seller each need to provide?
You bring photo ID, proof of address, income evidence and the application paperwork your broker prepares. The seller brings photo ID, registration papers for the boat and trailer, the HIN and engine serial details, bank details for payment, and a payout letter if finance is owing.
An independent inspection is worth arranging even when the lender does not require one. Hulls hide moisture and repairs, outboards hide compression problems, and a marine mechanic's hour is cheap against a bad purchase. For larger vessels, a proper survey does the same job at scale, and our guide on trailerable vs moored finance explains when surveys enter the picture.
Allow roughly one to three business days from formal approval to settlement for the checks and direct payment to run. Pre-approval before you negotiate keeps that timeline tight, and one enquiry with Morella Finance puts the private-sale-friendly lenders from the panel side by side and manages the settlement end to end.
Checklist
Buying privately? Use our checklist.
The steps from finding a boat to picking it up, including what you do and what we organise with the seller and lender.
Frequently asked questions
It is handled routinely at settlement. The seller obtains a payout letter from their financier, your lender pays that amount directly to clear the encumbrance, and any balance goes to the seller. The PPSR registration is then discharged and the boat passes to you unencumbered.
Yes. The hull, outboard motor and trailer are separately identifiable assets and any of them can carry its own encumbrance. A thorough pre-purchase check searches the PPSR against all three, and your lender's settlement process verifies them as part of the security.
Slightly. Allow one to three business days from approval to settlement for ownership verification, HIN and PPSR checks and the direct payment to the seller. Having the seller's documents collected early, especially a payout letter if finance is owing, shortens the wait.
Ready to compare your options?
This guide is general information. When you are ready, see how it applies to your situation.

Popular loan types
This guide is general information, not financial or credit advice. Consider your circumstances and check details with your broker or accountant.
Start here
Compare lenders in two minutes
No obligation, no impact on your credit score at quote stage. A broker will follow up with real options matched to your situation.
Step 1 of 3
What are you financing?
Select a finance type and tell us your loan amount.
Keep reading
Related guides
 Boat Finance 101: The Complete GuideHow boat loans work in Australia, including what lenders assess, the documents you need and how the application runs from enquiry to settlement.
 New vs Used Boat Finance ComparedLenders read a new boat and a used one differently. Hull age, engine hours, surveys and private sales all shift the finance, and this guide explains how.How Boat Loan Pre-Approval WorksPre-approval settles your boat budget before you go shopping and strengthens your hand at boat shows, brokers' yards and private sales. How it works.