
Secured Personal Loan. Use an Asset to Reach More Lenders.
A secured personal loan uses an asset as collateral, giving lenders greater confidence and typically resulting in a lower interest rate than an unsecured loan. We compare secured personal lenders across our full panel to find the right rate for your situation.
Secured personal loan options. Same day pre-approval possible.
Secured vs Unsecured: Which Is Right for You?
Broker vs bank,
a real comparison
Lower rates with security
Secured personal loans typically offer lower rates than unsecured options because the lender can claim the asset if you default.
Higher borrowing potential
The presence of security can increase the maximum amount a lender is willing to approve.
Broader eligibility
Borrowers who might not qualify for an unsecured loan at a competitive rate may find secured lending more accessible.
Rate comparison across the market
We compare secured personal lenders across the panel to find a rate and structure that suits your profile and asset.
The process
How a Secured Personal Loan Works
Tell us about your loan and asset
Share the purpose, amount and the asset you intend to use as security.
We assess and compare
We search secured personal lenders on our panel for rates suited to your profile and security type.
Review your options
We present matches with rates and terms explained clearly.
Apply and receive funds
Once you choose, we manage the application. Funds are disbursed when approved.
Secured personal loans, explained plainly.
Step 1 of 5
Understand secured personal loans
A secured personal loan uses an asset you own, most often a vehicle, as security for the loan, with the lender's interest recorded on the PPSR.
Holding security reduces the lender's exposure, which is why this structure exists alongside the unsecured version of the same product.
The registration is discharged when the loan is paid out, and the asset is then clear again.
Why choose a secured personal loan
Offering security opens a wider part of the panel, so there are more lenders and more structures to compare.
It can also support a larger amount than an unsecured application would reach on the same profile, because the lender is not relying on income alone.
For borrowers whose credit history is still building, security is often what makes the application workable at all.
Deciding if a secured personal loan fits
It fits where you own a suitable asset outright and are comfortable with an interest being registered against it for the life of the loan.
It's worth knowing that you can still sell the asset during the term, though the loan would need to be paid out as part of that sale.
Not every asset qualifies. Age and condition rules apply the same way they do in asset finance, and vary from lender to lender.
How to apply for a secured personal loan
Describe the asset you intend to offer alongside your own details, since the two are assessed together rather than separately.
Identification, income evidence and confirmation you own the asset outright make up a standard file.
Your broker compares the panel in one enquiry and manages the security registration through to settlement.
Tips for secured personal loans
Be sure about the asset before you offer it. An interest registered against something you plan to sell soon creates work you did not need.
Check whether the asset meets the lender's age rules before the application, rather than discovering the limit partway through.
Keep the asset insured for the term. Lenders generally expect it, and it protects the asset your loan is secured against.
Secured personal loans at a glance
- An asset you own is attached to the loan and registered on the PPSR
- Security opens a wider part of the panel than an unsecured application reaches
- The registration is discharged once the loan is paid out
- Asset age and condition rules apply and vary between lenders
- Lenders compared in one enquiry, with pre-approval possible the same day
Secured Personal Loans: The Rate Advantage
Providing security reduces the lender's risk. That reduction in risk is typically passed on as a lower interest rate. For larger loan amounts, the rate difference between secured and unsecured can be meaningful over the life of the loan.
Get my quoteA Panel of Lenders
We compare personal finance lenders across our full panel to find the right rate and structure for your situation.
Same Day Pre-Approval Possible
Know what you qualify for before you commit to a purchase or expense.
Matched to Your Situation
We assess whether a secured structure suits your asset and circumstances, then match you with lenders on the panel who work that way.
Debt Consolidation Specialists
We arrange consolidation structures that combine multiple debts into a single repayment.
Honest Rate Comparison
We present rates from multiple lenders side by side so you can see the full picture before committing.
No obligation to proceed
Review your options with no pressure. You're not committed until you choose to proceed.
Personal Loan Repayment Calculator
Estimate your repayments. Adjust the sliders to match your situation.
Monthly repayment
$456
per month
Weekly
$105
Total repayment
$16,428
Estimates only. Your actual rate depends on your profile and lender. Get a real comparison.
Get my quoteAbout the starting rate
6.00% p.a. is a starting point for estimating repayments only. It is not a quote, not an offer of finance, and not a rate available to every applicant. Your actual rate depends on the lender, the asset, the loan term, the loan amount and your circumstances. Adjust to model scenarios.
More Personal Finance Options
Same amount.
Not the same loan.
Personal lending varies by purpose, by security and by lender appetite. Your broker compares the market against the reason you are borrowing, not just the amount.
Personal Finance Guides
Written by a licensed broker for Australian borrowers.
 5 guidesPersonal financeTravel, weddings, home improvements and debt consolidation.Explore personal finance
 Fixed vs Variable Personal Loans ExplainedWhat fixed and variable personal loans actually mean for your repayments, flexibility and planning, and which suits the way you intend to repay.
 Personal Loans 101: The Complete GuideHow personal loans work in Australia, covering secured vs unsecured, fixed vs variable, what lenders assess and what borrowing actually obliges you to.Travel Loans: What to Know Before You BorrowHow travel loans work, when borrowing for a trip is reasonable and how to structure holiday finance so the repayments end soon after the trip does.Wedding Loans: Financing the Day Without the StressHow wedding loans work in Australia, how to decide what to borrow responsibly and how to structure finance so the celebration does not follow you for years.See all 5 personal finance guides
Who we help
Who Uses Secured Personal Loans?
Vehicle Owners
Using a car or motorbike already owned as security on a new loan.
Recreational Asset Holders
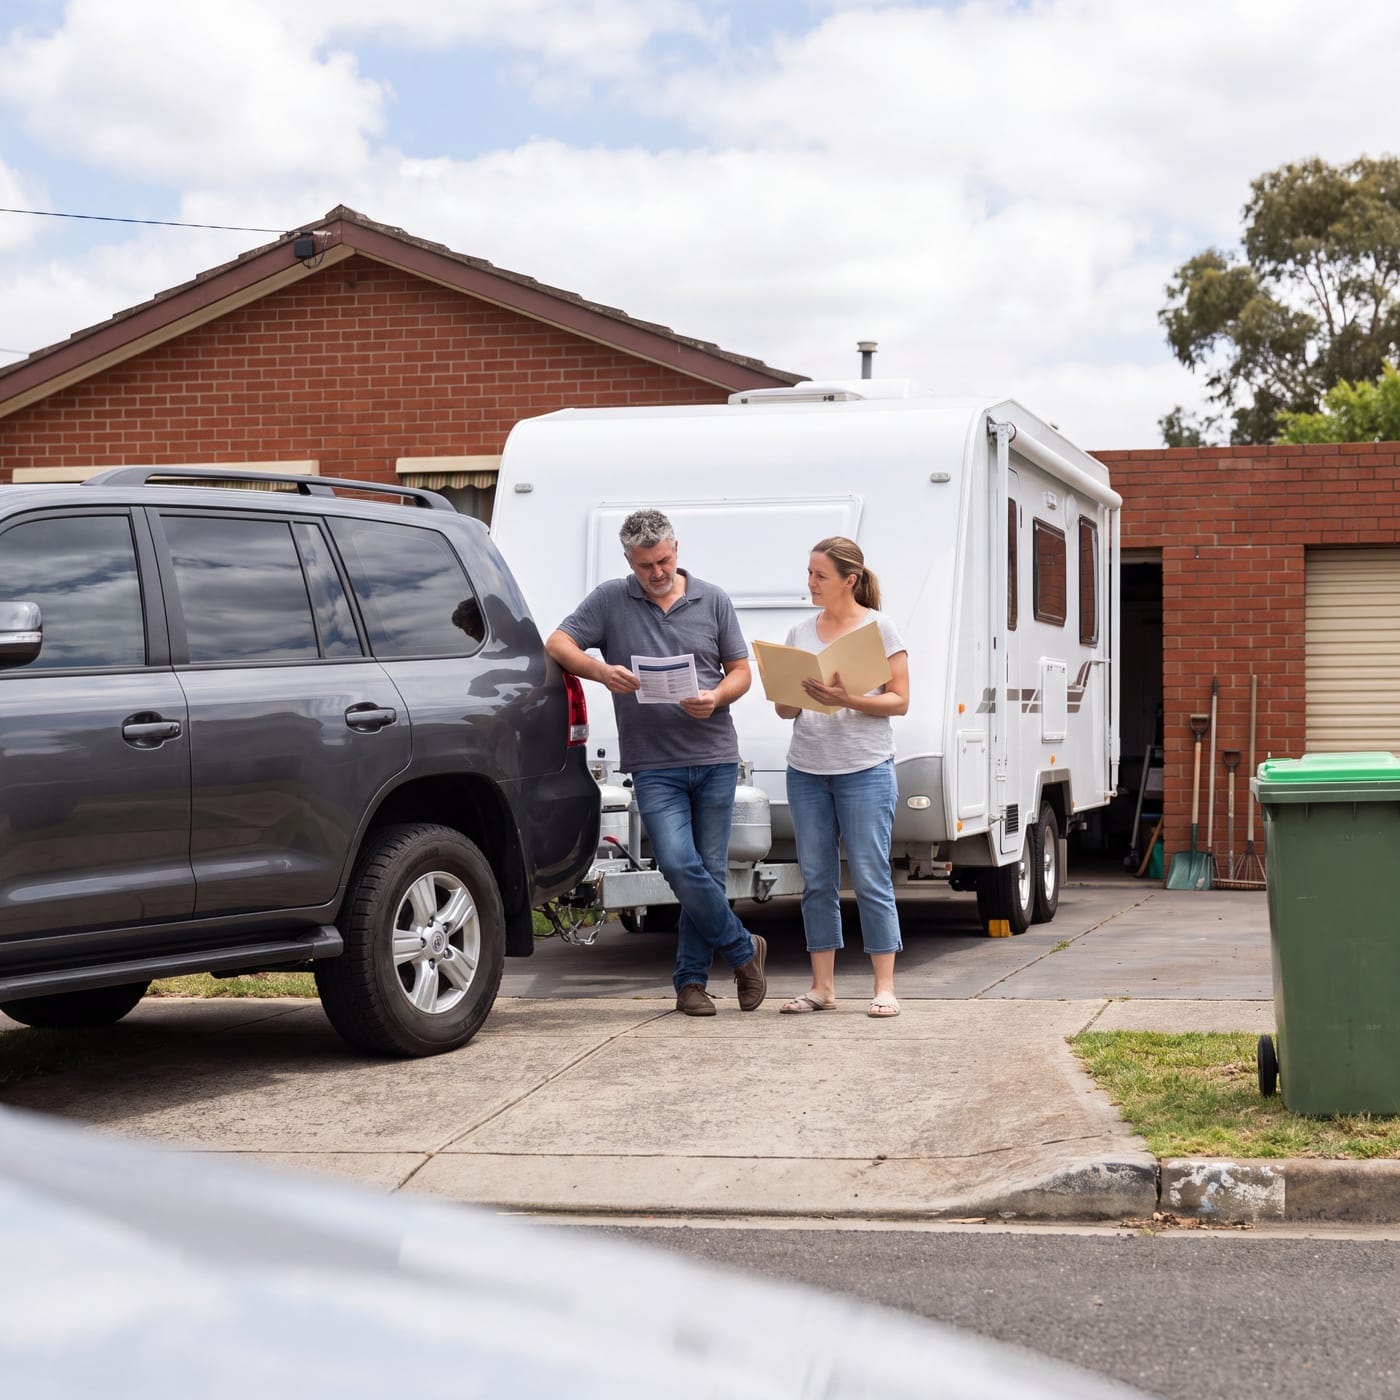
Caravan or boat owners leveraging an existing asset to improve loan terms.
Term Deposit Holders
Using a term deposit as low-risk security for a personal loan.
Larger Amount Borrowers
Borrowers seeking amounts where the rate difference between secured and unsecured is most significant.
Consolidators with Assets
Using an asset as security on a debt consolidation loan.
Australian citizen or permanent resident
Aged 18 or older
Stable income (PAYG or self-employed)
An acceptable asset to use as security
Acceptable credit history
Ability to service the loan repayments
Secured Personal Loan FAQs
Common security types include registered motor vehicles (cars, motorbikes, utes), caravans and boats. Some lenders also accept other assets. Acceptability depends on the lender's policies, the asset's age and its assessed value. We advise on what your intended security is worth to lenders.
Security reduces the lender's exposure, which is why secured lending reaches a wider part of the panel. Which lenders will consider you varies with your credit profile. We compare both options so you can see the actual difference for your situation.
If you default on a secured loan, the lender has the right to repossess and sell the secured asset to recover the outstanding debt. This is the key risk of secured lending. We explain this clearly before recommending a secured product.
No. The asset needs to be unencumbered, meaning it's owned outright with nothing still owed on it, before it can be used as security. If you're still paying off the car, we can look at other options with you.
Yes. Self-employed borrowers are assessed on their income documentation, which may include tax returns or business bank statements. Having an asset as security can improve the available rate even for self-employed applicants.
We assess your profile first, which does not touch your credit file. A formal credit enquiry only occurs if you proceed to a full application, and some lenders don't hit your file at all unless it goes through to approval.
In most cases, pre-approval is achievable the same day. Final settlement timing can depend on confirming the security details. We advise on the expected timeline for your application.